


YNAB
Advertisements
App Specs
- Version
- 26.32.0
- Updated
- Nov 7, 2026
- Android Version
- 11
- Installs
- 1,000,000+
- Developer
- ynab.com
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
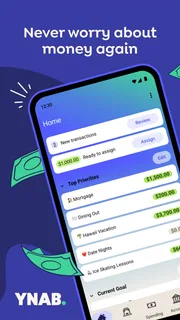
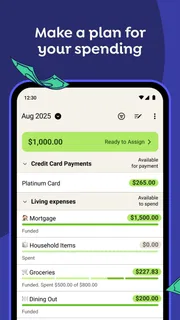
I approached YNAB as a first-time user looking for a clearer way to decide what my money should do, not just a record of where it went. Its central idea is to assign available money to specific purposes before spending it. That makes the app feel different from a basic expense tracker, and it can be a useful change if your usual method leaves you surprised by bills or short on cash at the end of the month.
YNAB is a finance app from ynab.com, available free to download for Android and iOS. It has a 4.5 average from around 24,000 ratings, with more than a million installs. The app is rated for everyone, though its budgeting approach asks for more attention than a set-and-forget tracker. The current version is 26.5.1, and the app has been available since October 20, 2015. In-app purchases range from $14.99 to $109.00 per item, so I’d check the subscription options shown in the app before deciding whether the ongoing cost suits you.
First Impressions and Setup
Getting started with YNAB is pretty straightforward. The app is available on both Android and iOS, and the download was a breeze. Once you open it, you're greeted with a clean, user-friendly interface that doesn’t overwhelm you with numbers and graphs. Instead, it gently nudges you to start budgeting by linking your bank accounts. I found the connection process secure and quick, which is always a win in my book.
Next, the app guides you through setting up your budget. It asks you to categorize your expenses, which might feel like a chore at first, but trust me, it’s worth it. The categories are intuitive, and you can customize them according to your lifestyle. Whether you’re saving for a vacation or just trying to keep your coffee spending in check, YNAB has got you covered.
For a smoother first session, I’d start with the money you can actually use now and a small set of categories you recognize immediately: housing, groceries, transport, and bills due soon. You can add detail later. Trying to recreate every past purchase or design a perfect category tree before making a plan can turn setup into homework. The useful first step is deciding what your available money needs to cover next.
Using YNAB Daily
Once my budget was set, I started using YNAB daily. The app encourages you to regularly check in and adjust your budget as needed. I found this feature particularly helpful because, let’s face it, life happens and sometimes you need to move money from one category to another.
What I love most about using YNAB is its proactive approach to budgeting. Instead of simply tracking what you’ve spent, it makes you plan ahead. This shift in mindset was a game-changer for me. It forced me to think about my spending habits and make informed decisions. Plus, it’s kind of fun to see your savings grow as you stick to your plan!
A practical first win is funding one near-term obligation, then checking the budget before making a flexible purchase. Imagine payday arrives and you have groceries to buy, a phone bill coming up, and a weekend meal with friends in mind. Giving the bill and groceries a place first makes the trade-off visible: you can still choose the meal, but you can see what you would need to move or postpone. That moment of choosing deliberately is more valuable than a colorful monthly chart.
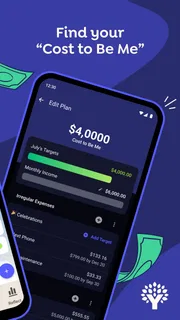
I’d also treat the budget as something to revise, not a promise that every estimate will be perfect. If groceries cost more than expected, move money from a less urgent category rather than treating the overspend as a failure. This workflow is especially useful for irregular expenses: set aside smaller amounts over time for annual renewals, car maintenance, or gifts instead of letting those costs appear to come out of nowhere. The benefit depends on returning to the plan often enough to notice when reality changes.
Features That Stand Out
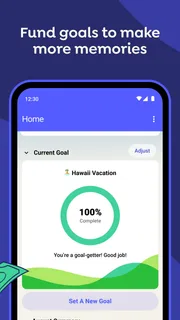
One of the standout features is the app’s ability to sync in real-time across multiple devices. So, if you’re budgeting with a partner, you both stay on the same page. Another cool feature is the goal-setting tool. Whether you’re saving for a new gadget or building an emergency fund, YNAB helps you visualize your progress and keeps you motivated.
Additionally, the app offers educational resources like workshops and tutorials, which are super helpful if you’re new to budgeting or need a refresher. I found these resources to be quite engaging and insightful.
Shared budgeting works best when both people agree on what the categories mean and who will update purchases. A quick check-in before a joint expense can prevent one person from assuming money is available while the other has already planned it elsewhere. For an individual user, the same habit helps: review categories together during a weekly reset, then make small adjustments instead of waiting until the month feels out of control.
Goals are most useful when they represent a real decision, not just a number to admire. I’d connect a goal to a specific expense and give it a priority, especially if several savings plans compete for the same dollars. If a target feels unrealistic, lowering the contribution or changing its timing is better than leaving it untouched and feeling behind. The app’s planning style makes those choices explicit, which is helpful but can also feel demanding if you prefer not to think about money frequently.
Challenges and Considerations
While I’m a big fan of YNAB, it’s not without its challenges. For starters, there’s a learning curve. If you’re used to traditional budgeting methods, transitioning to YNAB’s "give every dollar a job" philosophy might take some getting used to. However, once you get the hang of it, it’s incredibly rewarding.
Another consideration is that it’s not a free app. There’s a subscription fee, which could be a dealbreaker for some. But, in my opinion, the financial peace of mind it offers is worth the investment. Plus, they offer a free trial, so you can test the waters before committing.
The app’s free download should not be confused with a permanently free budgeting service: in-app purchases are offered, and the listed items span $14.99 to $109.00. That cost is easier to justify if actively planning helps you avoid missed bills or make progress toward savings. If you only want a quick spending snapshot, a spreadsheet or a simpler expense tracker may be enough, particularly if paying for a budgeting method would itself strain your budget.
There is also a difference between linking accounts and keeping a useful plan. Automatic syncing can reduce manual entry, but I would still review transactions and category balances rather than assume the budget is accurate without checking. If you prefer to avoid connecting financial accounts, you can decide whether a more hands-on budgeting routine is worth the effort for you. The key question is not whether every update happens automatically; it is whether you will keep the plan current enough to guide real decisions.
Compared with a traditional spreadsheet, this app gives the budgeting process more structure and makes moving money between categories part of the routine. A spreadsheet offers more freedom to build your own layout and may suit people who enjoy managing formulas. Compared with a passive expense tracker, YNAB asks you to act before and between purchases rather than mainly review past spending. That active approach is its strength for someone who wants to change habits, but a drawback for anyone who wants minimal maintenance.
I would be cautious about choosing it if your income is highly unpredictable and you want a budget that forecasts money you have not received. Its approach is most comfortable when you plan with money already available and adjust as circumstances change. It can still help someone with variable income, but they will need to make priorities clear and revisit the plan as funds arrive. If you need a simple record for reimbursement or taxes rather than a household spending plan, a dedicated tracking tool may fit better.
Making the Habit Stick
For a first week, I’d keep the routine modest: assign available funds, check the plan before a few purchases, and review what changed at the end of the week. That is enough to learn the logic without turning budgeting into an all-day project. When an unexpected expense lands, the useful question is which existing priority can make room for it. This turns a surprise into a concrete choice rather than a reason to abandon the whole budget.
If you share finances, agree on a simple rule for entering purchases and discussing changes. If you manage money alone, a short recurring review can help you catch overlooked bills and reset categories before the next pay period. Either way, consistency matters more than creating a flawless plan on day one. A budget that reflects actual decisions is more useful than an elaborate one you stop opening.
New users may wonder whether they need to connect a bank account immediately. I’d begin with the setup method that feels comfortable and focus on understanding the available-money plan; account linking is a convenience, not the purpose of budgeting. They may also wonder what to do when a category goes over. In practice, the next step is to move money from another category and decide whether that change reflects a one-off exception or a budget that needs adjusting for the future.
Final Thoughts
All in all, YNAB has been a game-changer in managing my finances. It’s more than just a budgeting tool; it’s a financial philosophy that encourages mindful spending and saving. If you’re serious about taking control of your money, I highly recommend giving it a shot. Who knows? You might discover a financial guru in yourself!
So, are you ready to let YNAB transform your financial life? Trust me, once you start seeing the benefits, you’ll wonder how you ever managed without it.
Pros and Cons
Pros
- User-friendly interface enhances budgeting.
- Real-time syncing across multiple devices.
- Customizable budget categories.
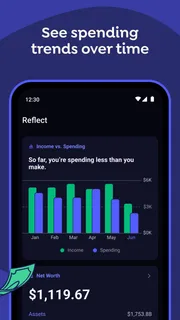
- Comprehensive financial reports.
- Strong community support and resources.
Cons
- Subscription-based model may deter users.
- Limited features in the free trial.
- No direct bank integration outside U.S.
- Learning curve for non-budgeters.
- No investment tracking features.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 YNABynab.com | 4.6 | 1,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is YNAB and how does it work?
YNAB, or You Need a Budget, is a personal finance app designed to help users manage their money by assigning every dollar a job. It uses a unique budgeting method that encourages proactive financial planning. Users input their income and expenses, and YNAB helps track spending, savings, and financial goals. It’s suitable for anyone looking to gain better control over their finances.
Is YNAB suitable for beginners in budgeting?
Yes, YNAB is beginner-friendly, offering comprehensive tutorials and educational resources to help new users understand the budgeting process. The app’s straightforward interface allows beginners to easily input financial data and track their progress, making it a great tool for those new to budgeting who seek to establish better financial habits.
What platforms is YNAB available on?
YNAB is available on various platforms, including Android, iOS, Windows, and macOS. This cross-platform availability allows users to access their budget from mobile devices and desktops, ensuring they can manage their finances on the go. The web app also offers seamless synchronization across all devices.
Does YNAB offer any financial guidance or support?
Yes, YNAB provides extensive support and educational resources to guide users. The app includes live workshops, video tutorials, and a helpful community forum. Additionally, YNAB’s support team is available to answer questions and provide assistance, ensuring users have access to the help they need to succeed financially.
Is there a cost associated with using YNAB?
YNAB offers a subscription-based model with a monthly or annual fee. While it does not have a free version, new users can take advantage of a 34-day free trial to explore the app’s features and determine if it suits their financial needs. Many users find the app’s benefits justify the cost.
Advertisements

Download YNAB
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 26.32.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.