


Inter Banking & Money Transfer
Banco Inter SA
Advertisements
App Specs
- Version
- 26.19
- Updated
- Nov 15, 2026
- Android Version
- 7.0
- Installs
- 100,000,000+
- Developer
- Banco Inter SA
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
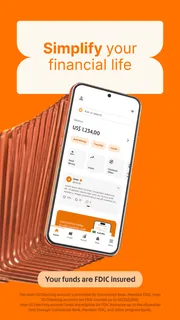
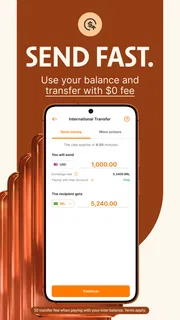
Our Review
 Analysis byUnlimiteds
When money is shared across a household, the tricky part is often not making a transfer; it is keeping track of who paid, what the payment was for, and which account should be used next time. I see Inter Banking as a useful option for people who want everyday banking and certain money-moving tasks together on a phone, but it works best when each person keeps clear boundaries around their own account. It is not a substitute for household budgeting or a shared account agreement.
Useful when household money has several moving parts
In a familiar shared-use scenario, one person pays a household bill, another needs to send their share, and someone else is arranging a purchase or a gift. A banking app can reduce the back-and-forth by putting account activity and money transfers in the same place. Inter also brings gift cards and international transfers into that broader mix, which may be handy when a household’s spending is not limited to local bills.
That convenience is most meaningful when the people involved already know how they want to divide expenses. The app can help with the banking task, but it cannot decide whether a grocery run is split evenly or whether one person owes the other for a particular bill. I would agree on the amount and purpose first, then use the relevant transfer option rather than treating a bank transaction as a complete record of the household’s arrangement.
A practical example is a shared dinner purchase: one person pays, then sends a clear request or message outside the banking process so the others know what their portion covers. Once everyone agrees, the transfer can be made through the app. Keeping that explanation separate from the transaction helps avoid the common confusion of seeing money move without remembering why.
One phone is not one shared account
For a couple or family using the same physical phone at different times, I would treat the device as a convenience, not as permission to use each other’s banking profile. A banking account is personal, and the person signing in should be the account holder. If another household member needs banking access, the sensible arrangement is for that person to use their own account and device access rather than relying on someone else’s session.
This matters even if the phone is routinely passed around for other tasks. A banking screen can expose private financial information, and an unlocked device may also leave an account available to the next person. I would sign out or otherwise secure access when finished, avoid saving access details where other users can reach them, and never share a passcode simply to make household coordination easier.
There is a trade-off here: a shared device may be convenient for looking something up together, but it blurs account boundaries unless everyone is careful. If several people need frequent independent access, separate phones or separate user sessions are a better fit than taking turns inside one person’s account. I would not choose this setup if household members expect the app itself to manage individual permissions or divide spending between them.
Set up around the account holder’s needs
Inter Banking is a finance app from Banco Inter SA. It is free, and its published minimum operating-system requirement is Android 7.0. Before making it the household’s everyday banking choice, I would check that the phone’s software meets that requirement and that the account holder can reliably access the device. A household member who uses an older or shared phone should settle those basics before depending on the app for a time-sensitive payment.
The setup decision should also be personal rather than communal. The account holder should manage their own sign-in and decide what financial information they are comfortable viewing on the device. If a partner or relative is helping with a one-off task, I would keep the account holder present and in control instead of handing over credentials. That approach may take an extra moment, but it avoids turning informal help into ongoing access.
Version 26.19 is the current version noted for the app. I would keep the app updated through the app store and make sure the phone itself is maintained, particularly if it is used for more than one person’s daily activities. An update does not remove the need for sensible account habits, but using a supported, current setup is a better starting point for financial tasks than relying on an old installation that nobody checks.
The app is rated for Everyone, but that label should not be read as a recommendation for children to manage banking independently. It describes the content rating, not a family account arrangement or a substitute for adult oversight. For younger household members, I would keep financial decisions and account access with a responsible adult, and explain money-sharing separately from giving a child access to an adult’s banking profile.
Coordination works best with a routine
For recurring household costs, I would use a simple routine: agree who pays, agree how the others will contribute, then make the transfer and note what it covers in a shared household record. The app can handle the banking part, while a note, message thread, or budgeting method can preserve the context. This division of labor is more reliable than expecting a bank transaction alone to explain a month of groceries, utilities, and one-off purchases.
Gift cards can also fit a household workflow, such as when someone is buying a present or setting aside a specific purchase. I would still check that the recipient and intended use are agreed before buying one. A gift card is less flexible than cash in a bank account, so it is a poor choice when the household is trying to reimburse an uncertain amount or settle a bill that may change.
International transfers are useful to have alongside ordinary banking if a household regularly needs to move money across borders. The important practical step is to confirm the recipient and transfer details carefully before proceeding. For an occasional transfer, I would compare the available terms and the recipient’s needs with other services before deciding; convenience inside a familiar banking app is valuable, but it should not be the only factor in a cross-border decision.
When coordination is occasional, a single banking app may be enough. When several people need to track shared spending in detail, a dedicated household budget or expense-sharing tool can be a better companion because its job is to record contributions and categories. I would not expect Inter to replace that layer simply because it brings banking and transfers together.
Where it sits among banking alternatives
Compared with a traditional bank’s mobile app, Inter’s appeal is the combination of banking with gift cards and international money transfers. That breadth can be convenient for someone who prefers fewer separate apps. The alternative may still be better if a person already has a bank they trust, relies on its established routines, or wants to keep household finances separate from a new account relationship.
Compared with a standalone transfer service, a banking app can make sense when the transfer is one part of a broader financial routine. A dedicated service may be preferable when the user’s priority is a particular transfer workflow or when they want to compare options specifically for an international payment. I would check the details for the transaction at hand rather than assume that one app is automatically best for every kind of transfer.
Inter has an average rating of 4.4 from around 5.1 million ratings, and it has passed 100 million installs. Those figures suggest that it is widely used, but they do not tell me whether its way of handling an individual household’s needs will feel right. I would treat broad popularity as reassurance that the app is established, not as a reason to overlook account boundaries or compare transfer choices.
Trust, age, and the right household fit
The app is intended for everyone by its content rating, but financial responsibility depends on the account holder and the household’s circumstances. I would be comfortable recommending it to an adult who wants a digital banking option and can keep their account private. I would be more cautious if the phone is routinely unlocked and passed among relatives, or if the household expects one person to supervise everyone’s transactions through a single profile.
People who need several family members to have formal, separate access should look for an arrangement designed for that need rather than improvising with one person’s login. Likewise, anyone who wants detailed shared budgets, automatic household expense allocation, or a complete record of who owes whom may prefer a specialist tool alongside their bank. Those are different jobs from moving money, and treating them as the same can lead to missed context.
There is also a trust question around convenience: putting more tasks in one app can make everyday banking feel simpler, but it concentrates attention on one account and one device. I would use a secure personal device where possible, review the recipient and amount before sending money, and keep a separate household record when the reason for a transfer matters later. These habits are useful whether the payment is local, tied to a gift card, or international.
Released on May 4, 2016, Inter Banking has been available long enough to build a substantial user base, and the current version is 26.19. I see it as a practical choice for an adult who wants banking and several adjacent money tasks in one place, particularly if the app’s approach suits their needs. Its free price removes an upfront purchase decision, but I would still evaluate the actual account and transfer terms before making it the center of a household’s finances.
My household verdict
I would recommend Inter Banking to someone managing their own money who also needs convenient transfers, gift cards, or international money movement. It can make sense in a household when everyone understands that each person’s account remains their own and shared expenses are agreed and documented separately. The strongest benefit is having several useful financial tasks close together, not having the app organize family finances for you.
I would skip it as a household-management solution if the main goal is shared visibility, child supervision, or automatic expense splitting. A separate budgeting method, a dedicated expense-sharing app, or a different banking arrangement may serve those needs better. For an adult comfortable handling their own account on a personal device, though, Inter Banking is a credible all-around option; I would use it with clear boundaries and a deliberate routine for shared costs rather than assuming convenience alone will keep everyone coordinated.
Pros and Cons
Pros
- Check account balances and recent transactions from your phone.
- Transfer money between eligible accounts without visiting a branch.
- Pay bills through the app when supported by your bank.
- Review transaction details to help monitor account activity.
- Access banking services outside regular branch hours.
Cons
- Some features may require enrollment with a participating bank.
- Transfer limits can restrict how much you send at once.
- New payees may require extra verification before transfers.
- Service availability can vary by bank and location.
- App access depends on a stable internet connection.
Advertisements
Android permissions
Inter Banking & Money Transfer asks for these permissions on Android. You can turn each one off in Settings at any time.
- Identity
- find accounts on the device
- Contacts
- find accounts on the device, read your contacts
- Location
- approximate location (network-based), precise location (GPS and network-based)
- Phone
- directly call phone numbers, reroute outgoing calls, read call log, read phone status and identity
- Photos/Media/Files
- read the contents of your USB storage, modify or delete the contents of your USB storage
- Storage
- read the contents of your USB storage, modify or delete the contents of your USB storage
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Inter Banking & Money TransferBanco Inter SA | 4.4 | 100,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What can I do with Inter Banking & Money Transfer?
Inter Banking & Money Transfer is intended to help users manage everyday banking tasks and send money through a mobile device. Available features may include checking account information, reviewing transactions, making transfers, and managing payment details. The exact services depend on the app version, your location, and the financial institution or provider connected to your account, so check the app listing and its official terms before relying on a particular feature.
Is Inter Banking & Money Transfer safe to use for banking and transfers?
The app may use security measures such as sign-in verification and protected connections, but no financial app can guarantee that every account or transaction is risk-free. Download it only from an official app store, confirm that the publisher is legitimate, and avoid signing in through links in unsolicited messages. Use a strong, unique password, enable any additional verification offered, and contact your bank directly if you notice unfamiliar activity.
Are there fees or limits when sending money with Inter Banking & Money Transfer?
Fees, transfer limits, delivery times, and supported payment methods can vary based on the provider, destination, currency, and type of transfer. Some transactions may be free while others could incur charges or exchange-rate costs. Review the amount, recipient details, estimated arrival time, and any displayed fee before confirming a payment. For current limits or charges, consult the app’s official information or your financial institution.
What information do I need to get started with Inter Banking & Money Transfer?
You may need a compatible device, an internet connection, and account details for the bank or payment service you want to use. Registration or identity checks may also be required, depending on the features and local rules. Only enter personal or financial information in the verified app, and read its privacy policy to understand how data is handled. Requirements can differ by country and provider.
What should I do if a transfer is delayed, fails, or goes to the wrong recipient?
First, check the transaction status and confirmation details in the app, then allow for the stated processing time, since some transfers are not immediate. If a payment fails or appears delayed, avoid sending it again until you confirm whether the original transaction completed. For an incorrect recipient or an unfamiliar charge, contact the app’s official support and your bank promptly; completed transfers may not be reversible.
Advertisements

Download Inter Banking & Money Transfer
About This Listing
- Last Checked
- Nov 15, 2026
- Version Reviewed
- 26.19
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.