


Self - Credit Builder & Cards
Advertisements
App Specs
- Version
- 10.0.0
- Updated
- Nov 7, 2026
- Android Version
- 7.0
- Installs
- 1,000,000+
- Developer
- Self Financial, Inc.
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
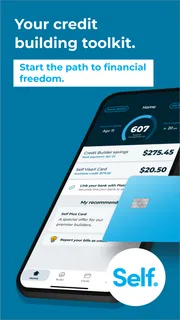
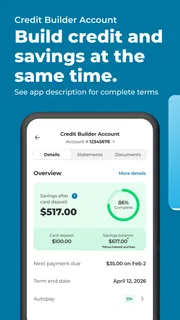
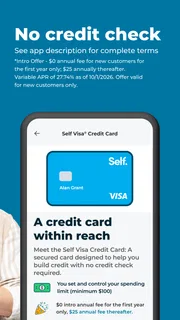
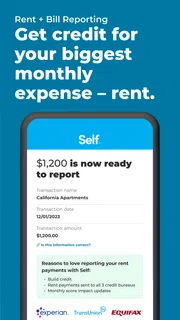
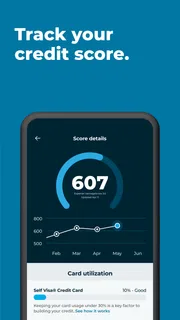
Our Review
 Analysis byUnlimiteds
I would be most comfortable using Self - Credit Builder as a personal financial tool, even if the phone it’s installed on is shared. Credit-building is tied to an individual’s finances, so the useful question for a household is not whether everyone can explore one account, but whether the person managing it can keep their own information and decisions separate. I’d treat the app as something one account holder uses privately, then discuss general plans or progress with a partner only if they choose to.
A shared phone still needs personal account boundaries
On a family tablet or a phone that gets passed around, I would avoid leaving a financial session open for the next person. That is sensible for any money app, but especially here: choosing a plan and keeping up with payments are personal responsibilities, not household settings to adjust casually. I’d sign out when finished if that option is available, use the device’s usual screen lock, and avoid letting someone else make a payment or change a choice on my behalf.
I’d also keep expectations clear before starting. A relative can remind you about a payment date or help you read an unfamiliar term, but they should not assume they can manage your account or see its details. Self is not a substitute for a shared household budget, and a shared device does not make credit histories shared. That distinction matters for couples, roommates, and parents helping an adult child get organized.
Planning payments without turning it into a family project
The most useful household role is often simple coordination. If a monthly payment is part of your plan, fit it into your own budget first; then, if household costs are split, agree on who covers which shared bills so the credit-builder payment does not get lost among them. I would not rely on another person’s memory as the payment system. A calendar reminder and a quick check of the app can make the routine easier to maintain without handing over account control.
This is also where the product’s structure deserves a careful look. The money is not immediately available while you make payments, so it should not be treated as emergency savings or cash for a bill that might come due next week. If you and a partner are deciding whether the monthly commitment fits, discuss the amount and timing in ordinary budget terms, but make the final choice based on the account holder’s own income and obligations.
Who should be involved, and who should not
Self Financial, Inc. develops this finance app, which is rated for Everyone. That age label is not a reason to treat it as a child’s money tool: credit-building decisions are best approached by the person responsible for the account and payments. If you are helping a younger family member understand credit, I’d start with a conversation about borrowing, payment habits, and credit reports rather than sharing login details or making choices for them.
The app is a stronger fit for someone who wants a structured way to establish or rebuild credit and can keep up with a planned payment. It is a weaker fit for someone who needs immediate access to every dollar, has an unstable budget, or is looking for a quick score jump. I’d also compare the total commitment with other ways of building credit before enrolling; the best option is the one whose cost, timing, and responsibilities genuinely fit your circumstances.
As a finance app, Self has an average rating of 4.5 from around 91,000 ratings and more than a million installs. Those figures suggest many people have tried it, but they can’t tell you whether its payment structure is right for your household. The app is free to download, while the credit-building arrangement itself involves fees, so I would separate the app’s download cost from the cost of using its financial product and read the terms carefully before committing.
One practical way to make that decision is to write down the amount you can set aside each month, the date it would leave your budget, and what you would do if an unexpected expense came up. Then compare that plan with the account terms in the app. If the numbers only work when another household member regularly covers your share, I’d pause rather than assume the arrangement will stay comfortable.
Getting Started with Self - Credit Builder
When I first downloaded Self - Credit Builder, I was a bit skeptical. I mean, can an app really help me with something as complex and crucial as credit? But, right from the get-go, I was greeted with a user-friendly interface that made the whole process seem less daunting. The app offers a clear step-by-step guide to help you set up your credit builder account. It’s as simple as creating an account, picking your plan, and voila, you’re on your way to better credit!
How It Works
The magic behind this app is its unique approach to building credit. Essentially, you’re taking out a small loan that you can’t touch immediately, which gets reported to the credit bureaus. Instead, you make monthly payments towards it, and once it’s paid off, you get access to the money. It’s like a savings account on steroids, where you’re not just saving but also building your credit history.
What I love about this is the transparency. You know exactly how much you’re paying, how long it will take, and how it impacts your credit score. Plus, you can track your progress within the app, which is incredibly satisfying. It’s like having a financial cheerleader cheering you on every time you make a payment!
Features That Stand Out
One feature that really caught my eye was the educational resources. Self - Credit Builder doesn’t just help you build credit; it educates you along the way. From understanding credit reports to learning about the factors that affect your score, it’s like a mini financial literacy course. And let’s be honest, who doesn’t need a little extra help with understanding financial jargon?
Another thing worth mentioning is the customer service. I had a few questions initially and decided to test the waters by reaching out. I was pleasantly surprised by how responsive and helpful the support team was. It’s reassuring to know that there’s real people ready to assist you when needed.
Is Self - Credit Builder Worth It?
In my honest opinion, if you’re someone who’s serious about taking control of your financial future, Self - Credit Builder is definitely worth a shot. It’s straightforward, effective, and comes with the added bonus of educating you in the process. Sure, there are fees involved, but think of it as an investment in your financial health. The app makes the whole process of credit building feel less like a chore and more like a journey you’re excited to embark on.
So, if you’re ready to take the plunge and start your credit building adventure, Self - Credit Builder might just be the partner you’ve been looking for. Give it a try, and who knows, you might just see your credit score rising sooner than you think!
Making the payment routine realistic
A useful habit is to review the plan at the same time you check your monthly bills, rather than treating credit progress as something to inspect only when a score changes. I’d look at the next payment, the remaining commitment, and whether the budget still has room for essentials and unexpected costs. That turns the app into a planning aid instead of a reason to stretch a tight month.
For example, imagine a person starting a new job who wants to establish a record of on-time payments. They could use the app to follow a predictable monthly commitment while keeping rent, utilities, and groceries ahead of optional spending. If their first paycheck is delayed or an urgent expense appears, the right response is to reassess the budget and contact the provider for clarification about available choices, rather than assuming the app can make the payment affordable.
How it differs from familiar credit-building routes
Compared with a secured credit card, this approach does not ask you to manage everyday purchases on a revolving card balance. That can be appealing if you want a more defined payment routine and prefer not to add another card to your wallet. A secured card may be more useful, however, for someone who can pay the statement in full and wants to practice using credit for ordinary purchases. Neither route is automatically better; they build different habits and carry different commitments.
It also differs from simply saving money in a regular savings account. With ordinary savings, the balance is generally available according to the account’s terms, while Self’s credit-builder structure keeps the funds unavailable until the arrangement is completed. The trade-off is central, not a small detail: you are accepting restricted access in exchange for a structured credit-building process. If liquidity is your priority, keeping savings accessible is likely more important than choosing this method.
What to check before choosing a plan
Before enrolling, I’d compare the full payment schedule and total cost, not just the monthly amount. Check how long the commitment lasts, what happens if you miss or make a late payment, and when the funds become accessible under the terms you are offered. These details determine whether the arrangement suits your real cash flow. The app can make the steps easier to follow, but it cannot remove the consequences of a commitment that is too tight.
I’d also treat credit progress as gradual and dependent on a broader financial picture. Regular payments can contribute to credit history, but no single app can promise a particular score outcome; credit files and scoring decisions involve more than one factor. If you already have a card or loan that you manage well, compare whether adding another obligation would solve a genuine gap or simply complicate your budget.
Choosing the right person and moment
This is most compelling for someone who has little credit history or is deliberately rebuilding, understands that the money is not available immediately, and can make the planned payments without relying on optimistic assumptions. It is not a good fit for someone seeking a fast cash advance, an emergency fund, or a guaranteed score increase. If your priority is learning the basics, the educational material may help, but reading it does not replace checking your own reports or asking a qualified professional about a complicated financial situation.
The app is free to download and its current version is 6.23.0, with Android support beginning at version 5.0. That makes it accessible on a range of Android devices, though I would still make sure the phone is secure and that the account holder can use it reliably for a recurring financial task. A finance tool is only helpful when its routine fits both the person’s budget and the way they actually manage money.
A measured household verdict
My overall view is that Self can give an individual a clear, structured route into credit-building, but it should stay an individual commitment even when family members share a device or household budget. The strongest practical benefit is the combination of scheduled repayment and progress tracking; the main compromise is that the money is not available during the payment period and fees matter. I would use it when the plan fits comfortably, keep account access personal, and make sure everyone involved understands that support and reminders are not the same as shared ownership.
If accessible cash, flexible borrowing, or a rapid result is what you need, I would look elsewhere. If you want a deliberate payment routine and can afford to leave the funds untouched until the end, it is worth considering after reading the terms closely. That distinction is what makes this app useful for some people and a poor match for others.
Pros and Cons
Pros
- Improves credit score effectively
- Easy to set up and use
- Affordable monthly payments
- No hard credit check required
- Builds savings while building credit
Cons
- Monthly fee can be a drawback
- No immediate credit score boost
- Limited to credit-building purposes
- Requires commitment to a payment plan
- Not suitable for those with severe credit issues
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Self - Credit Builder & CardsSelf Financial, Inc. | 4.7 | 1,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Self - Credit Builder and how does it work?
Self - Credit Builder is an innovative financial app designed to help users improve their credit scores through a Credit Builder Account. Users make monthly payments, which are reported to major credit bureaus, helping to build a positive payment history. The funds are held in a secured account until the end of the term, at which point they become available to the user. This approach not only aids in credit building but also encourages savings.
How much does it cost to use the Self - Credit Builder app?
The cost of using the Self - Credit Builder app varies depending on the specific plan you choose. There is a one-time non-refundable administrative fee to open your Credit Builder Account, and monthly payments range depending on the amount you select. It's important to review the terms carefully to choose a plan that fits your budget and financial goals.
Is Self - Credit Builder safe to use for my financial transactions?
Yes, Self - Credit Builder is safe for financial transactions. The app employs bank-level encryption and security protocols to protect your personal and financial information. Funds in your Credit Builder Account are FDIC-insured, providing an additional layer of security. The app's commitment to security has made it a trusted choice for users looking to improve their credit scores.
Can Self - Credit Builder really help improve my credit score?
Yes, Self - Credit Builder can help improve your credit score by establishing a positive payment history, which is a major factor in credit scoring. By making regular, on-time payments to your Credit Builder Account, these are reported to all three major credit bureaus. Consistent, timely payments can positively impact your credit score over time, improving your financial standing.
Who is eligible to use Self - Credit Builder?
To use Self - Credit Builder, you must be a U.S. citizen or permanent resident. Additionally, you need a valid Social Security Number, be at least 18 years old, and have a bank account or debit card to make your monthly payments. Meeting these eligibility requirements allows you to open a Credit Builder Account and start your journey toward better credit.
Advertisements

Download Self - Credit Builder & Cards
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 10.0.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.