


Schwab Mobile
Advertisements
App Specs
- Version
- Varies with device
- Updated
- Nov 7, 2026
- Android Version
- Varies with device
- Installs
- 5,000,000+
- Developer
- The Charles Schwab Corporation
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
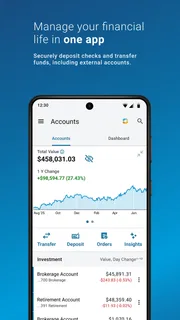
I found Schwab Mobile most useful when I treated it as a personal control panel for investing and banking rather than as a simple stock-watching tool. It brings research, account activity, trading, and everyday money tasks into one finance app, which can save time when I am moving between cash management and investment decisions. The developer is The Charles Schwab Corporation, and the app is free to download for an Everyone audience.
That combination makes it appealing for an individual who already uses Schwab services and wants one place to check what is happening. It is less compelling for someone who only wants a basic budget tracker, a very simple savings app, or a completely beginner-focused investing experience. My overall impression is practical: the app can cover a lot, but its usefulness depends heavily on how comfortable you are with financial terminology and how carefully you manage access on a shared phone.
How Schwab Mobile fits into a shared household
A realistic household example is a couple coordinating bills while keeping their investment decisions separate. One person might open the app to check available cash before paying a bill, while the other wants to review a portfolio or research a possible trade. Having banking and investing tools together reduces the need to switch between unrelated apps, but it does not turn separate financial responsibilities into one shared workspace.
That distinction matters. I would not hand a shared phone to another household member and assume that the app is suitable for casual browsing. Finance apps deal with information that can reveal balances, transactions, holdings, and trading activity. Even when two people trust each other, a device can be picked up at the wrong moment, left unlocked, or used by a child who does not understand the consequences of tapping through a financial screen.
For shared-device use, I would keep the app tied to the person whose accounts are connected and make sure that person controls when it is opened. If a household needs coordination, I would discuss the task outside the app first: which account needs attention, whether the goal is checking cash or researching an investment, and who is responsible for the final action. This simple separation helps prevent a quick balance check from turning into an accidental transaction or an unclear decision.
The strongest household habit is treating Schwab Mobile as an account-access tool, not as a family noticeboard. It can support coordination, but the app should not be expected to explain who is allowed to see what or who should approve a financial action. Those boundaries need to be agreed on by the people using the device.
What the first setup feels like
When I approach an app that combines investing and banking, I expect the opening experience to feel denser than a single-purpose wallet. Schwab Mobile has a broad job: it is designed for research, account review, trading, and banking in the same place. That breadth is useful, but it also means a new user should take time to identify the areas they actually need instead of tapping through every available section.
I would begin by deciding whether the app is mainly for monitoring, everyday banking, research, or placing trades. That choice changes how much attention I give to each screen. Someone checking a retirement account once a month does not need the same routine as an active investor who watches markets and reviews orders more often. Starting with a narrow purpose makes the interface feel less overwhelming.
On a household phone, I would also establish a clear access routine before signing in. The account holder should be the person who enters credentials and reviews sensitive screens. If another adult needs information, it is safer to share the relevant result verbally or through an agreed household process than to leave the account open for someone else to explore. I would avoid saving access details in a place where children or visitors can reach them.
Another useful setup decision is separating observation from action. I like to review balances, holdings, and research first, then pause before making a trade or moving money. That extra pause is especially valuable on a small screen, where a quick tap can feel deceptively simple. The app brings powerful actions close to information, so a deliberate routine is more important than trying to complete everything as quickly as possible.
Keeping banking and investing mentally separate
One of the app’s central conveniences is also one of its main sources of complexity. Seeing banking and investment activity in one application can make a household feel organized, but it can also blur the difference between spendable cash and money assigned to a longer-term plan. I would not treat every visible balance as interchangeable.
For example, before paying a household bill, I would verify which account the money belongs to and whether it is intended for spending. Before researching a security, I would make sure I am looking at the right account and understand whether the available cash figure reflects the purpose I have in mind. This is not a criticism of the app alone; it is a consequence of putting several financial jobs under one login.
That combined view is valuable for people who actively manage both sides of their finances. It can reduce the mental cost of switching tools and make it easier to review a broader picture. However, a user who wants strong separation between daily spending and investing may prefer dedicated apps or a simpler banking interface. Schwab Mobile rewards organization; it does not replace it.
Research and trading without rushing
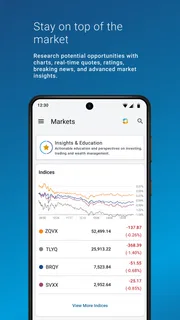
The research side is where I would expect the app to appeal most to users who want more than a basic portfolio snapshot. Having research and trading available together can shorten the path from a question to a decision. That is convenient, but it also creates a temptation to act before the question has been properly answered.
My preferred workflow is to use the research area as a preparation step, not as a signal generator. I would first write down what I am trying to learn, review the relevant information, and then decide whether any action is justified. On a phone, the convenience of moving from research to a trade can make an impulsive decision feel like an efficient one. Those are not the same thing.
This is also where Schwab Mobile may be a poor fit for a complete beginner who expects the app to teach investing from the ground up. A broad financial platform can expose users to useful tools, but exposure is not the same as guidance. If you are still learning basic concepts such as risk, diversification, order types, or the difference between account balances, I would use educational material separately and treat the app as the place to carry out informed tasks.
For experienced users, the advantage is convenience. A quick review during a commute or between household errands may be enough to check a position or investigate a market question. The trade-off is that a phone encourages short sessions, while some decisions deserve slower reading and a larger screen. I would use the mobile app for monitoring and straightforward actions, then move to a more spacious environment when the decision requires careful comparison.
Coordination between adults
Schwab Mobile can support a household conversation, but it should not be mistaken for a shared planning system. Two adults might agree that one person handles bill-related checks while the other reviews investments. That division can work well if each person knows what the other is doing and if the account boundaries are respected.
I would create a small verbal handoff routine. Before opening the app, say whether the goal is to check cash, review a holding, investigate research, or complete a banking task. Afterward, report only the result needed for the household decision. This keeps coordination focused and avoids turning every financial conversation into a screen-sharing session.
A separate point is timing. If one person is using the app for a time-sensitive task, the other should avoid interrupting or taking the phone mid-session. Financial actions are not ideal for casual multitasking, especially when a shared device contains several accounts or notifications. Agreeing on a quiet moment is a surprisingly effective way to reduce mistakes.
I would also keep household budgeting discussions separate from investment performance discussions. A strong month in a portfolio does not automatically mean more money is available for bills, and a short-term market decline does not necessarily change a long-term plan. Because the app places these subjects near each other, the people using it need to supply the context.
Age, trust, and a child using the phone
The Everyone content rating describes the general audience classification, not a recommendation that children should operate financial accounts. In my view, the important question is not whether a child can understand the words on the screen, but whether they understand the consequences of viewing or changing financial information. Most children do not need direct access to a banking and investing app.
If a child borrows the household phone, I would close the session first and keep the device locked when it is unattended. I would not rely on curiosity staying harmless. A child may tap a button simply to see what it does, while an adult understands that a financial action requires verification and responsibility.
Teenagers learning about money can still benefit from supervised conversations around screenshots, printed examples, or a separate educational exercise. I would explain the difference between observing an account and acting on it, and I would avoid using a live account as a teaching playground. The app can be part of a financial education discussion, but the account holder should remain in control.
Trust between adults deserves the same clarity. Sharing a device does not automatically mean sharing every account. I would decide in advance whether another person may see balances, read transaction history, or participate in investment decisions. If those permissions are unclear, the safest approach is to keep the session private and discuss the information needed afterward.
How it compares with simpler alternatives
Compared with a basic banking app, Schwab Mobile offers a wider financial scope. That is its main reason to exist for many users: banking activity, investment research, portfolio review, and trading can live in one place. If you already manage several Schwab-related tasks, this consolidation is more useful than maintaining separate tools.
Compared with a budgeting app, however, the emphasis is different. A budgeting-first product is usually better when your main goal is categorizing spending, setting household limits, or understanding recurring expenses. I would choose that kind of tool for day-to-day budget visibility and use Schwab Mobile for account access, investing, and related research.
Compared with a minimalist investing app, Schwab Mobile may feel more substantial. That can be a benefit for someone who wants room to grow into broader financial tasks, but it may feel like unnecessary weight for a person who only wants to make occasional, simple investments. The right choice depends on whether you value a fuller financial workspace or a reduced number of decisions on screen.
There is also a desktop-versus-mobile trade-off. A phone is excellent for quick checks and convenient access while away from home. A larger screen is often better for comparing information, reading carefully, and reviewing a complicated plan. I see the mobile app as a companion for active account management, not as a reason to abandon every other way of thinking through financial decisions.
Who should use it and who should skip it
I would recommend Schwab Mobile to an account holder who wants investing and banking functions close together, already understands the basics of personal finance, and values being able to review financial activity away from a computer. It is particularly practical for someone who alternates between checking cash and reviewing investments during the same day.
It is also suitable for a disciplined user who can resist impulsive actions. The app’s convenience is most helpful when you have a repeatable routine: identify the account, confirm the purpose, review the information, and only then decide whether to act. That process turns a broad tool into something manageable.
I would be more cautious recommending it to someone who wants a very simple first investing experience, a dedicated household budget, or a child-friendly money app. I would also hesitate for a person who tends to make decisions from quick market movements or who dislikes having banking and investing functions in the same environment. A simpler alternative may reduce friction and reduce temptation.
The public response is mixed, with an average rating of 3.1 from around 29 thousand ratings and roughly 13 thousand written reviews. I read that as a reason to set realistic expectations rather than as an automatic rejection. The app has reached more than 5 million installs, so it clearly serves a substantial audience, but popularity does not guarantee that its broad design will suit every household or investing style.
My household verdict
Schwab Mobile is a capable finance app for people who want a single mobile destination for banking, research, investing, and trading. I like the convenience of bringing those activities together, and I can see why an individual user would prefer it to switching between several financial tools. The free price also makes trying it straightforward for someone who already has a reason to use Schwab services.
My reservations are mainly about boundaries and behavior. A shared phone requires deliberate privacy habits, and a shared household requires clear agreement about who may view or act on an account. The Everyone age classification should not be confused with permission for children to use live financial accounts. The app can support adult coordination, but it does not replace a household’s own rules.
I would keep Schwab Mobile on my phone for quick reviews, planned account tasks, and research that I have time to consider properly. I would not use a short mobile session as a substitute for careful financial planning, and I would not leave it open on a device that other people casually use. For an organized adult managing Schwab finances, it is a useful all-in-one companion; for a beginner seeking simplicity or a family seeking shared controls, a different tool may be the better choice.
Pros and Cons
Pros
- Real-time quotes and market data support informed trading decisions.
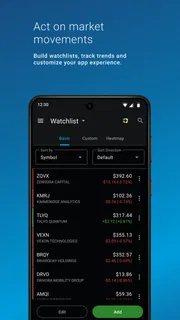
- Customizable watchlists make it easy to monitor favorite securities.
- Mobile check deposit simplifies funding and managing your brokerage account.
- Strong security features help protect account access and sensitive information.
- Access to Charles Schwab research and analyst insights within the app.
Cons
- Some advanced trading tools are easier to use on the desktop platform.
- The interface can feel dense and overwhelming for first-time investors.
- Options trading may require extra permissions and approval before use.
- Market data and features may vary depending on account type and holdings.
- Customer support access through the app may be less convenient during busy periods.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Schwab MobileThe Charles Schwab Corporation | 3.1 | 5,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Schwab Mobile and what can I do with it?
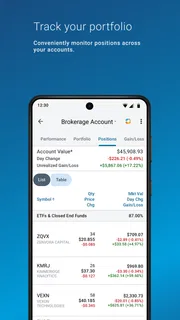
Schwab Mobile is Charles Schwab’s official mobile app for managing brokerage and related financial accounts from an Android or iOS device. After signing in, you can review balances, monitor positions, research securities, place trades, transfer money, deposit eligible checks, view statements, and contact support. The exact tools available may depend on your account type, permissions, location, and Schwab’s current service availability.
Is Schwab Mobile safe to use for investing and account management?
Schwab Mobile includes security features designed to protect account access and financial information, such as encrypted connections, secure sign-in options, device authentication, and optional two-step verification where supported. However, no app can eliminate every risk. Install it only from the official Google Play Store or Apple App Store, keep your operating system updated, avoid public Wi-Fi for sensitive actions, and never share your login or verification codes.
Can I buy and sell stocks, ETFs, options, or other investments through the app?
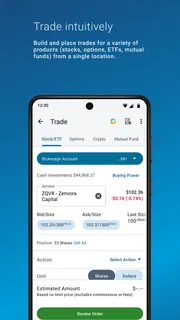
The app allows eligible Schwab customers to place and manage many types of investment orders directly from a mobile device. Depending on your account approval and trading permissions, this may include stocks, ETFs, mutual funds, options, and other available products. Before submitting an order, review the symbol, quantity, order type, duration, estimated costs, and any warnings carefully. Investing involves risk, and market prices can change quickly.
Does Schwab Mobile charge fees for using the app or placing trades?
Downloading and using Schwab Mobile generally does not require a separate app subscription fee. Nevertheless, the app does not make investing completely cost-free in every situation. Certain transactions, products, account services, or special orders may involve commissions, regulatory fees, fund expenses, spreads, or other charges. Pricing can change, so check Schwab’s current fee schedule and the order confirmation screen before completing a transaction.
What should I do if Schwab Mobile will not open, crashes, or I cannot log in?
If Schwab Mobile is not working properly, first check your internet connection and confirm that you installed the latest version from the official app store. Restarting the app or device may resolve temporary problems. If login fails, verify your credentials and use Schwab’s official recovery options rather than repeatedly guessing. For outages, locked accounts, device-security concerns, or transaction questions, contact Charles Schwab through its official website or customer-support channels.
Advertisements

Download Schwab Mobile
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- Varies with device
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.