


Payactiv
Advertisements
App Specs
- Version
- 2.2.8
- Updated
- Nov 7, 2026
- Android Version
- 10
- Installs
- 1,000,000+
- Developer
- On-demand pay and beyond
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
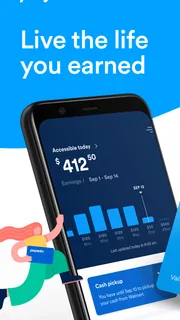
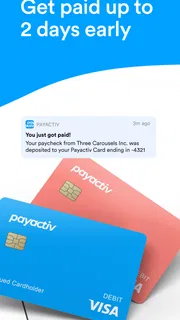
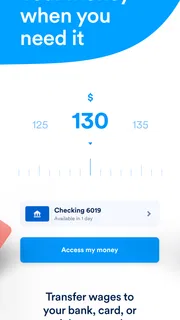
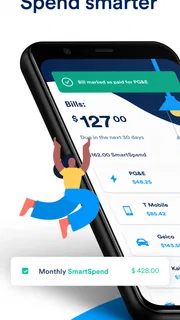
Our Review
 Analysis byUnlimiteds
When money gets tight a few days before payday, I think the first question is not whether an app promises quick access to wages, but whether that access fits the way you are paid and the way you manage bills. Payactiv is a finance app built around earned-wage access, with tools aimed at making day-to-day money decisions easier. I would consider it when a short-term timing gap is the problem—not as a substitute for a budget, an emergency fund, or a lasting increase in income.
Start with the fit, not the promise
Before relying on early pay, I’d check whether your employer’s payroll setup works with the service and what the app shows as available to access. That practical detail matters more than the general idea: earned wages are not necessarily the same as an unlimited cash advance, and the amount you can use depends on your pay and work situation. If your employer is not supported, the central reason to choose this app may not apply to you.
I’d also decide in advance what kind of expense would justify using wages early. A utility bill due before payday or an urgent trip to work is different from routinely drawing money forward for ordinary spending. In the first case, earlier access may help smooth a timing mismatch. In the second, it can leave less pay for the next set of bills. The useful question is whether it solves a one-off timing problem without making the next payday harder.
That is why I would treat the app as a cash-flow tool, not as extra income. Before confirming a transfer, I’d compare the amount with upcoming essentials and leave enough room for them. If you are already struggling to cover recurring costs, a conversation with a trusted financial counselor or a review of bills and due dates may be more useful than repeatedly moving pay forward.
Where Payactiv can make a difference
For someone whose work and payroll are compatible, the main draw is having another option between a bill coming due and the usual payday. The app’s combination of early wage access, bill payment, budgeting tools, and savings plans gives it a broader role than a simple balance screen. I’d find that combination most useful if I prefer to check cash flow and organize a payment in one place rather than switch among several separate tools.
A realistic example: imagine your car needs an unexpected repair late in the pay cycle, and you need the car to get to work. I would first check the amount available and the payment timing, then compare that with rent, groceries, and other costs that will fall due after payday. If using a portion of already-earned wages keeps the repair from turning into a more expensive problem, the option could be practical. I would still avoid taking more than the immediate need, because money accessed now is money that will not be waiting in the next pay cycle.
The app may also suit people who want a prompt to look at their financial habits, rather than only a way to cover an urgent cost. Budgeting and savings tools can help make a pattern visible: for example, whether several small expenses are repeatedly creating a shortfall near payday. My tip would be to use those tools before an emergency, when there is time to adjust a plan, and to review whether early access is becoming a regular part of the budget.
How it compares with other ways to bridge a gap
Compared with a credit card, earned-wage access is tied to pay you have already worked for rather than a revolving borrowing limit. That can make the idea feel more direct, but it does not make every withdrawal harmless: using money early still reduces what remains for later. A credit card may be more suitable for someone who needs a payment method for purchases and can reliably repay the balance; Payactiv is more relevant when the problem is the timing of wages and an eligible employer makes access possible.
Compared with a personal loan or a payday loan, this app’s core approach is different: it focuses on accessing earned pay, not taking out a conventional loan. That distinction is worth understanding, but I would not assume every use is cost-free or identical across users. Check the terms and any charges shown in the app before making a decision. If you need a larger amount, need money over a longer period, or cannot repay without creating another shortfall, a conversation with a nonprofit financial counselor or your creditors may be a better next step than repeatedly accessing wages early.
A basic budgeting app is another reasonable alternative, especially if your real problem is losing track of spending rather than the date money arrives. Budgeting alone cannot bring forward wages, while Payactiv’s central appeal is that access option alongside money-management tools. I would choose the simpler budgeting route if I did not need early pay; there is little value in adopting a payroll-linked service just to record expenses when a tool already fits that job.
Small decisions that make the service more useful
I would set up a simple routine rather than open the app only when something goes wrong. Check what is due before payday, identify the smallest amount that would solve the immediate issue, and then look at what will remain for the next cycle. This makes the decision concrete and helps prevent a vague “there’s money available” feeling from turning into unnecessary use.
It is also worth separating access from planning. If an early withdrawal covers a bill, note that bill in the budget as paid and account for the reduced pay later; otherwise, it is easy to count the same money twice in your mental plan. A small written list of the next few essentials can be more valuable than making a transfer quickly. I see this as one of the key trade-offs: convenience is helpful, but it can make future cash flow less visible unless you actively track it.
For a first-time user, I would explore the budgeting and savings sections before depending on them in a critical moment. That gives you a chance to understand how the app presents your finances and where you would go to manage a payment. I would also confirm the employer connection and review any transaction details at the point of use, since access and available options are shaped by your circumstances.
Who should look elsewhere
Payactiv is a weaker fit if your employer is not connected, your income does not arrive through a compatible payroll arrangement, or you want a general-purpose account that is independent of work. It may also be the wrong choice if you need stable long-term borrowing or have a recurring deficit that early access cannot fix. In those cases, moving each payday forward can conceal the underlying issue and make the next cycle tighter.
People who already manage bills comfortably and simply want to save may prefer a dedicated savings or budgeting tool. Likewise, anyone who does not want a financial app linked to an employment-based pay arrangement should compare other options before signing up. I would not install it on the assumption that every employee can use every feature; the employer connection and the terms presented to you are central to whether it is useful.
Payactiv is free to download and is rated for Everyone. It was released on June 4, 2014, and version 2.2.2 supports devices running Android 10 or later. The developer is On-demand pay and beyond. It has a 4.5 average from around 40,000 ratings, with about 8,400 written reviews, and has passed one million installs. Those figures suggest that many people have tried it, but they do not tell me whether it will fit a particular employer or budget; that is something to check for yourself.
First Impressions and Features
So, what’s the deal with Payactiv? At first glance, it’s super user-friendly, and I love an app that doesn’t make me feel like I need a finance degree to navigate. Right off the bat, you’ll notice its sleek design and intuitive layout, which makes checking your balance and managing your funds a breeze.
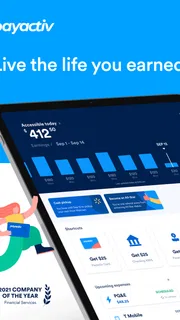
One of the standout features is the ability to access earned wages before payday. It’s like a financial safety net that you never knew you needed but suddenly can’t live without! Imagine not having to wait for payday to cover unexpected expenses. Pretty neat, right?
How Does It Work?
Now, you might be wondering, “How does this magic work?” Well, it’s pretty straightforward. The app connects with your employer’s payroll system and allows you to access a portion of your earned wages before the actual payday. Think of it as getting paid in real-time for the hours you’ve already worked. It’s a game-changer, especially if you’re living paycheck to paycheck or have bills that just can’t wait.
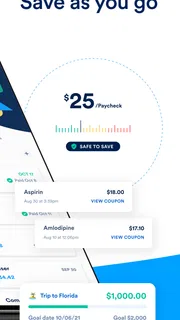
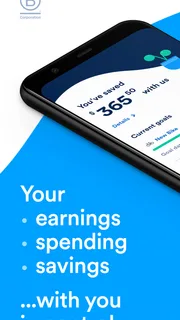
In addition to early wage access, the app offers a host of other financial tools. You can pay your bills directly from the app, which is a huge time-saver. Plus, they have a budgeting tool to help you manage your expenses and savings plans. It’s like having a mini financial assistant who doesn’t nag you about your spending habits.
Why I Think It's a Game Changer
Let me tell you why I’m pretty stoked about this app. For one, it’s about empowerment. Having control over your finances without the stress of payday loans or high-interest credit cards is liberating. Payactiv gives you the flexibility to deal with financial hiccups on your terms.
Moreover, the app’s commitment to financial wellness is evident in its educational resources. There are plenty of tips and guides on how to manage your money better, which I found to be super helpful. It’s like having a friendly guide to help you navigate the often confusing world of personal finance.
My Bottom Line
In conclusion, if you’re looking for a way to take control of your financial situation, Payactiv might just be the app for you. It’s not just about accessing your wages early; it’s about changing how you interact with your money. So why not give it a try and see how it can make a difference in your life? After all, financial wellness is just a tap away!
My recommendation is more measured: I would try it if my employer supported the service and I had an occasional gap between work already completed and payday. I would use only what solves that immediate need, check the effect on the next pay cycle, and make sure the app’s available terms suit me. If I needed help with ongoing debt, regular shortfalls, or a budget that never balances, I would look beyond early wage access first. Used with that distinction in mind, Payactiv can be a practical option; treated as extra income, it can disappoint.
Pros and Cons
Pros
- Instant access to earned wages.
- No hidden fees or interest charges.
- User-friendly interface and navigation.
- Supports financial wellness tools.
- Compatible with most payroll systems.
Cons
- Limited to participating employers.
- May encourage frequent withdrawals.
- Requires bank account for transfers.
- Customer support can be slow.
- Limited features for non-U.S. users.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 PayactivOn-demand pay and beyond | 4.4 | 1,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Payactiv and how does it work?
Payactiv is a financial wellness app that allows employees to access their earned wages before payday. By integrating with your employer's payroll system, it lets you withdraw a portion of your upcoming paycheck as needed, helping you manage unexpected expenses without resorting to costly payday loans. Users can transfer funds to their bank accounts, pay bills, or load money onto a prepaid card directly through the app.
Is Payactiv safe to use?
Yes, Payactiv takes security very seriously. The app employs bank-level encryption and security measures to protect your personal and financial information. Additionally, Payactiv is compliant with all relevant regulations, ensuring that your data privacy is safeguarded. Users can feel confident that their sensitive details are secure when using the app's features.
Are there any fees associated with using Payactiv?
While Payactiv often partners with employers to offer its services at no cost to employees, there may be minimal fees for certain transactions. For example, accessing funds through an instant transfer might incur a small fee. However, these fees are typically lower than those associated with traditional payday loans or overdraft charges. It's advisable to check with your employer or the app for specific details.
Can Payactiv help improve financial wellness?
Absolutely. Payactiv is designed to aid users in managing their finances more effectively by providing timely access to earned wages, thus reducing the need for high-interest loans. The app also offers budgeting tools, financial counseling, and savings programs to help users improve their financial literacy and stability over time. It empowers individuals to take control of their financial health.
Do all employers support Payactiv?
Not all employers offer Payactiv as a benefit, as it depends on whether the employer has partnered with the service. If your employer does not currently offer Payactiv, you might consider suggesting it as a valuable benefit. Employees can check with their HR department or directly with Payactiv to see if their workplace supports the service or to express interest in having it implemented.
Advertisements

Download Payactiv
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 2.2.8
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.