

ONE@Work (formerly Even)
Advertisements
App Specs
- Version
- 10.106.1
- Updated
- Nov 7, 2026
- Android Version
- 7.0
- Installs
- 1,000,000+
- Developer
- ONE Finance, Inc.
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
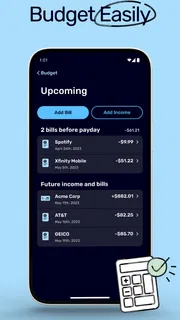
Screenshots
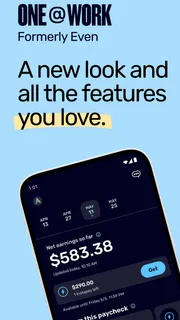
Our Review
 Analysis byUnlimiteds
When a bill lands before payday, a small timing gap can feel bigger than it is. I see ONE@Work (formerly Even) as an app built around that practical problem: helping workers think about their pay and day-to-day finances, rather than treating money management as a separate project. Its early-pay access and spending guidance may be useful, but I would approach it as a cash-flow aid, not a substitute for savings or a complete financial plan.
Where it fits in a money routine
The most useful way to judge an app like this is by the moment you need it. Imagine a household bill is due a few days before the next payday. A worker who has already earned wages may use the app to access some pay earlier, reducing the pressure to put the expense on a credit card or ask someone else for help. That can make a real difference in a tight week. It does not make the expense cheaper, though, and money taken early still has to be accounted for when the regular paycheck arrives.
That distinction is important. I would use early access for a genuine timing mismatch, such as an urgent bill, rather than treating it as extra income for routine discretionary spending. If the same shortfall keeps appearing every pay cycle, the feature may soften the immediate problem without fixing its cause. The app is most helpful when it gives someone room to make a more deliberate choice, not when it encourages them to ignore a recurring budget gap.
ONE@Work is a free finance app from ONE Finance, Inc. Its average rating is 4.8 from around 78,000 ratings, and it has more than a million installs. Those figures suggest that many people have found a reason to try it, but they do not tell me whether its tools will suit a particular employer or pay arrangement. I would treat the app’s usefulness as something to check against my own work and spending setup, rather than assuming that a popular finance app automatically fits everyone.
What makes the app useful—and what to watch
When you first open ONE@Work, you're greeted with a sleek and intuitive interface that just makes you feel like you're already in control of your finances. The app's primary goal is to make sure you’re never caught off guard by unexpected expenses, and it does this quite effectively. Right from the get-go, you can link your bank accounts, allowing the app to provide real-time insights into your financial status. How cool is that?
Features That Stand Out
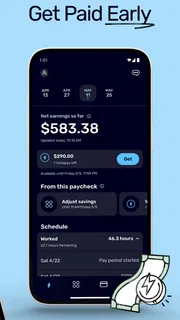
One of the standout features is the ability to access your earned wages before payday. Imagine needing some extra cash for an unexpected bill or a spontaneous adventure—this feature has got your back. It’s like having an emergency fund without actually needing to set one up.
Another feature that I found particularly helpful is the budgeting tool. It’s not just any budgeting tool; it’s designed to learn your spending habits and offer personalized advice on how to manage your money better. It’s like having a financial advisor who knows you better than your bank does!
These tools are most valuable when I give them a clear job. For instance, I might check the spending picture before deciding whether an early wage withdrawal is genuinely needed, then keep the next payday in view when planning the rest of the week. That two-step habit is more useful than opening a finance app only after a balance has become alarming. It also helps separate an unavoidable bill from a purchase that can wait.
A practical trade-off is that personalized guidance depends on the picture the app can build from the accounts and activity I connect. If I use several accounts, pay for some expenses in cash, or keep important bills elsewhere, any overview may leave out parts of the story. I would treat its advice as a prompt to review my choices, not as an instruction to follow blindly. Before connecting financial accounts, it is sensible to review the app’s current access and privacy information and decide whether that exchange feels comfortable.
Pay timing is not the same as a bigger paycheck
Early wage access can be easy to misunderstand because the money arrives sooner, which may feel like a raise in the moment. I would instead think of it as shifting when already-earned pay is available. The best test is whether using it solves a one-off timing issue while leaving enough money for the rest of the pay period. If taking money early repeatedly makes the next stretch harder, that is a sign to revisit the budget or seek a more stable solution.
For someone deciding whether to use the feature, a useful first step is to map the next two pay periods: note the fixed bills, likely essentials, and the dates they fall due. Then consider an early withdrawal only against a specific expense, rather than the vague feeling that a little extra cash would be reassuring. This simple check can reveal whether the problem is timing, an unusually large bill, or spending that regularly exceeds income. Each calls for a different response.
Compared with a conventional budgeting app, ONE@Work’s distinctive appeal is its connection between pay access and money management. A standalone budget tracker may suit someone who only wants categories, spending reports, or a plan they control themselves. A bank’s own app may be more convenient for someone who wants to see one account and avoid linking multiple services. On the other hand, a worker facing a mismatch between earned pay and bill dates may value the combination more than another chart of monthly spending. The right choice depends on the problem, not on which app has the longest feature list.
Good habits make the guidance more useful
I would start by checking whether the connected accounts reflect the bills and everyday purchases that matter most. If the app sees only part of a person’s finances, its view may be helpful but incomplete. It is also worth revisiting the picture after a change in routine—such as a new recurring bill or a different pay schedule—so that a previous spending pattern does not become an unquestioned guide to current decisions.
Another useful habit is to set a personal rule before a stressful moment arrives. For example, I might reserve early access for essential bills or unexpected needs, and avoid using it for purchases that can wait until payday. A rule like that turns a convenient option into a deliberate tool. Without one, it can be tempting to focus on the cash available today and overlook how the choice affects the remaining days before the next paycheck.
The budgeting feature may also work better as a conversation starter than as a verdict. If the app highlights an area of spending, I would compare that observation with my actual priorities and obligations. A higher cost in one category could reflect a temporary need, not a careless habit. The useful question is whether the pattern is sustainable and intentional, not whether every category can be reduced.
Who is likely to benefit
ONE@Work is most compelling for someone whose pay and bill dates do not line up neatly, who wants a clearer view of spending, and who is willing to check that view regularly. It may also help a person who is building basic money habits: looking ahead to bills, noticing patterns, and deciding whether a purchase can wait. Its Everyone content rating makes the app broadly accessible in that respect, while the financial decisions involved still call for adult judgment and care.
I would be more cautious about recommending it to someone who is already relying on advances to cover ordinary expenses every pay period. In that situation, early access can relieve pressure for a moment but may leave less available later. A budget conversation, a change to bill timing, or a dedicated savings buffer may address the recurring issue more directly. Likewise, someone who dislikes connecting financial accounts or prefers to track every transaction manually may be more comfortable with a simple spreadsheet or a privacy-conscious budgeting method.
It is also not the best fit for someone seeking a broad investment service or a full replacement for their bank’s tools. The app is centered on pay and personal money management, so I would compare it with alternatives according to those needs. If the main aim is to see account balances, a banking app might be enough. If the aim is detailed long-term planning, a specialist budgeting or planning tool may offer a better match. ONE@Work makes more sense when near-term cash flow is the actual pain point.
Questions worth settling before relying on it
A natural question is whether early pay will always be available in the amount someone wants. I would not build a fixed bill-payment plan around an assumption that every early-access request will work exactly the same way. Before relying on it for a due date, check the options presented in the app and keep a backup plan for essential payments. That is a sensible safeguard with any tool that affects the timing of income.
Another question is whether using the app means changing how a person gets paid. Since ONE@Work is intended for work-related pay access, I would check the setup steps and eligibility shown in the app before making it part of a routine. If an employer or payroll arrangement does not support the workflow a user expects, the app may not solve their particular cash-flow problem. A few minutes spent understanding the setup is better than discovering a mismatch when a bill is due.
People may also wonder whether its guidance can replace professional financial advice. I would not treat spending insights or automated suggestions as a substitute for help with debt, taxes, or complex financial decisions. They can make everyday patterns easier to notice, but context matters: income changes, family responsibilities, and irregular expenses can all affect what a sensible plan looks like. For ordinary budgeting, the app may be a useful companion; for serious or complicated financial concerns, a qualified adviser or trusted support service may be more appropriate.
ONE@Work is free, which makes it easier to try without paying an upfront price, but I would still judge it by the practical value and the account access involved. The current version is 10.106.1, and it supports Android 7.0 or later. The app was released on September 6, 2016, and has received 26,000 reviews. Those details give a sense of its history and reach, though my decision would still turn on whether its pay and budgeting tools suit my own situation.
Why You Should Consider It
If you’re someone who struggles with keeping track of your spending or just wants a better way to manage your money, this app could be a lifesaver. The insights it provides can help you make informed decisions about your finances, ensuring you’re not left in the lurch when you need funds the most.
Moreover, the app’s commitment to security is commendable. With bank-level encryption, you can rest assured that your financial data is safe and sound. It’s like having a digital vault that only you can access.
In a nutshell, ONE@Work is not just an app; it’s a financial revolution waiting to happen. Whether you’re a financial novice or a seasoned expert, this app has something valuable to offer you. So why not give it a try and see how it can transform your financial life?
Remember, managing finances doesn’t have to be a chore. With the right tools, it can be a walk in the park. So go ahead, download the app, and take the first step towards financial freedom. You won’t regret it!
My verdict on the trade-off
I would recommend ONE@Work to a worker who wants a practical way to think about pay timing and everyday spending, especially when an unexpected expense arrives between paydays. I would not recommend treating early access as a standing source of extra income or assuming its spending guidance sees every part of a person’s financial life. Used with a clear limit and a quick look ahead at upcoming bills, it can be a useful aid. If the underlying problem is a repeated shortfall, I would choose a more lasting budgeting or financial-support approach alongside—or instead of—relying on earlier pay.
Pros and Cons
Pros
- User-friendly interface makes navigation simple.
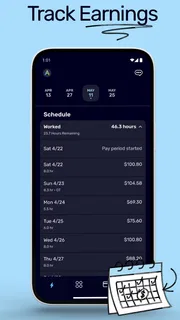
- Supports financial wellness with paycheck insights.
- Offers early access to earned wages.
- Integrates seamlessly with major payroll systems.
- Provides personalized financial guidance.
Cons
- Limited availability to certain employers.
- Features may vary based on user's employer.
- Requires access to sensitive financial data.
- Customer support can be slow to respond.
- Subscription fee may apply for full features.
Advertisements
Other Releases by ONE Finance, Inc.
View All Other Releases by ONE Finance, Inc.How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 ONE@Work (formerly Even)ONE Finance, Inc. | 4.8 | 1,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |

Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is ONE@Work and how does it function?
ONE@Work (formerly Even) is a financial wellness app designed to help employees manage their finances more effectively. It provides tools such as budgeting assistance, savings programs, and access to earned wages before payday, helping users avoid payday loans and high-interest credit. The app integrates with users’ bank accounts to provide a comprehensive overview of their financial health.
Is ONE@Work safe to use for my financial transactions?
Yes, ONE@Work employs bank-level security to ensure that all financial information is kept secure. The app uses encryption and other security measures to protect sensitive data. Additionally, it only accesses the information necessary to provide its services, ensuring user privacy and data protection.
Can ONE@Work help me save money?
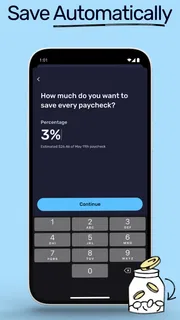
Absolutely. ONE@Work offers a variety of tools aimed at helping users save money. It includes features like automated savings, which allows users to set aside money from their paycheck automatically. Additionally, the app provides personalized financial advice and budgeting tools to help users manage expenses and increase their savings over time.
How does accessing earned wages early through ONE@Work work?
ONE@Work allows users to access a portion of their earned wages before payday, providing a flexible financial option for those in need of funds. Users can request an advance on their earnings, which is then deposited directly into their bank account. This service helps avoid the need for costly payday loans and bridges financial gaps until the next paycheck.
Are there any fees associated with using ONE@Work?
While ONE@Work offers many free features, there may be fees associated with certain services, such as accessing earned wages early. It's important to review the app's terms and conditions or contact customer support for detailed information on any potential fees. Many users find that the benefits, such as avoiding payday loan interest, outweigh the costs.
Advertisements

Download ONE@Work (formerly Even)
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 10.106.1
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.