


Navy Federal Credit Union
Navy Federal
Advertisements
App Specs
- Version
- 2026.8.1
- Updated
- Nov 1, 2026
- Android Version
- 11
- Installs
- 10,000,000+
- Developer
- Navy Federal
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
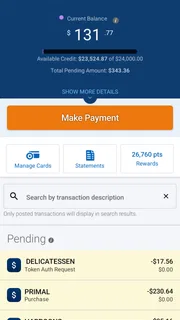
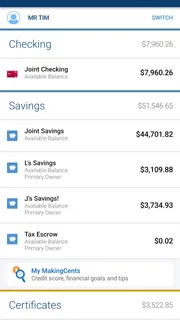
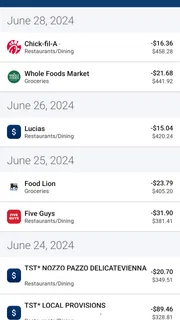
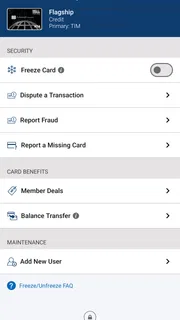
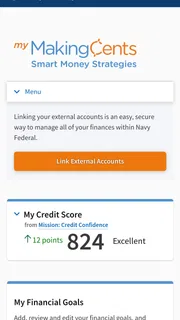
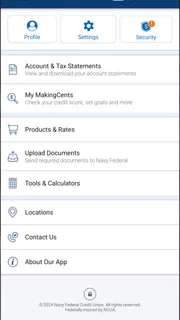
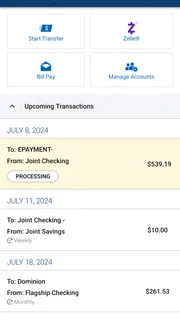
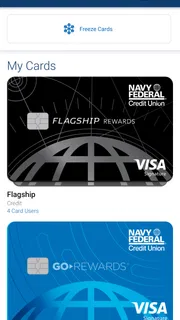
Our Review
 Analysis byUnlimiteds
I approached Navy Federal Credit Union as the sort of finance app I would use between errands rather than as a complete replacement for every banking tool. It is free, aimed at Everyone, and developed by Navy Federal, so its main value is straightforward access to that credit union’s services from a phone. The store summary, “Our Members Are the Mission,” points to a member-focused identity, but the practical question is simpler: does the app make everyday money management easier?
My answer is cautiously positive for Navy Federal members. The app gives a familiar mobile route into their financial relationship, and the large user base suggests it has become a regular part of many members’ routines. At the same time, a credit-union app is only useful if you already belong to that institution or intend to use its services. It is not a general-purpose budgeting app, a universal wallet for every bank account, or an especially sensible download for someone who has no connection to Navy Federal.
How Navy Federal’s app feels in its current state
The current version is 2026.8.1, and the app has been available since July 29, 2011. That long presence matters because financial apps need to feel dependable more than flashy. I would rather have a clear path to routine account tasks than a screen full of decorative extras. Navy Federal’s mobile experience is best judged by how quickly it helps me check what happened with my money, make a payment, move funds, or handle a basic banking job without reaching for a computer.
Its category is finance, but that label covers very different products. Some finance apps focus on investing, some on expense tracking, and others on digital payments. This one is tied to the Navy Federal relationship itself. That distinction affects nearly every decision about whether it is right for you. If your accounts, loans, or cards are with Navy Federal, having the official app nearby can reduce the friction of managing them. If your goal is to see balances from several unrelated institutions in one place, a dedicated aggregation or budgeting service may fit better.
The app’s reach is substantial: it has passed ten million installs and holds an average rating of 3.7 from roughly one hundred ten thousand ratings. I would read those figures as evidence of broad use, not as proof that every member will have the same experience. Finance apps often receive low scores when a login problem, update issue, or device-specific bug blocks access to something urgent. A middling average deserves attention, but it should be weighed alongside the app’s purpose and your own relationship with the credit union.
For a normal weekday, I can imagine opening it before paying a bill, checking whether a deposit has arrived, or confirming that a card transaction is legitimate. Those are small actions, yet they are exactly where a mobile banking app earns its place. I do not need a long session. I need accurate information, sensible navigation, and confidence that I am looking at the right account before I move money.
A realistic everyday workflow
Imagine getting a notification about a purchase while standing in a supermarket. I would open the app, verify the transaction against the amount on my receipt, and then review the available balance before deciding whether to make another payment that day. Later, I might use the same session to inspect a recurring charge and check whether a scheduled payment is still appropriate. The useful habit here is not simply “check your balance”; it is using the app as a quick verification point before a small financial decision.
That workflow also shows why mobile access can be more valuable than a desktop-only banking site. I am more likely to check an unexpected transaction immediately when the tool is already on my phone. The trade-off is that a phone screen is less comfortable for reviewing a long history or comparing several accounts. For detailed reconciliation, I would still prefer a larger screen or a downloaded statement if that option is available through my account experience.
What the long product history tells me
An app that has existed since 2011 has had time to become part of members’ habits. That can be reassuring, especially for people who dislike changing financial tools every few months. It also raises a reasonable expectation: the app should continue adapting to modern devices and security demands instead of merely preserving an old interface.
The current release number shows that the product is actively maintained in the present era, but a version number alone does not tell me that every change will be visible or dramatic. In finance, some of the most important work may be behind the scenes: compatibility, reliability, authentication behavior, and the handling of edge cases. I would not install an update expecting a completely redesigned banking experience. I would install it because keeping a financial app current is usually the safer and less frustrating choice.
What existing users may notice after updates
For someone who already uses Navy Federal on a phone, the biggest benefit of ongoing development is continuity. A current release should be a better bet for compatibility with a newer operating system than an abandoned application. The minimum operating system is iOS or Android version 11, so owners of older devices need to check that their phone meets this requirement before planning around the app.
That requirement is not a trivial footnote. A member with an aging phone may face a choice between updating the device, using another access method, or staying with a browser. I would check the operating system before deleting an older banking setup, particularly if the phone is used for authentication or other account access. The app is free, but avoiding a download charge does not remove the possible cost of an incompatible device.
Updates can also change familiar navigation. I recommend that existing users avoid making their first post-update session an urgent payment or transfer. Open the app when you have a few quiet minutes, confirm that you can sign in, locate the accounts you use most, and review any saved routines. This is a practical precaution, not a criticism of Navy Federal specifically: financial interfaces are poor places to discover a changed button while a deadline is approaching.
The broad rating of 3.7, alongside around forty-three thousand written reviews, tells me that user sentiment is mixed rather than uniformly enthusiastic. I would not treat every complaint as a permanent flaw, because app reviews can reflect temporary outages or individual device problems. Still, the volume of written feedback is a reminder to keep a backup way to contact the credit union or access important information. A mobile app should be convenient, but I would not make it the only route to a time-sensitive financial task.
Where it is stronger than usual alternatives
Compared with a generic budgeting app, Navy Federal’s app has the advantage of being connected to the institution that actually holds the member’s accounts. That usually makes it the more natural place for account-specific actions. A budgeting app may be better at showing spending patterns across several providers, but it is not the tool I would choose first when I need to deal directly with a Navy Federal relationship.
Compared with using a mobile browser, a dedicated app can feel more immediate. The icon is always available, and the experience is designed for a phone rather than a desktop page squeezed into a small display. I also prefer an official institution-specific app over an unofficial utility when the task involves financial credentials. The important qualification is that convenience should not override basic caution: I would install it through the recognized app marketplace, keep the phone protected, and avoid signing in over a connection I do not trust.
Compared with a standalone payment wallet, this app serves a wider account-management purpose. A wallet is excellent for a quick purchase, but it is not where I would expect to review the broader relationship behind that payment. Navy Federal’s app makes more sense when I need context around an account, rather than only a fast tap at a checkout terminal.
Three habits that make the app more useful
First, I would use it as a transaction-checking tool, not just a balance display. A balance can look acceptable while an unfamiliar charge is waiting to be noticed. Reviewing recent activity after unusual spending helps me catch mistakes sooner and keeps the app connected to real decisions rather than passive checking.
Second, I would separate quick checks from serious record keeping. The phone is ideal for confirming whether something posted or whether funds appear available. For tax preparation, household reconciliation, or a dispute that requires careful documentation, I would move to a larger screen and save the relevant records through the account’s available channels. This division prevents the small interface from becoming a source of avoidable errors.
Third, I would keep a backup routine. Before traveling or making a large scheduled payment, I would make sure I know how to reach Navy Federal through another official channel if the app is unavailable. That is especially sensible given the mixed rating and the fact that no single mobile application should be treated as infallible. The app can be my first choice without being my only choice.
Who should use it, and who should skip it
I think it is a sensible download for an active Navy Federal member who wants convenient phone access to everyday financial tasks. It is also a reasonable fit for someone who already manages money primarily from a smartphone and does not want to open a browser each time an account question comes up. The free price removes one barrier, while the Everyone age classification makes it broadly approachable from a store-policy perspective.
I would be more hesitant to recommend it to someone who wants a single dashboard for accounts at multiple banks, detailed envelope budgeting, investment analysis, or advanced household reporting. Those needs belong to more specialized tools. I would also ask whether a person is comfortable relying on a phone for financial access. If they prefer paper records, branch conversations, or a desktop workflow, downloading the app may add little value.
It is not the right choice merely because it has more than ten million installs. Popularity cannot turn an institution-specific app into a universal money manager. The first question is membership and account relevance; the second is whether mobile access matches the way you actually handle money.
Remaining friction and practical limitations
The most obvious limitation is scope. This is not a neutral finance workspace where I can freely combine every financial provider, build a complete spending plan, and compare products across the market. Its usefulness is concentrated around Navy Federal. That focus is a strength for members and a dead end for everyone else.
The second limitation is the tension between convenience and screen size. A phone is excellent for a quick confirmation, but less pleasant for investigating many transactions or planning a complicated set of payments. I would be careful with tiny labels, similarly named accounts, and any action where selecting the wrong destination could have consequences. Taking an extra moment to verify the account and amount is more important than finishing quickly.
The third is that the rating suggests room for improvement in the lived experience. I cannot infer one universal cause from a store score, but I can make a practical recommendation: keep the app updated, use a supported operating system, and do not wait until a deadline to discover whether your particular device and login routine work smoothly. If access repeatedly becomes a problem, the better solution may be another official access channel rather than endless retries.
What I would watch as the app evolves
With version 2026.8.1 currently in place, I would watch future releases for improvements that affect trust more than appearance. Clearer error messages, predictable sign-in behavior, accessible account labels, and smooth handling of routine tasks would matter more to me than a cosmetic redesign. Those details determine whether the app feels dependable when I am distracted or in a hurry.
I would also pay attention to how well the experience serves both long-time members and people joining the mobile workflow for the first time. A mature app can accumulate layers of navigation that make sense to existing users but confuse newcomers. The best evolution would preserve familiar paths while making the first few sessions easier to understand.
Finally, I would look for evidence that the app remains useful without trying to become everything at once. Navy Federal does not need to imitate every budgeting, investment, or payment product. Its strongest identity is direct mobile access to the credit union. If future development protects that clarity while reducing friction, the app will remain a practical companion rather than another crowded finance dashboard.
My final recommendation
I would recommend Navy Federal’s app to members who want a convenient, official way to stay close to their accounts from a supported phone. My experience of its role is practical rather than exciting: it is most valuable in short sessions, when I need to verify activity, check a balance, or handle an ordinary account task without sitting at a computer.
I would not recommend it as a replacement for a dedicated budgeting service, a multi-bank dashboard, or a careful desktop review of complex finances. Its mixed average rating means I would keep expectations realistic and maintain a backup access method. Even so, the combination of a long product history, active current version, free availability, and broad adoption makes it worth trying for the people it is actually designed to serve.
My bottom line: if Navy Federal is already your credit union, install it, test the everyday tasks you care about, and keep the app current. If you are looking for a general finance manager unrelated to Navy Federal, skip it and choose a tool built around that broader job.
Pros and Cons
Pros
- No monthly maintenance fee on many checking accounts.
- Large surcharge-free ATM network through CO-OP and participating locations.
- Strong mobile app security with biometric login and alerts.
- Wide range of loan
- mortgage
- and credit card options.
- Excellent support for military members and their families.
Cons
- Membership is limited to eligible military groups
- veterans
- and families.
- Some products require a minimum opening deposit or balance.
- Branch availability is limited outside military communities.
- International transaction and ATM fees may apply on some accounts.
- Certain features can be less convenient for non-members or joint users.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Navy Federal Credit UnionNavy Federal | 3.7 | 10,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Navy Federal Credit Union, and who can join?
Navy Federal Credit Union is a member-owned financial institution offering checking and savings accounts, credit cards, loans, mortgages, and other banking services. Membership is generally available to active-duty military members, veterans, Department of Defense personnel, certain government employees, and eligible family members. Before downloading the app, confirm that you qualify for membership and have the information needed to verify your eligibility.
What can I do with the Navy Federal mobile app?
The Navy Federal mobile app lets eligible members manage many everyday banking tasks from an Android or iOS device. Depending on your account and location, you can check balances, review transactions, transfer funds, pay bills, deposit checks remotely, manage cards, apply for selected products, and locate branches or ATMs. Available features may vary, so some services could still require the website or a representative.
Is the Navy Federal app safe to use for mobile banking?
The app is designed for secure access to Navy Federal accounts and may support protections such as encrypted connections, login verification, device authentication, alerts, and biometric sign-in where available. However, security also depends on your habits. Download it only from the official Google Play Store or Apple App Store, keep your device updated, avoid public Wi-Fi for sensitive tasks, and never share passwords or verification codes.
Does Navy Federal charge fees for using the app or mobile check deposit?
Downloading and using the Navy Federal mobile app is generally not the same as paying a separate app subscription fee, but certain banking services may have account-specific fees, limits, or eligibility requirements. Mobile check deposit can also involve rules concerning endorsement, check type, daily limits, and availability of funds. Review the current fee schedule and deposit terms before relying on the feature.
What should I do if I cannot log in or notice suspicious activity?
If you cannot access your account, first check your internet connection, confirm that the app is updated, and use the official password or username recovery options rather than links from unsolicited messages. If you see an unfamiliar transaction, receive unexpected security alerts, or believe your credentials are compromised, contact Navy Federal through an official channel immediately. Avoid sharing account details with anyone claiming to offer unofficial support.
Advertisements

Download Navy Federal Credit Union
Unlimiteds is available from its official store. We do not host or distribute app downloads.
About This Listing
- Last Checked
- Nov 1, 2026
- Version Reviewed
- 2026.8.1
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.