


Instant Cash Advance: CashHoop
Advertisements
App Specs
- Version
- 1.0.15
- Updated
- Nov 7, 2026
- Android Version
- 7.0
- Installs
- 1,000,000+
- Developer
- Biskup Apps
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
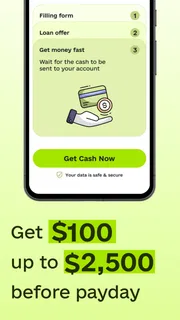
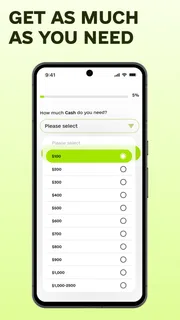
Our Review
 Analysis byUnlimiteds
When an unexpected bill lands between paydays, the hardest part is often not finding a financial app but deciding whether speed is worth the trade-off. Instant Cash Advance: CashHoop is built for that exact moment. It is a free finance app from Biskup Apps that focuses on cash advances and tax filing, with a simple promise: help you handle an urgent expense without turning the search into a long research session.
After looking at it as an everyday money tool, my view is fairly clear. CashHoop can be useful when timing matters and you need to explore an advance quickly, but it should not become a substitute for a proper budget or a cheaper source of short-term help. Its strongest quality is convenience. Its biggest weakness is that convenience can make borrowing feel easier than it really is.
Start with the decision, not the download
Before opening CashHoop, I would ask two practical questions: is this expense essential, and can I repay an advance without leaving another necessary bill uncovered? Those questions matter more than how quickly an app gets you to an application. If the answer to either is uncertain, checking a payment extension or asking the biller about options may be a better first move.
This is a useful distinction for anyone searching for “instant” help. The word describes the kind of problem the app is meant to address, not a guarantee that every person will receive money immediately or qualify for an option. I would approach the app as a place to explore, then judge any next step on its own terms.
What using CashHoop feels like in real life
The app sits in the finance category, but it is more focused than a general banking app. A traditional banking application usually centers on account balances, transfers, cards and transaction history. CashHoop instead aims at two specific tasks: seeking a cash advance and working through tax-related needs. That narrower purpose makes it easier to understand why you opened it.
I can imagine using it after a car repair unexpectedly takes priority over groceries, or when a utility payment is due before the next paycheck. In that situation, the value is not entertainment or long-term financial planning. The value is having one place to start instead of searching through unrelated lending pages while stressed.
The app is free to install, which lowers the barrier to checking whether it fits your situation. It is rated for Everyone, and the minimum operating-system requirement is Android 7.0 or later. That broad compatibility is practical for people who keep an older phone rather than upgrading frequently.
CashHoop has also attracted a sizeable audience: it has passed one million installs, with an average rating of 4.6 from roughly twenty-six thousand ratings. Those figures suggest that the basic experience works well for many users, although popularity should never be confused with proof that an advance is affordable for every borrower.
The useful part is the quick starting point
What I like most is the way the app addresses a problem people usually face under pressure: where do I begin? A cash advance search can become confusing when several services use similar language and every option seems urgent. CashHoop gives that search a dedicated home, which can reduce the mental effort involved in taking the first step.
That does not mean I would tap through every offer automatically. I would use the app as a screening tool, then slow down before accepting anything. The important details are the total repayment amount, the repayment date, any fees, and what happens if the payment cannot be made on time. A fast application is only helpful if the obligation remains manageable after the emergency has passed.
One practical habit makes the app safer to use: open it with the bill in front of you and write down the exact amount you need before starting. If the repair costs less than expected, do not treat the difference as extra spending money. Borrowing only the necessary amount keeps the decision connected to the original problem instead of allowing a small emergency to become a larger balance.
Tax work gives the app a second purpose
The tax-filing side is an interesting addition because it gives CashHoop a role beyond urgent borrowing. Many people think about filing only when a deadline is close, and that is often the same period when cash flow feels tight. Having tax-related tools and advance-related help in the same app may make the overall process feel more connected.
I would still separate the two decisions mentally. Filing taxes is an administrative task; taking an advance is a borrowing decision. Completing one should not make the other feel automatically justified. If the app presents both parts during the same visit, I would finish the tax work first, review the result carefully, and only then decide whether an advance is genuinely needed.
A useful workflow is to keep records ready before opening the tax section. Gather the documents and figures you already know you will need, rather than beginning while searching through email or paper files. This reduces interruptions and makes it easier to notice whether a number has been entered incorrectly. The app may make the process more convenient, but it cannot replace careful checking of personal information.
Where the experience needs caution
The central limitation is not necessarily a missing button or a complicated screen. It is the financial tension built into instant borrowing. Speed can be reassuring, especially when a bill is urgent, but it can also discourage comparison. I would not accept the first available option simply because it appears quickly.
Before agreeing to anything, I would look for the complete cost rather than focusing on the amount arriving in the account. An advance that solves today’s problem but leaves too little for rent, food or transportation next week is not a successful solution. The app can help with access, but the responsibility for judging affordability remains with the user.
This is also why CashHoop is not the right choice for someone who already has recurring difficulty covering ordinary expenses. If every pay cycle requires an advance, the problem is probably structural rather than temporary. A conversation with a bank, credit union, nonprofit counselor or trusted financial adviser may be more useful than repeating short-term borrowing.
I would also avoid using it for nonessential purchases. A delayed gadget, restaurant meal or optional subscription does not justify the same urgency as a necessary repair or a basic household bill. The clearer the emergency, the easier it is to decide whether the cost of borrowing is acceptable.
How it compares with familiar alternatives
Compared with a bank app, CashHoop is more specialized and less suitable for managing an entire financial life. A bank application is usually the better place to review regular income, recurring payments and account history. That information helps you understand whether an advance fits the rest of your month. CashHoop is more useful when the immediate task is exploring a cash advance rather than monitoring a checking account.
Compared with a credit card, the decision depends on the complete terms and your ability to repay. A card may offer more flexibility, but it can also encourage a balance to remain open for a long time. A cash advance may feel more contained because it is tied to a specific repayment arrangement, yet that does not automatically make it cheaper. I would compare the total cost and timing rather than choosing based on the label.
Compared with asking an employer about an earned-wage option, CashHoop may be more convenient for someone who wants to investigate independently. However, an employer-based arrangement or a small emergency fund could be less disruptive to future cash flow. Those alternatives are worth checking before borrowing, particularly when the need is predictable.
Compared with a tax-only application, CashHoop may be appealing to someone who wants tax filing and advance-related help in one place. The trade-off is focus: a dedicated tax product may suit a person who wants nothing else around the filing process, while CashHoop makes more sense for someone who values the combination.
Small habits that make a big difference
My first recommendation is to treat the application process as a comparison moment, not a checkout screen. Keep a note of the amount requested, the amount received, the amount repaid and the date of repayment. Seeing those figures together is much more informative than remembering only the amount deposited.
Second, check the repayment date against your actual payday and fixed bills. A date that looks reasonable in isolation can be difficult if it falls just before housing costs or insurance. I would map the next two weeks of essential spending before accepting anything, even if the application itself takes only a short time.
Third, avoid opening the app repeatedly just because it is available. Rechecking an advance after a stressful day can turn a temporary idea into an impulsive decision. If the emergency is real, write down the reason and the maximum amount first. If the reason changes from “cover a necessary bill” to “have extra money,” I would stop and reconsider.
For tax filing, I would save confirmation details and review the final information before submitting. A convenient workflow is valuable only when the result is accurate. I would also avoid switching between several tasks in one sitting; mixing tax entries with borrowing decisions makes it harder to notice mistakes and easier to rush.
Who should consider it
CashHoop is best suited to an adult who has a genuine short-term cash problem, understands that an advance must be repaid, and wants a focused place to explore the available process. It may also suit someone who wants tax-filing assistance alongside that financial task instead of maintaining separate apps.
The app is especially practical for people using an older Android phone, since Android 7.0 is enough to meet its minimum requirement. Its free access also means you can inspect the experience without paying an upfront download charge. That does not remove the need to examine the terms of any financial product reached through the app.
I would recommend a more cautious approach for a first-time borrower. Read every screen, take a screenshot or note of important terms for your own records, and do not assume that the app’s friendly presentation means the advance is low-cost. If anything is unclear, pause rather than guessing.
People who should probably skip it include users looking for full budgeting, investing, banking or debt-management features. CashHoop is not presented as an all-purpose financial command center. Someone who wants to track spending categories, set long-term savings targets and manage multiple accounts will likely be better served by a dedicated budgeting or banking application.
A realistic moment to use it well
Imagine that a necessary car repair arrives just before payday and the mechanic needs an answer. I would first confirm the final repair amount and ask whether the payment can be split or delayed. If neither is workable, I would open CashHoop with that amount written down, inspect the available terms, and compare the repayment date with rent, groceries and transportation costs already due.
If the repayment would force another advance later in the month, I would treat that as a warning rather than a reason to borrow more. If the figures fit and the expense is genuinely urgent, an advance may be a reasonable bridge. The important point is that the app should support a decision I have already thought through, not make the decision for me while I am under pressure.
What to check before committing
A sensible final check is to make sure you understand what happens after tapping through the application: what amount you would receive, what you would owe, and when repayment is expected. I would also read any conditions presented before agreeing, especially details about fees or missed payments. If the language feels unclear, stop and seek an explanation instead of relying on an assumption.
Another useful safeguard is to compare the proposed repayment with the money that will actually remain after essentials. A payday is not disposable income if it is already spoken for by housing, food or transport. This small calculation can reveal when a seemingly manageable advance would simply move the shortfall to a later date.
My verdict after weighing convenience against cost
The current release is version 1.0.15, and the app’s strong rating shows that many people find its approach useful. I can see why: the purpose is easy to grasp, the download is free, and the combination of cash-advance access with tax filing addresses two situations that often arise when money is tight.
Still, I would recommend CashHoop with a condition, not as a blanket endorsement. Use it when the need is specific, the repayment plan is realistic and you have checked the full cost. Do not use speed as a reason to skip comparison, and do not let a short-term advance hide a longer-term budget problem.
For me, the app’s best role is as a starting point during a genuine financial interruption. It can reduce the friction of finding help and keep tax-related work close at hand. Its weakest role is as a repeated solution for ordinary monthly shortfalls. In that situation, a slower but more sustainable alternative is better.
My recommendation is simple: CashHoop is worth considering for a carefully measured, short-term need, especially if its tax tools are also relevant to you. Open it prepared, borrow only what the emergency requires, and compare the repayment obligation before committing. Used with that discipline, it is a convenient finance app; used casually, it can make an expensive decision feel deceptively easy.
Pros and Cons
Pros
- Simple application process with clear steps for requesting an advance.
- May help cover unexpected expenses between regular paychecks.
- Application is convenient for users who prefer managing finances by phone.
- Repayment details are presented before accepting an advance.
- Useful for comparing available advance amounts and potential fees.
Cons
- Eligibility and advance amounts may vary based on personal financial information.
- Fees or other costs can make borrowing expensive for short-term needs.
- Repayment may be withdrawn automatically on the scheduled due date.
- Late repayment could lead to additional charges or financial pressure.
- Availability and features may depend on location and banking compatibility.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Instant Cash Advance: CashHoopBiskup Apps | 4.6 | 1,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Instant Cash Advance: CashHoop?
Instant Cash Advance: CashHoop is a financial app designed to help eligible users request short-term cash advances through a mobile device. After creating an account and providing the requested personal and financial information, users can review available offers, repayment terms, fees, and other conditions. Approval, advance amounts, and funding speed are not guaranteed and may depend on eligibility, verification, and applicable regulations.
How does CashHoop’s cash advance process work?
After downloading CashHoop, you generally need to register, verify your identity, connect or provide information about a qualifying bank account, and complete the application. If you qualify, the app may show an advance offer with details such as the amount, repayment date, fees, and any optional services. Review every term carefully before accepting, since the final decision and delivery time can vary.
Are there fees or other costs associated with CashHoop?
CashHoop may involve fees or charges depending on the advance, payment method, optional features, and your location. Before confirming an offer, check the complete cost, including any membership, expedited-transfer, subscription, late-payment, or other applicable fees. Do not rely only on promotional wording or an estimated amount. The disclosure screen and official terms should be treated as the most accurate source.
Is CashHoop available to everyone, and what information is required?
No, access to CashHoop services is not necessarily available to every applicant. Eligibility may depend on factors such as age, residence, income, banking history, identity verification, and the requirements of lending or financial partners. The app may request sensitive information, including contact, employment, bank-account, and identification details. Only submit information through the official app or verified website.
When will I receive the money, and how is repayment handled?
Funding time can differ based on approval, bank processing, weekends, holidays, and whether you select a standard or expedited delivery option. Repayment is usually scheduled for a future date and may be collected from the linked bank account or another authorized method. Confirm the exact due date and payment amount in advance, and contact official support promptly if you anticipate difficulty repaying.
Advertisements

Download Instant Cash Advance: CashHoop
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 1.0.15
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.