

Instacart Shopper Rewards
Branch Messenger
Advertisements
App Specs
- Version
- 2026.8.3
- Updated
- Nov 6, 2026
- Android Version
- 10
- Installs
- 100,000+
- Developer
- Branch Messenger
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
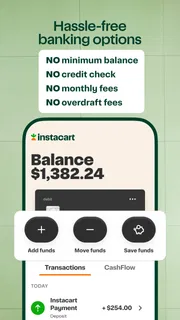
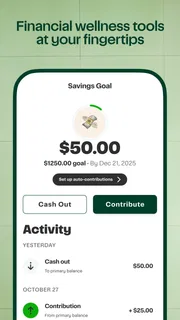
Our Review
 Analysis byUnlimiteds
When I look at a finance app, I want to know one thing before anything else: does it make a real money task easier, or does it simply put a familiar service in a new wrapper? Instacart Shopper Rewards is aimed at a very specific audience, namely people who shop for Instacart and want to explore the debit-card side of that work. That focus makes it more interesting than a general-purpose banking app, but it also means the right choice depends heavily on how closely your daily income and spending are tied to Instacart shopping.
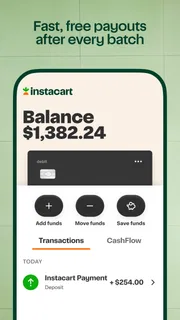
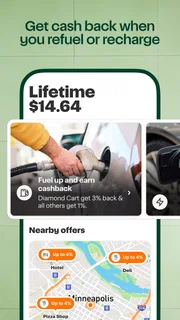
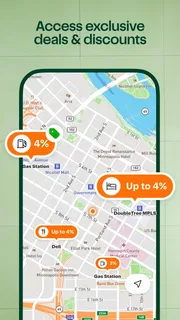
I approached it as a decision rather than a popularity contest. The app is free, carries an Everyone age rating, and comes from Branch Messenger. Its store summary presents it as a way to discover a new debit card, while the short description identifies the Instacart Shopper audience directly. That combination tells me this is not designed to replace every financial tool on your phone. It is a focused option for shoppers who want to examine a card connected with their work routine.
What to consider before choosing it
I’d weigh the app’s focused appeal against the ongoing effort of managing a separate financial routine. Before deciding, I’d identify one recurring task the card should make simpler, then consider whether I’ll still value that separation when my shopping schedule changes. That gives me a practical test for lasting usefulness, rather than relying on first impressions alone.
The first question is whether you are an Instacart shopper
The most important filter is not the app’s average rating or install count. It is whether you actually shop for Instacart. If you do, the app’s narrow purpose may be helpful because it keeps the financial conversation close to the work you already do. If you do not, there is little reason to treat this as a general debit-card discovery tool. A broad banking app, a conventional prepaid product, or the financial service you already use will probably make more sense.
I also think about frequency. Someone who shops occasionally may not gain enough from adding another financial app to their phone. A person who shops regularly, checks earnings often, and wants a separate place for work-related money has a clearer reason to investigate it. The app is most compelling when the card is part of a repeatable routine rather than a one-time experiment.
Separate the card decision from the app decision
It is easy to treat a polished mobile experience as proof that the underlying financial product is right for you. I would avoid that shortcut. The application is the access point, but your actual decision should include how you plan to use the debit card, where your money normally goes, and whether you are comfortable managing another account or payment method.
Before committing, I would write down the jobs I expect the card to handle. For example, do I want a dedicated place for shopper-related funds, a way to separate work spending from household spending, or simply a debit card to try? Those are different needs. A focused app may suit the first two, while a regular bank account may be better for someone who wants savings tools, bill management, and a broader financial dashboard in the same place.
Think about visibility and control
Finance apps are only useful when they help me understand what is happening with my money. With a work-linked debit-card app, I would pay particular attention to how easily I can distinguish shopper activity from personal purchases, how quickly I can find the information I need, and whether the workflow feels clear enough to use during a busy day. I would not want to make a financial decision while standing in a store aisle and then struggle to understand it later.
A useful habit is to decide in advance what the app will be used for and what will remain in your main financial account. Keeping that boundary clear can prevent a dedicated card from becoming an unplanned replacement for your entire banking setup. In my view, this kind of separation is one of the more practical reasons to consider a specialized product.
What the current app details tell me
The application launched on August 6, 2025, and its current version is 2026.8.2. It has an average rating of 4.3 from 549 ratings, with 141 written reviews and 100K+ installs. Those figures suggest that people are using it and that the overall response is positive, but I would still read the written feedback with care. A rating can tell me whether the broad experience is acceptable; it cannot decide whether the card fits my own work pattern.
The minimum operating-system requirement is Android 10, which is worth checking before installation. I would also make sure my phone has enough room for another finance app and that I am comfortable keeping work-related financial access on the device I use every day. Those are small practical checks, but they matter more here than they would for a casual entertainment download.
Where this product is likely to win
Its biggest strength is focus. Instacart Shopper Rewards is not trying to speak to every kind of consumer. Its identity is built around the shopper experience, and that can reduce the mental distance between earning through Instacart and managing the related debit-card option. For a shopper who wants a work-oriented financial lane, that focus is more useful than a crowded app filled with unrelated banking features.
I can also see value in having a dedicated workflow for people who prefer separation. Imagine finishing a long shopping day and wanting to keep the money connected with that work distinct from rent, groceries, or family spending. A separate debit-card arrangement can make that boundary easier to maintain. It does not automatically create better budgeting, but it can make the categories more visible if I use it deliberately.
Another advantage is reduced comparison fatigue. General finance apps often ask users to sort through checking, savings, credit, transfers, rewards, investing, and other products. A shopper-focused app gives me a smaller decision surface. That is helpful when I already know why I am looking: I want to understand the debit-card option associated with Instacart shopping, not browse an entire financial marketplace.
A realistic day-to-day use case
Picture a shopper who works several blocks away from home and uses a personal bank account for household expenses. Before starting a shift, that shopper can decide that the debit-card app is for work-related money and routine purchases during shopping hours, while the main account remains the place for recurring bills. After the shift, the shopper reviews activity and keeps the two purposes separate.
The important part of this scenario is not the number of transactions. It is the workflow. The app becomes useful because the shopper has assigned it a clear job. Without that plan, a second card can create more confusion than convenience. I would begin with a small, understandable use case, observe how it fits my routine, and only then decide whether it deserves a larger role.
Small habits that make a specialized card easier to manage
My first tip would be to name the purpose in plain language before using the card. “Instacart work” is more useful as a mental label than simply “another debit card.” That distinction helps when I review my finances later and prevents accidental mixing with personal spending.
My second tip would be to check the app at a fixed point in the day rather than repeatedly opening it between shopping tasks. A short review after work is less distracting and gives me a better chance of noticing activity that needs attention. This is especially relevant for shoppers, whose working day already involves constant movement and time pressure.
My third tip would be to keep a fallback payment method available. A dedicated work card may be convenient, but relying on one payment route for every situation can be uncomfortable. I would carry or retain access to my normal financial option until I had enough experience to know that the new arrangement works smoothly for me.
Where a different type of app may fit better
The main alternative is a traditional bank app. That route is usually better for someone who wants one central place for everyday banking, bill payments, long-term balances, and a wider view of personal finances. If my priority is a complete household money system, I would start with the bank I already trust rather than add a specialized shopper product.
A budgeting app can also be a better match when the real problem is spending visibility rather than access to a debit card. Budgeting tools are designed around categories, planning, and reviewing habits. Instacart Shopper Rewards may be more relevant to the card and shopper relationship, but it should not be chosen as a substitute for a budgeting system if budgeting is what I actually need.
Someone who wants a general prepaid or debit solution may prefer an app built for a broad consumer audience. That kind of service can be easier to keep after changing jobs or reducing shopper activity. The trade-off is that it may not feel as closely connected to the Instacart work routine. I would choose the broader option when flexibility matters more than specialization.
There is also a simple alternative: keep using the account and card you already have. Switching has a cost even when an app is free. I have to learn a new workflow, remember another login, monitor another financial destination, and decide which card to use at checkout. If the existing setup already handles my shopper-related needs without confusion, the specialized option has to offer a clear improvement before it is worth the change.
What switching really involves
The monetary price of the app is free, but “free” does not mean frictionless. The real cost can be attention. I would need to understand the card’s role, adjust any personal routine built around my current account, and make sure I do not overlook activity because I am checking the wrong application. That is why I would test the workflow gradually instead of moving every financial task at once.
I would also consider what happens if my relationship with Instacart changes. A shopper who expects to continue for a long time may value the app’s specialization. Someone treating shopping as a temporary source of income may prefer a more portable financial product. The best choice is not only about today’s convenience; it is about whether the arrangement still makes sense if my work pattern changes.
Another switching cost is record keeping. If I use one account for personal purchases and another for shopper-related activity, I need a simple method for remembering what happened where. I might review both apps during the same weekly money check, keep receipts organized, or use a note that records the purpose of unusual purchases. The exact method is personal, but the principle is important: separation only helps when I maintain it consistently.
Limits I would take seriously
The app’s narrow audience is both its advantage and its limitation. If I am not an Instacart shopper, the central reason to use it disappears. Even for shoppers, a focused debit-card app may not cover every financial need. I would not expect it to replace a full bank relationship, a dedicated savings strategy, or a detailed budgeting system simply because it sits in the finance category.
I would also avoid assuming that a positive rating guarantees a perfect experience for every user. The 4.3 average is encouraging, but personal expectations differ. A shopper who wants a simple, work-linked card may be satisfied, while another user may be frustrated by having to manage a separate financial destination. The written reviews are worth reading for patterns that match my own situation rather than treating the average as a promise.
Device compatibility is another practical boundary. Since the app requires Android 10 or newer, anyone using an older phone should check compatibility before planning around it. I would not change phones solely for this app. If the device requirement creates a problem, the sensible alternative is to use an existing financial arrangement or choose a service that works with the phone already in hand.
Who should choose it
I would recommend taking a close look at Instacart Shopper Rewards if you actively shop for Instacart, want to explore its debit-card option, and appreciate keeping work-related money distinct from personal finances. It is particularly suitable for someone who likes focused tools and is willing to create a clear routine around a separate card.
I would be more cautious if I rarely shop, already have a simple and effective bank setup, or dislike managing multiple financial apps. In those cases, the convenience may not outweigh the extra attention. I would also steer someone toward a traditional bank or budgeting app if their main goal is household money management rather than a shopper-oriented debit-card experience.
My final recommendation
After weighing the alternatives, I see this as a specialized finance app rather than a universal banking replacement. Its free price, shopper-specific purpose, and focused presentation make it worth considering for the people it is built around. The strongest case is not that it can do everything; the strongest case is that it may give an Instacart shopper a clearer way to organize a particular part of working life.
My recommendation is to try it only with a defined plan. Decide what the card will be used for, keep a backup payment method, review activity at a regular time, and compare the experience with the account you already use. If the separation makes your routine easier, the app has earned its place. If it adds another layer without solving a real problem, staying with your current bank or choosing a broader budgeting tool is the better decision.
In short, the right reason to use this app is control through specialization. I would recommend it to active Instacart shoppers who want to examine a dedicated debit-card route, not to anyone searching for a complete replacement for everyday banking. That honest boundary is what makes the product easier to judge: it can be a useful work-focused companion, but only when its limited purpose matches the way you actually handle money.
Pros and Cons
Pros
- Rewards can make frequent shopping trips more worthwhile.
- The program may offer useful savings on eligible shopper expenses.
- Reward progress is easy to monitor within the shopper experience.
- Benefits are tailored to active Instacart shoppers.
- No separate rewards app is generally needed to participate.
Cons
- Eligibility and benefits can vary by market or shopper status.
- Some rewards may require completing specific order milestones.
- Reward values and offers may change without much notice.
- Benefits may not offset fuel
- vehicle
- and maintenance costs.
- Inactive shoppers may find limited value in the program.
Advertisements
Other Releases by Branch Messenger
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Instacart Shopper RewardsBranch Messenger | 4.2 | 100,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |

Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Instacart Shopper Rewards?
Instacart Shopper Rewards is a benefits program designed for eligible Instacart shoppers. It may provide access to rewards, discounts, savings, or other perks connected with completing deliveries and maintaining shopper activity. The exact benefits can vary by location, shopper status, and current promotions, so users should review the terms shown in the app before relying on a specific reward or discount.
Who can participate in Instacart Shopper Rewards?
Participation generally depends on being an approved Instacart shopper and meeting the program requirements in your region. Some rewards may be available only to active shoppers, while others can depend on completed batches, earnings, account standing, or promotional eligibility. Availability is not necessarily the same for every user, so check the Rewards section of the Instacart Shopper app for your personal eligibility.
How do I access and redeem rewards in the app?
After signing in with your shopper account, open the relevant rewards, benefits, or account section in the Instacart Shopper app. Available offers should display their redemption instructions, expiration dates, and any required codes or links. Some benefits may be applied automatically, while others require registering with a partner or completing an additional step. Always read the conditions before redeeming.
Are Instacart Shopper Rewards free to use?
Access to the rewards program may not require a separate membership fee, but individual benefits can have restrictions, costs, or eligibility conditions. A discount does not always mean that a product or service is completely free, and partner offers may involve subscriptions, taxes, delivery charges, or minimum-purchase requirements. Confirm the final terms and price before accepting an offer.
What should I know about privacy and account security?
Instacart Shopper Rewards may use information connected to your shopper account, activity, location, or eligibility to display relevant benefits. Before downloading or using the app, review its privacy policy and permissions, and install it only from an official app store. Never share passwords or verification codes, and be cautious of messages promising rewards that request payment or sensitive personal information.
Advertisements

Download Instacart Shopper Rewards
About This Listing
- Last Checked
- Nov 6, 2026
- Version Reviewed
- 2026.8.3
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.