

Credit Card : Wallet & NFC
Galaxy studio apps
Advertisements
App Specs
- Version
- 3.0.5
- Updated
- Nov 6, 2026
- Android Version
- 7.0
- Installs
- 5,000,000+
- Developer
- Galaxy studio apps
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
I spent time with Credit Card : Wallet & NFC as a finance app, focusing on what it can realistically do for someone who handles several cards and wants quick access to card information. Its central idea is straightforward: combine a mobile wallet concept, an NFC scanner, and a credit or debit card BIN validator in one place. That makes it more specialized than a basic notes app, but it is also more limited than a complete banking or payment solution.
The app is free to download, which makes it easy to try without committing money first. It comes from Galaxy studio apps and is available for devices running Android 7.0 or later. The age rating is Everyone, so its presentation is aimed at a broad audience rather than professional financial users. I found that its appeal depends less on advanced money management and more on whether you regularly need to inspect, organize, or identify card-related information.
What the app actually offers in daily use
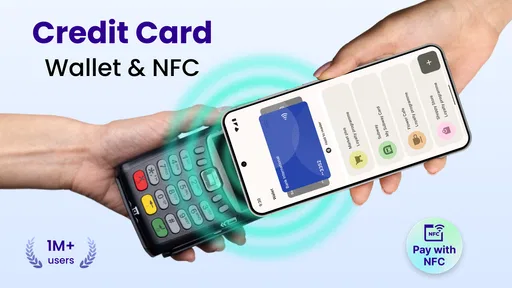
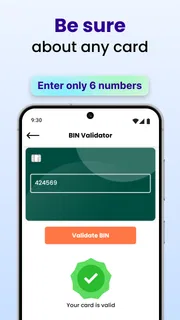
The most useful way to think about this app is as a card-information utility. The wallet angle suggests a convenient place to keep card details, while the NFC scanner adds a way to read compatible contactless information. The BIN validator is the more distinctive part: it can help identify the issuing details associated with a card number’s opening digits. That is useful when checking what kind of card you are dealing with, but it should not be confused with checking your available balance, validating a transaction, or replacing your bank’s own app.
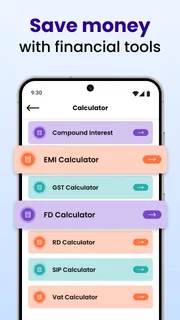
I would not install it expecting a full personal finance dashboard. There is no reason to treat it as a budgeting tool, a banking account, or a universal contactless payment replacement. Its purpose is narrower and more practical. If you have ever had to distinguish several debit and credit cards, check a card’s issuer information, or investigate whether a card supports a particular contactless interaction, the combination of tools makes more sense.
The current version is 3.0.5, and the app has built a visible audience: it has passed five million installs, with an average rating of 4.6 from around sixty-eight thousand ratings. Those figures suggest that the concept is reaching many Android users, although popularity alone does not guarantee that it will fit your particular wallet habits. I still recommend judging it by the specific task you need it to perform.
Free access is the important starting point
There is no upfront purchase price for downloading the app. That matters because the best way to judge a tool like this is through your own cards, phone, and everyday routine. NFC behavior can vary depending on the device and the card, so a free starting point is more useful than paying before you know whether the scanner is relevant to you.
The app also includes in-app purchases ranging from $0.99 to $99.99 per item. That is a very wide range, so I would treat the free installation as an opportunity to evaluate the core experience rather than assume every function is included. The presence of purchases means that “free” should be understood as free to install and try, not as a guarantee that every possible option is permanently available without payment.
For a casual user, that distinction is important. If you only want occasional card identification, the free experience may be enough to decide whether the app is useful. If you are considering paying for anything inside it, I would first confirm exactly what the purchase unlocks and whether that benefit solves a repeated problem for you. A one-time convenience can be worthwhile, but it is harder to justify a high-priced item for a task you perform only once.
Where the wallet idea helps
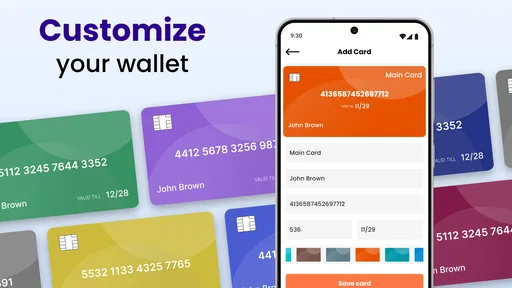
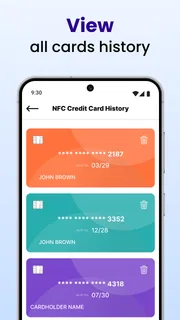
Keeping card-related information in one dedicated place can be more practical than scattering notes across a phone. In my experience, the advantage is not simply having a list of cards; it is reducing the small moments of uncertainty that happen when two cards look similar or when you need to remember which issuer is associated with a number. A specialized interface gives that information a clear purpose.
There is also a useful separation between identifying a card and using it. The BIN validator can help with the first task, while NFC scanning addresses a different kind of inspection. That makes the app more interesting than a plain digital wallet that focuses only on storing payment cards. The trade-off is that users must understand what each tool is for instead of expecting one button to handle every card-related need.
A realistic example would be a person carrying a personal debit card, a work card, and an older credit card with similar designs. Before adding or recording details, that person can use the identification tools to distinguish the cards and keep the information organized. Later, when checking a card number or investigating its issuing range, the BIN feature may be quicker than searching through old emails or paperwork. The value comes from the workflow, not from replacing the financial institution behind the card.
NFC is useful, but it is not magic
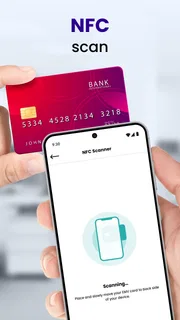
The NFC feature is the part most likely to create unrealistic expectations. A phone needs compatible NFC hardware, and the card or tag being scanned must expose information that the app can read. A failed scan does not automatically mean the card is defective, and a successful scan does not turn the app into a payment terminal or bank verification system.
I would use the scanner as an inspection aid, not as the final authority for an important financial decision. If you are checking whether a card works with a particular service, the service itself and the issuing bank remain more relevant than a general-purpose scanner. This is one of the app’s less obvious trade-offs: NFC can make card handling faster, but it also encourages users to ask what the scan actually proves.
A practical tip is to test the scanner with the card positioned steadily against the phone rather than moving it around quickly. If your phone has NFC controls, make sure the feature is enabled before blaming the app. Even then, results can depend on the physical card and device. That variability makes the scanner valuable for experimentation and quick checks, but less suitable as the only method for confirming compatibility.
What the BIN validator can and cannot tell you
The BIN validator is useful for interpreting the beginning of a payment card number. It can provide context about the card’s issuing identity and classification, which is handy when you are sorting cards or checking whether a card belongs to the expected issuer. This is especially helpful for people who manage multiple cards for household, travel, or business purposes.
However, a BIN check should not be treated as proof that a card is active, funded, genuine, or approved for a transaction. Those are different questions. The validator can support a screening process, but it cannot replace an authorization response from a bank or payment provider. That distinction is essential for anyone using the app for online selling, customer support, or fraud checks.
My recommended workflow is to use the BIN result as an early clue, then confirm anything important through the issuer or the payment service involved. This two-step approach prevents a common mistake: assuming that identifying a card’s range is the same as verifying the cardholder or the card’s current status.
Privacy and handling deserve common sense
Any app that deals with card-related information deserves cautious handling. I would avoid entering more information than the task requires, and I would not use a finance utility as a substitute for a bank’s protected account environment. The safest habit is to keep sensitive details limited, avoid sharing screenshots, and remove information you no longer need to keep.
This is not a criticism unique to this app; it is a sensible boundary for the whole category. A wallet-style interface can feel familiar, but familiarity does not mean it has the same protections or account controls as your bank. If you need transaction history, card locking, dispute management, or account recovery, your bank’s official application is the better destination.
I also recommend separating convenience from trust. The app may be convenient for organizing and inspecting card information, but important financial actions should still happen through the institution that issued the card. That division gives the app a sensible role without asking it to do work it was not designed to replace.
Where it compares well with ordinary alternatives
The usual alternative is to use a bank app for each card. That approach is stronger for balances, transactions, card controls, and account security, but it becomes awkward when you have cards from several institutions. Credit Card : Wallet & NFC is more appealing in that multi-card situation because it focuses on card identity and inspection rather than one bank relationship.
Another alternative is a general notes app. Notes are flexible, but they require manual structure and do not naturally connect card organization with NFC scanning or BIN checking. The dedicated approach is more convenient when your main goal is card-related work. On the other hand, a notes app may be preferable if you need complete control over the format or want to keep unrelated financial records together.
Dedicated payment wallets are different again. They are designed for making supported payments, while this app is better understood as a card utility. If your only goal is tapping your phone at a checkout, use the payment wallet supported by your device and financial institution. If your goal is identifying and organizing cards, this app has a clearer reason to exist.
Small workflows that reveal its value
One useful workflow is card inventory. I would start by separating active cards from expired or rarely used ones, then use the app’s identification tools to avoid mixing them up. This is more reliable than naming cards only by their appearance, especially when a bank changes its design or sends replacement cards that look nearly identical.
A second workflow is troubleshooting. If a contactless card is not behaving as expected, the NFC scanner can offer an initial check before you contact the issuer. It cannot diagnose every cause, but it may help you decide whether the phone can detect anything at all. That can save time by separating a possible phone or card-reading issue from a payment-account issue.
A third workflow is cautious card screening for a small online business or household administrator. The BIN validator can help organize incoming card information at an early stage, but it should never be the sole fraud decision. Pairing it with the payment processor’s own checks is the sensible approach. This is a clear example of the app’s strength and limitation appearing together: it can add context quickly, but it does not provide final authorization.
These workflows are more valuable than simply storing a card image. They use the app as a small toolkit: identify, inspect, organize, and then confirm through the proper financial channel. That is the mindset I would recommend to anyone installing it.
Who will get the most from it
I think the app is best for Android users who carry several payment cards, frequently need issuer information, or want a convenient place for card-related checks. It may also suit curious users who want to explore NFC interactions without immediately committing to a paid tool. The broad Everyone rating and low entry barrier make it approachable for ordinary household use.
It is less suitable for someone who wants a complete money-management system. There is no reason to choose it over a bank app for reviewing spending, transferring money, freezing a card, or managing account settings. It is also not the right choice if your main requirement is secure mobile payment at checkout; a dedicated payment wallet is more appropriate for that job.
People who rarely handle more than one card may find the extra tools unnecessary. In that case, the app could add another layer to a simple task that is already handled by the bank or phone wallet. The free installation makes trying it low-risk, but your time still has value, and a specialized tool is not automatically better than a simpler routine.
My final recommendation
After using it as a card-information utility, I see Credit Card : Wallet & NFC as a focused companion rather than a financial command center. Its combination of wallet organization, NFC scanning, and BIN validation gives it a distinct purpose, especially for people managing multiple cards. The free starting price is a genuine advantage, while the in-app purchase range means I would inspect each paid option carefully before spending.
The app earns its place when you need quick card identification and practical organization in one Android tool. Its limitations become clear when you expect bank-level account features, guaranteed NFC compatibility, or definitive fraud and payment verification. In those situations, your bank, payment processor, or device wallet is the stronger choice.
My advice is simple: install it if card inspection is a recurring problem, test the free experience with a non-critical use case, and keep its results in perspective. Use it to gather useful card context, not to replace the institution that controls the card. For the right user, that focused role makes it worthwhile; for everyone else, the usual bank and payment tools may be cleaner and more dependable.
Pros and Cons
Pros
- Stores multiple cards and payment details in one convenient place.
- NFC support enables quick contactless payments on compatible devices.
- Clean interface makes card management easy for most users.
- Useful reminders can help track payment dates and card information.
- Reduces the need to carry physical cards in your everyday wallet.
Cons
- NFC features depend on phone hardware
- region
- and supported payment terminals.
- Some banks or cards may not be compatible with the app.
- Sensitive financial data requires strong security and device protection.
- Certain features may be limited behind in-app purchases or subscriptions.
- The app may not replace official banking apps for full account management.
Advertisements
Other Releases by Galaxy studio apps


How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Credit Card : Wallet & NFCGalaxy studio apps | 4.6 | 5,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |

Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Credit Card: Wallet & NFC used for?
Credit Card: Wallet & NFC is designed to help you organize and manage payment card information from your mobile device. Depending on your phone, region, and supported services, it may provide tools for storing card details, viewing wallet-related information, or using NFC features. It should not automatically be assumed to replace your bank’s official app or a physical card, so check the available functions carefully before relying on it for payments.
Can I make contactless payments with Credit Card: Wallet & NFC?
Contactless payment support depends on your smartphone’s NFC hardware, operating system, country, bank, card issuer, and compatibility with the payment service being used. Installing the app alone does not guarantee that tap-to-pay transactions will work. During testing, users should confirm that NFC is enabled, the device meets security requirements, and their bank or payment provider supports the selected wallet before attempting to pay in stores.
Is it safe to store my credit card information in this app?
Users should treat any wallet or card-management application as sensitive because it may handle financial information. Before entering card details, review the app’s privacy policy, requested permissions, developer information, and security options. Avoid sharing PINs, passwords, or one-time verification codes inside unfamiliar forms. For the safest experience, use official banking or payment services whenever possible and enable a strong device lock, biometric protection, and transaction notifications.
Does Credit Card: Wallet & NFC work with every bank and card?
No application can guarantee compatibility with every bank, card network, country, or payment terminal. Support may vary according to the card issuer, NFC standards, device model, Android or iOS version, and local regulations. A card might be visible in the app but still unavailable for contactless payments. Before downloading, check the current compatibility information and confirm with your bank if your specific card is supported.
Is Credit Card: Wallet & NFC free to download, and are there extra costs?
The app may be available to download without an upfront charge, but users should inspect the store listing for advertisements, optional subscriptions, premium tools, or in-app purchases. Your bank or payment provider may also apply separate fees, limits, or currency-conversion charges when a transaction is made. Read the pricing details carefully before activating any paid feature, and remember that the app itself does not remove normal card or banking fees.
Advertisements

Download Credit Card : Wallet & NFC
About This Listing
- Last Checked
- Nov 6, 2026
- Version Reviewed
- 3.0.5
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.