


Cherry: The Smarter Way to Pay
Cherry Technologies, Inc.
Advertisements
App Specs
- Version
- 1.3.0
- Updated
- Nov 6, 2026
- Android Version
- 7.0
- Installs
- 100,000+
- Developer
- Cherry Technologies, Inc.
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
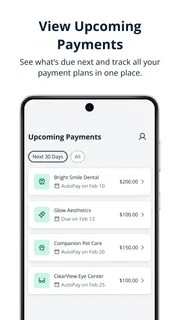
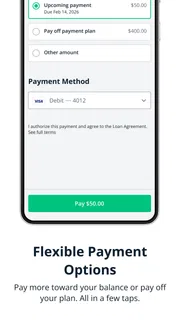
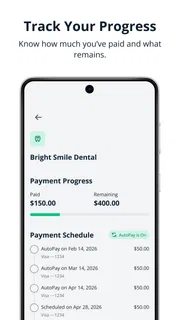
Our Review
 Analysis byUnlimiteds
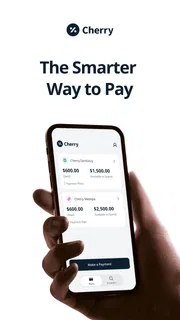
Cherry: The Smarter Way to Pay is a finance app from Cherry Technologies, Inc. that focuses on helping people manage payment plans and pay according to a schedule that suits them. I approached it as a first-time user would: install it, understand what it is meant to do, look for the first useful action, and then decide whether it deserves a regular place on my phone.
My first impression is that Cherry is best understood as a payment-plan companion rather than a complete personal-finance command center. That distinction matters. If you want detailed budgeting, investment tracking, bank-account analysis, or a full record of every transaction, this is probably not the tool I would choose first. If your main concern is keeping an organized view of planned payments and handling them on time, its narrower purpose is more appealing.
The app is free, available for Everyone, and currently listed at version 1.3.0. It has passed the early discovery stage with over one hundred thousand installs and an average rating of 4.5 from roughly one hundred thirty ratings. Those figures suggest that Cherry has found a useful audience, although the relatively small review pool also tells me to judge it by its practical workflow rather than treating the rating as a guarantee.
Getting from installation to a useful payment routine
I’d treat the first setup as a quiet, deliberate task rather than something to squeeze into a spare minute: check each plan against its original terms, then make sure its label will still make sense when you’re scanning quickly. Once that foundation is clear, the next section looks at how a simple review habit can turn the plan list into a dependable part of your routine.
What I would expect before opening it
The store summary presents Cherry as a way to manage plans and pay on a schedule. That wording sets a helpful expectation: the central experience should be about staying aware of agreed payment timing, not about making every part of your financial life visible in one place. I would install it when I had a specific payment arrangement to organize, rather than downloading it simply because I wanted a general money app.
That focused approach is one of its strengths. Many finance apps ask users to connect several accounts, categorize spending, and build a complete picture before they become useful. Cherry appears aimed at a more immediate problem: keeping a plan understandable and acting on it when a payment is due. For someone who tends to lose track of dates or forgets which installment comes next, that focus can be more valuable than a long list of analytical tools.
At the same time, I would not expect the app to replace a bank app, card statement, or household budget. A payment-plan tool can help you follow an arrangement, but it does not automatically make the underlying commitment affordable. I would still check the original terms and keep enough money available before relying on any schedule inside the app.
The first setup should be treated as a fact-checking step
For a new user, the most important part of setup is not speed; it is accuracy. I would enter or review each plan carefully, paying particular attention to the total obligation, the timing of payments, and any details that affect when money needs to be ready. A schedule is only useful when it reflects the real agreement.
My practical advice is to have the relevant confirmation email, receipt, or account information beside you while setting things up. That avoids the common mistake of creating a convenient-looking schedule from memory. If a payment date is entered incorrectly, the app may make the plan feel organized while still leaving you exposed to a missed deadline.
I would also begin with one active plan instead of trying to reconstruct every financial commitment at once. This gives a first-time user a clean test: can I understand the plan, recognize the next action, and complete it without hesitation? Once that routine feels clear, adding other plans becomes less intimidating and less likely to produce a cluttered or confusing overview.
Another useful habit is to give each plan a recognizable description. “Monthly payment” is easy to confuse with another monthly payment. A label that identifies what the plan relates to makes the list more useful when you are checking it quickly in the middle of a busy day. This is a small organizational choice, but it can make the difference between a schedule that is merely stored and one that is actually used.
The first successful action is more important than a perfect dashboard
I would define success on the first visit very simply: open a plan, understand what is due next, and complete the appropriate payment action on schedule. That is a more realistic test than spending time exploring every screen. If Cherry helps me move from uncertainty to a clear next step, it has already done something worthwhile.
For example, imagine I am preparing for a payment after receiving a reminder during a crowded workweek. Instead of searching through messages or trying to remember the last installment, I would open Cherry, check the plan, confirm the upcoming obligation, and arrange the payment while I still have time to resolve any problem. The value is not excitement; it is reducing the number of mental steps between remembering and acting.
I would make a personal rule to check the plan before the due date rather than waiting until the last possible moment. That gives me time to verify the amount, check the available balance through the appropriate financial channel, and deal with a declined transaction or incorrect detail without turning it into an emergency. Cherry can support that habit, but the habit still belongs to the user.
A second practical workflow is to use the app during a weekly money check-in. I would review upcoming plan obligations alongside my regular bank balance and other bills. This prevents the common mistake of treating an installment as an isolated payment when it is actually part of a larger month. The app can organize the plan; a broader review is still needed to decide whether the timing works with everything else.
Where first-time users may become confused
The phrase “pay on your schedule” can be read too broadly. I would not interpret it as permission to change any payment terms freely or as a promise that every plan can be adjusted in any way I choose. A schedule shown in an app should be compared with the actual agreement. If the original provider has rules about dates, amounts, or payment methods, those rules remain important.
I would also separate three ideas that are easy to blend together: viewing a plan, preparing for a payment, and successfully completing a payment. Seeing a due item in Cherry does not by itself prove that the payment has gone through. After taking action, I would look for the appropriate confirmation and keep the relevant record. That extra check is especially important when the payment is time-sensitive.
Another possible source of friction is expecting a finance app to explain every part of a financial decision. Cherry can help make a plan easier to follow, but it cannot tell me whether taking on that plan was wise for my income, whether another option would cost less, or how it fits into long-term goals. I would use it as an execution and organization tool, not as a substitute for reading terms or seeking financial advice when the decision is complicated.
People who manage several plans may also need a consistent naming and checking system. Without one, even a clean list can become difficult to scan. I would group my routine mentally by timing, then confirm each plan individually instead of assuming that similar-looking entries have identical conditions. This is a non-obvious trade-off: the app may reduce date-related stress, but it cannot remove the attention needed to distinguish one obligation from another.
Who gets the most value from Cherry
I think Cherry is most suitable for someone who has a defined payment plan and wants a simpler way to keep that commitment visible. It may be particularly helpful for people who are comfortable using a phone for financial tasks but do not want to build a large spreadsheet or maintain a complicated budgeting system.
It also makes sense for a user who prefers a narrow tool with a clear job. If my main problem is remembering which payment comes next, I would rather have a focused workflow than a dashboard filled with spending categories I never review. The free price removes an obvious barrier to trying it, and the Everyone content rating makes it approachable for a broad audience.
I would be more cautious if I needed advanced household budgeting, shared financial planning, detailed reports, or a complete account aggregation service. In those situations, a traditional budgeting app, a spreadsheet, or the tools provided by my bank may be a better match. Cherry’s value comes from its payment-plan focus; that same focus limits how much it can do outside that job.
How it compares with familiar alternatives
The usual alternative is a calendar reminder. A calendar is excellent for remembering a date, but it does not necessarily give that date enough context. A reminder may say “payment due” without showing which plan it belongs to or what action should follow. Cherry is more useful when the user needs a payment-oriented view rather than a generic alert.
A spreadsheet offers more flexibility. I can add columns for totals, notes, income, and other bills, then design a system around my own preferences. The downside is maintenance. A spreadsheet depends on disciplined updates, and it can become unreliable when I am busy. Cherry is preferable when I want less manual structure and a more direct path to reviewing a plan.
A bank app is usually the strongest option for checking actual account activity and confirming completed transactions. It may also provide its own scheduled-payment tools. I would use that channel as the final source for balance and transaction confirmation, while using Cherry to keep the payment-plan workflow easier to follow. The two approaches can complement each other rather than compete.
Compared with a broad budgeting app, Cherry should appeal to someone who values immediacy over analysis. A budgeting platform may help answer whether a payment fits into a monthly spending plan. Cherry is better suited to answering what plan I am managing and what payment action I need to address next. Choosing between them depends on whether the problem is planning the whole budget or staying on top of a particular arrangement.
Small habits that make the app more dependable
I would use a three-check routine: verify the plan details, verify the next scheduled action, and verify the result after paying. It sounds basic, but it prevents three different errors that are often treated as one. A correct plan can still be paired with a missed action, and a completed action can still be recorded incorrectly if it is not checked afterward.
I would also avoid adding a plan while distracted. Entering financial details on a crowded train or between meetings creates unnecessary risk. A quiet setup session is more valuable than a fast one, because the purpose of the app is to reduce later confusion. Once the plan is correct, brief checks should be much easier.
For people with irregular income, I would review upcoming obligations earlier than someone with a predictable pay cycle. A schedule can show when a payment is expected, but it cannot create funds that are not available. In that situation, Cherry is useful as an early-warning list, while the user still needs a separate cash-flow plan and enough time to contact the relevant provider if a problem is likely.
For people who share household responsibilities, I would agree on who checks the plan and who confirms the payment. Even when only one person uses the app, unclear responsibility can lead to duplicate actions or no action at all. The app can make the plan visible, but a household still needs a simple human agreement around it.
What the current version means for a cautious user
Cherry is relatively early in its product life, with a release date of February 20, 2026 and a current version of 1.3.0. I see that as a reason to use it deliberately rather than dismissing it or trusting it blindly. Early versions can improve quickly, but users should still form their own backup habits for important financial commitments.
My backup would be straightforward: retain the original plan information, keep confirmation records, and use the relevant financial account to confirm that a payment was actually processed. This is not a criticism unique to Cherry; it is sensible whenever an app sits between a user and a time-sensitive financial obligation. Convenience should reduce effort, not remove verification.
The Android requirement is listed as version 7.0 or later, which makes the app accessible to people using older supported devices. I would still keep the operating system and the app updated when updates are available, especially for a finance-related tool. A current installation is generally easier to troubleshoot and more sensible for handling personal financial information.
My recommendation after using it as a newcomer
I would recommend Cherry to a friend who has a clear payment-plan problem and wants a focused way to stay organized. I would tell that friend to begin with one plan, compare every detail with the original agreement, and make the first check before the due date. That path gives the app a fair test without asking the user to redesign their entire financial life.
I would not recommend it as the only finance app for someone who wants a full budget, investment overview, detailed spending analysis, or comprehensive household accounting. A bank app, spreadsheet, or broader budgeting service may be stronger for those needs. Cherry works best beside those tools when the specific challenge is following scheduled payments without relying on memory.
My overall view is positive but focused. The app’s strongest quality is the way it turns a potentially vague obligation into something I can review and act on. Its main limitation is equally clear: organizing a payment plan is not the same as judging affordability, changing contract terms, or confirming every financial detail. Used with that understanding, Cherry: The Smarter Way to Pay is a practical free finance app for first-time users who want a calmer, more deliberate route from “I need to remember this” to “I know what I need to do next.”
Pros and Cons
Pros
- Splits purchases into manageable installments with clear repayment schedules.
- Useful for shoppers who need short-term payment flexibility at checkout.
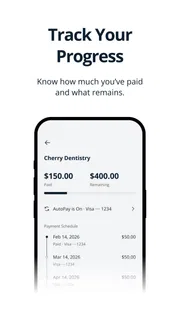
- Application helps track upcoming payments and outstanding balances.
- Digital signup and approval process can be quicker than traditional credit applications.
- May offer access to partner-store promotions or exclusive shopping deals.
Cons
- Eligibility and spending limits can vary based on personal financial information.
- Late or missed payments may lead to fees or affect your credit profile.
- Not every retailer or purchase may qualify for Cherry financing.
- Using installments can make expensive purchases feel easier to overspend on.
- Terms
- fees
- and available plans should be reviewed carefully before accepting.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Cherry: The Smarter Way to PayCherry Technologies, Inc. | 4.5 | 100,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Cherry: The Smarter Way to Pay?
Cherry is a healthcare financing and payment platform that allows eligible patients to divide the cost of certain medical, dental, cosmetic, and wellness treatments into manageable monthly payments. Instead of paying the entire treatment fee upfront, you can apply for a financing option through a participating provider. Available plans, terms, and approval decisions depend on your application and the provider’s participation.
How does Cherry financing work?
To use Cherry, you generally begin through a healthcare provider that offers Cherry as a payment option. You submit an application, review the financing plans you qualify for, and select an option that fits your budget if approved. The provider then receives payment according to the agreement, while you repay the financed amount over the selected term. Read all disclosures carefully before accepting.
Does using Cherry guarantee approval, and will it affect my credit?
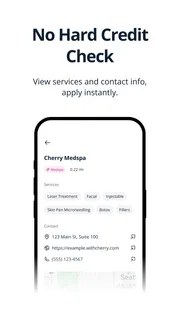
Cherry does not guarantee that every applicant will be approved. Eligibility can depend on factors such as application information, credit history, income, and the specific financing program available through the provider. The effect on your credit may vary depending on the type of application and review performed. Before applying, check Cherry’s current disclosures to understand whether a credit inquiry may occur.
Are there fees or interest charges when paying with Cherry?
The total cost of using Cherry depends on the financing offer you receive. Some plans may include promotional terms, interest, administrative charges, or other costs, while others may have different pricing conditions. Do not assume that every plan is interest-free. Before confirming treatment financing, review the annual percentage rate, payment amount, number of payments, late-payment terms, and total repayment amount.
Can I use Cherry for any healthcare treatment or pay early?
Cherry is not necessarily available for every treatment, provider, or location. The services you can finance depend on the participating clinic and the options shown during your application. If you are approved, check the agreement for rules about changing or canceling treatment, refunds, and early repayment. Paying early may be possible, but any applicable terms should be confirmed directly in your financing documents.
Advertisements

Download Cherry: The Smarter Way to Pay
About This Listing
- Last Checked
- Nov 6, 2026
- Version Reviewed
- 1.3.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.