

Wallet - Digital Card Wallet
Advertisements
App Specs
- Version
- 6.2.5
- Updated
- Nov 7, 2026
- Android Version
- 7.0
- Installs
- 1,000,000+
- Developer
- Wallet Assistant
- Category
- Tools
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
I usually treat digital wallet apps with a little more caution than ordinary utility apps. A tool that stores payment-card details, loyalty cards, and scannable codes sits close to everyday identity and spending habits, so convenience is only half the decision. After using Wallet - Digital Card Wallet, I found its appeal easy to understand: it gives scattered cards one place to live, while keeping the experience focused on quick access rather than turning into a full banking app.
This is a free tools app from Wallet Assistant, intended for Everyone and available on Android devices running version 7.0 or later. It has reached over a million installs and holds a 4.7 average from around 23 thousand ratings, which suggests that the basic idea is working for a substantial audience. The current release is version 6.2.5, and the app was released on August 10, 2023. Those details matter less than how it behaves in the small moments when you are standing at a checkout, opening a loyalty barcode, or trying to find the right card before a scanner times out.
Trust starts with what the app actually needs to do
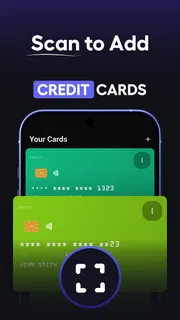
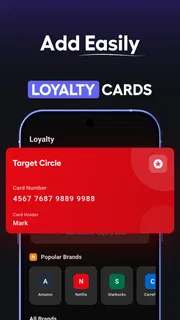
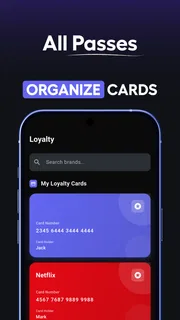
The first useful distinction is between a card organizer and a financial account manager. This app is designed to collect credit cards, barcodes, and loyalty cards in one place. I would not approach it as a replacement for a bank application, a payment service, or the secure payment wallet built into a phone. Its value is organization: instead of searching through a physical wallet or several screenshots, you open one app and select the item you need.
That narrow purpose is a positive starting point. A focused card wallet is easier to understand than an application that combines payments, budgeting, shopping, rewards, identity documents, and financial transfers. At the same time, the word “wallet” can create expectations that the app will handle tap-to-pay transactions or directly connect to a bank. I would not assume that. The safest way to use it is as a convenient display and storage tool for cards and barcodes, while continuing to use official banking or payment apps for transactions that require them.
My trust assessment therefore begins with restraint. I would add a loyalty barcode or a card I need at stores before I consider placing highly sensitive information there. That gradual approach lets you see whether the app fits your routine, whether the card images or codes are easy to retrieve, and whether the controls feel clear enough for your comfort level.
The developer is listed as Wallet Assistant, and the app is free to download. Optional in-app purchases range from $9.99 to $69.99 per item, so I would pay attention to any upgrade screen before confirming anything. A free starting point is helpful, but it does not automatically mean every capability is included without charge. I prefer to test the basic workflow first and decide whether the paid options solve a real problem rather than paying simply because the app looks useful.
What I checked when organizing cards
Adding a card is most useful when I think about the moment I will need it, not just the card itself. For example, I would group supermarket loyalty cards, pharmacy cards, and membership barcodes according to the places where I use them. That makes the wallet practical under pressure. If every item is added in random order, the app can become a digital version of an overstuffed physical wallet.
I also recommend using clear names that make sense at a glance. “Coffee shop” or “health store” is faster than trying to recognize a small logo while a queue is waiting. If the app lets you add notes or labels during your workflow, keep them short and useful, such as the branch name or the type of reward. The goal is to reduce decisions at the checkout, not create another catalog that needs maintenance.
One non-obvious trade-off is that centralizing cards improves access but increases the importance of the phone itself. If your battery is empty, the screen is damaged, or you cannot unlock the device, the digital collection is less useful than a physical backup. I would keep a payment card or essential membership card available outside the app, especially for travel, long shopping trips, or places where charging is difficult.
Where the app feels more useful than screenshots
Many people already save loyalty cards as screenshots. That works once, but it becomes awkward when the image is buried among travel tickets, receipts, and photos. A dedicated wallet gives each card a deliberate place and makes the collection easier to scan mentally. I found that difference most valuable for cards I use occasionally, because those are the ones I am least likely to remember where I saved.
There is also a practical advantage over carrying every physical loyalty card. A phone-based collection reduces clutter and makes it easier to leave rarely used cards at home. However, the app should be judged by retrieval speed, not by how many cards it can hold. If opening the correct item takes longer than pulling a plastic card from a simple wallet, the organizational benefit has disappeared.
For that reason, I would spend a few minutes arranging the collection immediately after adding several items. Put frequent cards where your eye naturally finds them, remove duplicates, and avoid adding old cards just because you might use them someday. A smaller, maintained wallet is usually more dependable than a complete archive.
Controls, sensitive moments, and how much choice you keep
With any app that may contain card details, I look for visible user choices rather than making assumptions about invisible protection. The important questions are practical: Can I decide what to add? Can I remove an item when I no longer need it? Can I review the app’s settings and purchase prompts before committing? Can I choose not to place a particularly sensitive card inside it? These choices are more meaningful to me than broad claims about security that I cannot verify from ordinary use.
I would begin with loyalty cards and barcodes because they offer a low-risk test of the workflow. Once I understand how items are displayed and removed, I can decide whether adding a credit card is appropriate for my own situation. That decision should depend on what information the app asks me to enter, how comfortable I am with storing it, and whether I need the convenience often enough to justify the trade-off.
A barcode is not the same thing as a payment credential. A loyalty code generally identifies an account at a retailer, while a credit-card number can be much more sensitive. Treating both as interchangeable simply because they appear in the same wallet would be careless. I would use the app’s organizing strength for low-risk cards first and reserve payment activity itself for the official channel intended for that purpose.
The moments when caution matters most
Imagine I am at a supermarket with a full basket and the cashier is ready for the loyalty scan. I open the wallet, search for the store, display the barcode, and let the scanner read it. That is the ideal everyday scenario: the app saves me from carrying another card and avoids hunting through a photo gallery. But if the screen brightness is too low, the barcode is cropped, or the phone is offline and the item does not appear as expected, the convenience can turn into friction. I would keep a backup method for cards that affect discounts or access.
A second scenario is travel. I might collect a hotel membership card, an airline-related loyalty code, and a rental-company barcode in one place. That reduces paper and makes the set easier to locate. Yet travel is also when battery, connectivity, and device loss become more serious concerns. I would not make the app my only record of anything important. A small offline backup, a physical card, or an official account application can prevent one technical problem from disrupting a trip.
Another sensitive moment comes when lending a phone to someone else. A friend may need to scan a shared household loyalty card, but handing over an unlocked device can expose other cards visible nearby. I would open the exact item first and avoid leaving the wallet on a broad overview screen. This is a simple habit, but it reflects an important principle: privacy is shaped not only by app settings, but also by how the phone is handled in public.
I would also review the collection after replacing a card, changing a loyalty account, or ending a membership. Old barcodes and expired payment details create confusion and can expose information that no longer serves a purpose. Deleting them is not glamorous, but it is one of the most useful maintenance tasks in any digital organizer.
Permissions and data choices deserve a deliberate review
I do not infer trust from the app’s category or from its rating alone. Before adding sensitive material, I would inspect the permission prompts shown on my device and read the privacy information available through the app’s store page and settings. The relevant question is whether each requested access makes sense for the action I am trying to perform. If a prompt feels unrelated to adding or displaying a card, I would pause rather than approve it automatically.
The same caution applies to account controls. I would look for ways to manage stored items, sign out if an account is involved, and understand what happens when the app is removed from the phone. I would not assume that uninstalling an application erases every copy of information associated with it. If the app presents a deletion or account-management choice, I would use it when appropriate and keep my own record of which cards I added.
Purchase screens deserve the same attention. Since the app is free with optional purchases, I would read the wording around any premium feature and confirm the amount before accepting. A useful test is to ask whether the paid capability changes a daily problem I actually have. If I only need a handful of loyalty cards, the free experience may be enough; if the upgrade is presented as a requirement for a feature I expected to be basic, I would reconsider whether this is the right wallet for me.
How it compares with the usual alternatives
Compared with a physical wallet, this app is lighter and easier to reorganize, but it depends on a charged and accessible phone. Compared with a photo gallery, it offers a more intentional home for cards and should make retrieval less chaotic, though the benefit depends on how carefully I label and arrange items. Compared with a bank or phone payment wallet, it is better understood as a card organizer rather than a complete payment system.
That distinction makes the app a good companion rather than a universal replacement. I would choose it when my main irritation is carrying loyalty cards or searching for barcodes. I would choose an official banking or system payment wallet when my priority is contactless payment, transaction history, bank authentication, or the strongest integration with the phone’s payment hardware. I would choose physical cards when reliability matters more than reducing wallet size.
There is no single winner because these tools solve different problems. The mistake would be expecting a barcode organizer to provide every control of a financial service. Used within its actual role, Wallet - Digital Card Wallet is easier to evaluate and less likely to create false confidence.
Who should use it, and who should skip it
I think it suits people who carry many loyalty cards, regularly use store barcodes, or want a cleaner alternative to screenshots. It is also useful for households that share several membership cards, provided the owner is comfortable with the phone being used as the access point. Someone who shops at many different retailers may notice the biggest organizational improvement because the app turns a scattered collection into one routine.
I would be more cautious if you rarely use loyalty programs, already have a well-organized system wallet, or dislike entering card information into third-party tools. There is little reason to add another layer if your phone’s existing wallet already handles everything you need. People who require guaranteed access without a phone should also keep physical alternatives instead of relying on this app alone.
Accessibility and speed should be part of the decision too. If you have difficulty reading small card images, navigating a list quickly, or keeping a phone screen visible under bright lights, test the display before moving essential cards into the app. A tool can be well designed for one person and inconvenient for another because the checkout environment is not forgiving.
My cautious verdict after using it
The strongest reason to install this app is simple organization, not financial management. It can make loyalty cards and barcodes easier to find, reduce the physical clutter in a wallet, and replace an unreliable pile of screenshots with a more deliberate collection. The free entry point makes it reasonable to test with low-sensitivity cards first, while the Everyone rating keeps it approachable for a broad audience.
My recommendation comes with boundaries. I would not treat the app as proof that stored payment information is risk-free, and I would not make it the only way to access cards during travel or emergencies. I would review permissions and account choices directly on my device, read purchase prompts carefully, remove outdated cards, and keep a backup for anything essential.
At a 4.7 average and with over a million installs, it is clearly attracting people who like the basic concept. My own conclusion is more specific: it is worth trying if your problem is card clutter and barcode retrieval. It is not the right choice if you want a full bank-connected payment experience or if you are uncomfortable storing sensitive details in a separate utility. Used thoughtfully, Wallet - Digital Card Wallet is a practical organizer; used as a substitute for every other wallet, it asks for more trust and reliability than I would give it.
Pros and Cons
Pros
- Keeps loyalty cards organized in one convenient digital wallet.
- Reduces the need to carry bulky physical cards when shopping.
- Quickly displays card details at checkout when needed.
- Simple interface makes adding and viewing cards easy.
- Useful for storing cards from different retailers in one place.
Cons
- Some cards may not be supported or scan correctly.
- Requires phone access whenever you need to show a card.
- Digital cards may not work in stores with outdated scanners.
- Losing phone access can also mean losing access to stored cards.
- Some features may depend on device compatibility or app permissions.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Wallet - Digital Card WalletWallet Assistant | 4.7 | 1,000,000+ | Free |
 GoogleGoogle LLC | 4.0 | 10,000,000,000+ | Free |
 Google Play StoreGoogle LLC | 4.9 | 10,000,000,000+ | Free |
 Gboard - the Google KeyboardGoogle LLC | 4.5 | 10,000,000,000+ | Free |
Alternatives Worth Trying


More Tools Reviews
View All More Tools Reviews


Frequently Asked Questions
What is Wallet - Digital Card Wallet used for?
Wallet - Digital Card Wallet is designed to keep digital versions of your loyalty cards, membership cards, coupons, tickets, and similar passes in one convenient place. Instead of carrying a physical wallet full of plastic cards, you can open the app and display the relevant barcode or QR code when shopping or checking in. Its usefulness depends on which card and pass formats are supported on your device.
Can Wallet - Digital Card Wallet store all types of cards and passes?
The app can be useful for many loyalty, rewards, membership, and event cards, but it may not support every card automatically. Compatibility can depend on the barcode type, the merchant or organization, and whether a pass is available in a supported digital format. Before deleting physical cards, check that the businesses you use can scan the codes displayed by the app.
Does Wallet - Digital Card Wallet work without an internet connection?
Many saved cards can generally be displayed offline once their information has been added to the app, which is helpful in stores with weak reception or when traveling. However, features such as downloading new passes, synchronizing information, receiving updates, or accessing online content may require an internet connection. It is sensible to open important cards in advance before going somewhere.
Is Wallet - Digital Card Wallet safe for storing personal information?
A digital card wallet may contain identifying details, membership numbers, barcodes, and other information connected to your accounts. You should review the app’s permissions, privacy policy, backup options, and available security protections before adding sensitive passes. Use a strong device lock, keep your operating system updated, and avoid sharing screenshots of cards that contain account numbers or scannable codes.
Is Wallet - Digital Card Wallet free to download and use?
The app may be available to download without an upfront charge, but the exact business model can vary by platform and version. Some features may include advertisements, optional purchases, subscriptions, or limitations on the number of cards you can save. Check the Google Play Store or Apple App Store listing for the current price, in-app purchase details, and supported device requirements before installing.
Advertisements

Download Wallet - Digital Card Wallet
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 6.2.5
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.