


Afterpay: Pay over time
Afterpay
Advertisements
App Specs
- Version
- 1.142.0
- Updated
- Nov 5, 2026
- Android Version
- 7.0
- Installs
- 10,000,000+
- Developer
- Afterpay
- Category
- Shopping
- Content Rating
- Mature 17+
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
I find Afterpay most useful at a particular point in a shopping trip: I’ve chosen something I genuinely need, the full cost is awkward to pay all at once, and I want to decide calmly whether splitting the bill fits my budget. That makes it different from a coupon app or a general shopping marketplace. It is a free shopping app from Afterpay, built around paying for a purchase over time rather than finding the lowest price. The app has a 4.0 average from around 167,000 ratings and more than 10 million installs, so it is a familiar option for people who already shop with retailers that accept it.
Start with the purchase, not the payment plan
Before I open the app, I try to settle two questions: do I need the item now, and could I cover its full cost without borrowing? If the answer to the second question is yes but the timing is inconvenient, splitting payments may help with cash flow. If I would need to stretch my budget even with installments, I take that as a reason to wait rather than a reason to buy.
That distinction matters because a smaller amount due today can make a purchase feel more affordable than it really is. I recommend deciding on a spending limit before browsing stores, then checking whether the total still makes sense after delivery costs and any other charges shown during checkout. The payment schedule should fit around your existing bills, not compete with them.
From browsing to checkout
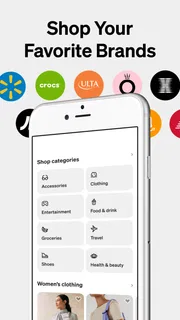
After setting up an account, I can browse participating retailers in the app or begin with a retailer I already have in mind. The practical first step is to check whether the shop accepts Afterpay before spending time choosing an item. If it does, I select the payment option at checkout and review the amount due now and the future installments before confirming the order.
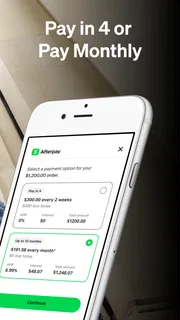
The app’s familiar installment setup divides a purchase into four payments scheduled every two weeks. I treat the checkout screen as the point to pause and verify the total, the dates and the payment method, rather than tapping through because the first installment looks manageable. A quick note in my calendar or budget app can make those upcoming dates easier to keep in view, especially when several household expenses fall close together.
For instance, imagine replacing a worn everyday item shortly before payday. If the retailer offers Afterpay and the full purchase fits your budget, the split can make the timing less uncomfortable. But if another installment is already due around the same time as rent, utilities or a planned grocery shop, the sensible move may be to wait, choose a less expensive item or pay another way.
Where the handoffs can feel less smooth
There are two separate parts to the experience: the retailer handles the goods, order details and delivery, while Afterpay handles the payment arrangement. That division is worth remembering if something goes wrong. A question about an item, shipping or an order change usually starts with the shop; a question about the scheduled payments belongs with the payment service. Keeping the order confirmation and payment details together can save time when you need to work out which side to contact.
There is also a small but important handoff at checkout: a retailer has to support Afterpay for the option to appear. So I would not build a shopping plan around the app until I have checked the actual store and basket. The item you want may be available from a shop that does not offer this payment method, and the app cannot make that retailer part of the process.
What I would check before committing
The most useful habit is to look at the entire schedule, not just the first payment. Add the future dates to the same budget view where you track bills, and consider other purchases already split into installments. Several individually manageable payments can become a crowded month when they overlap. I also avoid using a new installment plan to cover routine spending that I could not otherwise afford; that can turn a short-term convenience into a recurring squeeze.
Paying on time is central to the appeal, but missing a scheduled payment can bring late fees. I would therefore check that the payment method and account details are current and that enough money will be available on each due date. If your income varies, or you are unsure when funds will arrive, a payment plan with fixed dates may be less comfortable than paying in full or waiting until the timing is clearer.
Who benefits, and who may prefer another route
I see the strongest fit for someone who already has a planned purchase, has a reliable way to meet the scheduled payments, and wants to spread the timing without turning shopping into an ongoing habit. It can also be useful when replacing an essential item cannot wait for the next pay cycle, provided the installments remain affordable alongside other commitments.
It is less suitable for anyone trying to control impulse spending, anyone who regularly loses track of due dates, or anyone whose budget has no room for the later payments. Paying in full gives a clearer picture of what you can afford and avoids the mental bookkeeping of several due dates. A credit card or another payment option may suit a shopper better if they already understand its terms and can manage it responsibly; the right comparison is the total cost and the effect on your budget, not simply which option makes checkout feel easiest.
For a lower-cost purchase, saving up and buying later may be the cleanest alternative. For a time-sensitive purchase, installments may help with timing, but they do not reduce the price of the item. I keep that difference in mind: a payment schedule changes when money leaves my account, not whether I can ultimately afford the purchase.
What is Afterpay?
Picture this: You're browsing your favorite online store, and you stumble upon that must-have item. But, alas! Your wallet isn't quite keeping up with your desires. Enter Afterpay. This nifty app lets you purchase items immediately and split the payment into four equal installments, due every two weeks. And the best part? No interest or hidden fees if you pay on time!
How Does It Work?
Using Afterpay is as easy as pie. First, download the app on your Android or iOS device. Once you’ve set up your account, browse through the multitude of partner retailers. When you’re ready to check out, simply choose Afterpay as your payment method. Your total bill gets divided into four manageable chunks, making shopping less of a financial burden.
Now, a word to the wise: while the app doesn’t charge interest, it does impose late fees if you miss a payment. So, a little planning goes a long way in ensuring you enjoy the benefits without any hiccups.
Why I Love It
Let me tell you why I’ve grown fond of Afterpay. It’s the sheer convenience and the empowerment it offers to shop without the immediate financial strain. During the holiday season or when big sales hit, this app is a godsend. Plus, it helps me budget my expenses better by spreading payments over a period, making it easier to manage my monthly finances.
Things to Keep in Mind
While the app is a fantastic tool for managing purchases, it’s important to stay mindful of your spending habits. It’s easy to get carried away, thinking you can pay later. But remember, those payments will come knocking every two weeks. So, shop smart, my friend!
Moreover, not all stores accept Afterpay, so a quick check on their partner retailers list is always a good idea before you get your hopes up on that new gadget or outfit.
The Final Word
In conclusion, Afterpay - Buy Now, Pay Later is a revolutionary tool for anyone looking to make shopping more affordable and flexible. It’s user-friendly, efficient, and a real game-changer in the world of digital payments. Just remember, with great power (of spending) comes great responsibility. Happy shopping!
How I decide whether it fits a real shopping day
My routine is to make the shopping decision before I think about the payment method. Say I notice that my work shoes are wearing out while getting ready in the morning. I would first pick a sensible replacement and check the final basket total, then see whether the retailer offers Afterpay. If the split schedule sits comfortably beside my regular bills, the app can help me handle the timing. If it only works by assuming I will have spare money later, I would leave the purchase for another week or choose a cheaper pair.
This approach also helps during sales. A discount can make a planned purchase worthwhile, but a sale is not a reason by itself to create several future payment dates. I compare the discounted total with what I would otherwise spend, and I check that the payment plan does not make me add extra items simply because each one seems like a small installment. The useful outcome is getting the item I intended to buy while keeping the rest of the month predictable.
Small habits that make the schedule easier to manage
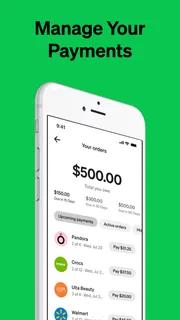
One practical tip is to record each installment as soon as the purchase is confirmed, rather than relying on memory or waiting for a reminder. I would include the retailer, the total and the due dates in the same place I track other commitments. This is especially helpful if you use installment payments for more than one purchase: looking at each plan separately can hide how many payments will land in the same week.
I also try not to make a new purchase based on money that is already earmarked for an upcoming installment. Treating future payments like bills, rather than optional expenses, gives a more honest view of what is available to spend. If the numbers are tight, I would rather postpone a nonessential order than depend on a later payday arriving exactly as expected.
Questions to settle before placing an order
A common point of uncertainty is whether the app can be used for any online shop. In practice, the retailer must offer Afterpay at checkout, so I check the payment choices on the shop’s own site before relying on it. Another useful question is whether the purchase still works if I pay the full amount today. If the answer is no, splitting the bill may only postpone a problem; it is not a substitute for having enough money to cover the overall cost.
People also often wonder what happens when an order needs attention after checkout. Since the retailer manages the product and order, I would start there for delivery or item questions, while keeping the payment schedule in mind separately. If an order change affects the amount or timing, I would review the updated order and the payment account rather than assuming those two records adjust in exactly the same way. Holding on to confirmations makes that check much easier.
Another decision is whether to use this instead of a card or paying directly. I would compare the actual checkout total, the dates money is due, and how each option fits my personal budget. Paying in full is simpler when cash is available; a familiar card may be preferable for someone who already manages it well. Afterpay’s main value is the installment structure, not a discount on the goods, so it is best judged as a budgeting choice rather than a way to make an expensive item cheap.
A grounded fit for planned purchases
Afterpay is a shopping app for Android and iOS, developed by Afterpay, and it is free to download. It is rated for Everyone, with a release date of August 5, 2018, and version 1.128.0 currently listed for devices running Android 7.0 or later. Those details make it straightforward to identify the app, but they do not change the core decision: the payment schedule only helps when the purchase and every later payment fit your circumstances.
My overall view is that this is a convenient option for a specific kind of shopper, not a reason to change how they shop. I would use it for a considered purchase at a participating retailer when the timing is the only awkward part and I can confidently plan for each due date. I would skip it for impulse buys, a stretched budget or a shop that does not offer it. Used with that boundary, the app can make a checkout more flexible; used without one, it can make future expenses easier to overlook.
Pros and Cons
Pros
- Easy installment payments
- No interest fees
- User-friendly interface
- Instant approval process
- Wide range of retailers
Cons
- Requires credit check
- Late fees apply
- Not available worldwide
- Limited payment flexibility
- May encourage overspending
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Afterpay: Pay over timeAfterpay | 4.0 | 10,000,000+ | Free |
 SHEIN-Shopping OnlineRoadget Business PTE. LTD. | 4.8 | 1,000,000,000+ | Free |
| 4.4 | 1,000,000,000+ | Free | |
 Amazon ShoppingAmazon Mobile LLC | 4.4 | 1,000,000,000+ | Free |
Alternatives Worth Trying


More Shopping Reviews
View All More Shopping Reviews


Frequently Asked Questions
What is Afterpay and how does it work?
Afterpay is a 'buy now, pay later' service that allows you to purchase items immediately and pay for them in four equal installments, due every two weeks. It’s interest-free as long as you pay on time, making it a convenient option for budgeting. Users can shop online or in-store at participating retailers, providing flexibility for shoppers who prefer to spread out their payments.
Does Afterpay charge any fees or interest?
Afterpay does not charge any interest on the purchases. However, if you miss a payment, you may incur a late fee. It's crucial to keep track of your payment schedule, as the late fees can add up. Making timely payments ensures you maintain a good standing with Afterpay, allowing continued access to their service without any additional costs.
Is there a credit check required to use Afterpay?
No, Afterpay does not require a traditional credit check to use their service, which makes it accessible to a wider range of users. Instead, they use their own criteria to approve accounts, so most people can get started with just a few simple steps. This opens up opportunities for those who might not have perfect credit to still utilize a payment plan option.
How do refunds and returns work with Afterpay?
When you return an item purchased with Afterpay, the refund process depends on the retailer's return policy. Once the return is approved, Afterpay will adjust your payment schedule or issue a refund if you've already made payments. It's important to check both the retailer’s and Afterpay's policies to understand the full process and any potential impacts on your payment plan.
Can I use Afterpay for all types of purchases?
Not all purchases can be made with Afterpay. It is only available at participating retailers, both online and in-store. Before shopping, it’s recommended to check if the store accepts Afterpay as a payment option. Additionally, there might be some restrictions on the types of goods you can buy using Afterpay, so reviewing their terms of service can provide more clarity.
Advertisements

Download Afterpay: Pay over time
About This Listing
- Last Checked
- Nov 5, 2026
- Version Reviewed
- 1.142.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.