

Upgrade - Boost Money
Upgrade, Inc.
Advertisements
App Specs
- Version
- 1.3.0
- Updated
- Nov 1, 2026
- Android Version
- 12
- Installs
- 50,000+
- Developer
- Upgrade, Inc.
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
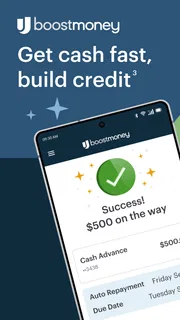
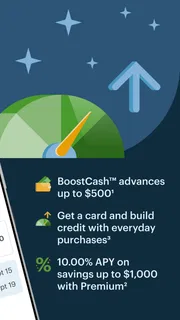
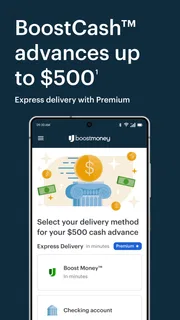
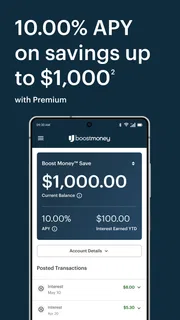
Our Review
 Analysis byUnlimiteds
I spent time with Upgrade - Boost Money as a finance app, paying particular attention to how comfortably it can be used in different everyday situations. Its promise is straightforward: bring spending, saving, and credit-building into one place. That combination can be useful, but it also means the app asks users to move between several money decisions rather than simply checking a balance. My overall impression is that it is most appealing to someone who wants a single financial starting point, while people who prefer highly specialized tools may find the experience less focused.
Developed by Upgrade, Inc., the app is free and aimed at Everyone. It has reached over 50 thousand installs and holds a 4.1 average from more than 170 ratings, with around 50 written reviews. Those figures suggest a modest but established presence rather than the scale of a household-name banking platform. The current release is version 1.3.0, and it requires Android 12 or newer. It was released on February 27, 2026, so Android users should check their device version before trying to install it.
How Upgrade - Boost Money feels to use in real life
I find the most useful way to approach this section is to treat the app as a place to connect everyday spending choices with longer-term saving and credit goals, rather than as a screen to check hurriedly. A small routine—review first, decide afterward—can make that broader purpose easier to manage. That leads naturally to the practical question of which everyday situation benefits most from having those priorities together.
Readability and navigation when money is the main concern
The strongest idea behind the app is the way it groups three related goals: spending, saving, and building credit. I find that structure easier to understand than opening separate apps for a spending account, a savings tool, and a credit-focused service. When I am trying to answer a simple question such as “Can I afford this purchase?” it is helpful to have the broader financial context nearby instead of treating the transaction in isolation.
That said, combining several financial jobs can also make navigation feel mentally heavier. A user who only wants to see recent spending may not want to think about credit-building at the same time. The app is therefore easier to approach when I decide what I am doing before opening it: checking available money, reviewing saving progress, or considering credit habits. That small change in routine prevents the broader feature set from becoming distracting.
For readability, financial apps need to make numbers feel immediately meaningful. A balance, a recent purchase, and a credit-related action do not have the same importance, even if they appear in the same general area. I would use the app slowly during the first few sessions, reading each label rather than tapping through quickly. This is especially sensible for anyone who is unfamiliar with credit terminology or who tends to confuse available funds with money that is safe to spend.
One practical habit is to review the app at a calm time rather than while standing in a checkout line. A quick glance before a purchase can be useful, but financial decisions become harder when the screen is competing with noise, queues, or pressure from someone waiting. I found the app more useful as a short planning tool than as something to operate hurriedly during a transaction.
The store summary, “Spend, Save, Build Credit,” describes the app’s central direction clearly, but it does not tell the whole story of using it. The real value depends on whether those three areas match your personal priorities. If saving and credit are active concerns, the combined approach feels purposeful. If you already have a reliable system for those tasks, the extra financial layer may not justify changing your routine.
Motor and sensory considerations during everyday use
From an interaction standpoint, a finance app should reduce the chance of accidental actions. I recommend using deliberate taps and pausing before confirming anything that affects money. This is not a criticism unique to this product; it is a sensible approach whenever a screen contains balances, transfers, or credit-related choices. Users with limited dexterity may prefer to operate it while the phone is supported on a table instead of holding it one-handed.
People with tremors, reduced precision, or fatigue may also benefit from enlarging system text and display settings before judging the experience. Larger text can make numbers easier to inspect, although it may also cause more scrolling or make a compact screen feel crowded. That trade-off matters in a finance app: readability is more important than seeing every option at once, but extra scrolling can make it harder to maintain a clear sense of where you are.
For users with low vision, I would not rely on color alone to interpret any financial state. Read the accompanying wording and confirm the actual figures. A colored indicator may be easy to miss in bright sunlight, under glare, or for someone who distinguishes colors differently. The safest workflow is to treat visual emphasis as a guide and the written amount or status as the information that deserves final attention.
Users who are sensitive to visual clutter may appreciate approaching the app with one task at a time. I would open it to review a purchase, finish that review, and leave rather than moving through every financial area in one sitting. This makes the experience less demanding and reduces the chance of mixing up a spending decision with a saving or credit decision.
For people who use screen magnification, voice access, or other phone-level assistance, the practical question is whether the app remains understandable when the interface is enlarged or controlled indirectly. I would test that with low-risk browsing first: reading account information, opening a recent transaction, and returning to the main screen. Only after that feels comfortable would I attempt a money action. This staged approach is more useful than assuming that a finance app will behave perfectly with every assistive setup.
Situational access: when the same app works differently
Access is not only about disability. A person can have full vision and steady hands yet still struggle with a finance app while commuting, caring for a child, working in a noisy room, or dealing with stress. Upgrade - Boost Money makes the most sense when I can give it focused attention. A quiet review before the week begins is a better setting than trying to understand credit information while distracted.
Consider a realistic scenario: I am preparing for a weekend trip and want to make sure a planned purchase will not interfere with saving. I would first review recent spending, then consider the amount I want to keep available, and finally look at the credit-building side only if it is relevant to my plan. The benefit is not merely having several financial tools in one app; it is being able to connect a short-term spending decision with a longer-term goal.
Another useful situation is a new-to-credit user who wants a more organized place to think about financial habits. The app may feel less intimidating than assembling several unrelated services, because the spending, saving, and credit themes point toward one broader routine. Even then, I would avoid treating any credit-related progress as instant or automatic. Responsible use still requires understanding what an action means and checking information carefully.
For someone managing money with a partner or family member, the app could be convenient as a shared topic for discussion, but I would not assume that one person’s comfortable workflow automatically works for everyone else. A partner with different reading needs, language preferences, motor limitations, or financial experience may need more time and a separate method for reviewing the same decisions. The inclusive choice is to agree on a process rather than handing over the phone and expecting the other person to follow along.
Travel and poor connectivity are also moments when expectations should be realistic. I would not make a time-sensitive financial decision in an unfamiliar environment without first confirming that I can access the information I need. When a phone is low on battery, the screen is hard to read outdoors, or attention is split between navigation and money, postponing a nonessential review is safer than rushing.
Where the experience can still create barriers
The biggest barrier is financial complexity rather than visual design. Spending, saving, and credit-building are connected, but they are not interchangeable. A person may understand a balance while still finding credit concepts confusing. The app can provide a useful home for these topics, yet it cannot remove the need to read carefully or ask for independent advice when a decision has serious consequences.
A second barrier is the Android requirement. Because the app needs Android 12 or newer, users with older phones cannot simply join the experience without changing devices or operating systems. That is a practical access issue for people who keep older hardware for budget, environmental, or familiarity reasons. It also means that a family member may be unable to use the same app even when another person in the household can.
The app’s free price removes an obvious download barrier, but “free” does not automatically mean frictionless. Financial products deserve more scrutiny than ordinary casual apps because the user is trusting them with sensitive decisions. Before committing to a routine, I would read every in-app explanation connected to an account or credit action and make sure I understand what is being requested.
There is also a concentration risk in putting several money tasks together. A single app can be convenient, but it can encourage users to treat one screen as the complete picture of their finances. I would still keep an independent record of important payments and goals, whether that means a simple note, a spreadsheet, or another trusted account view. That backup is particularly useful for users who need more time to process information or who may forget a decision made during a stressful moment.
Compared with a traditional bank app, Upgrade - Boost Money has a more focused identity around spending, saving, and credit-building rather than trying to represent every possible banking service. Compared with a standalone budgeting app, it sounds more directly connected to financial activity instead of being only a planning workspace. Compared with a dedicated credit tool, its advantage is the connection to everyday money behavior; its possible weakness is that a specialist service may offer a deeper explanation of one narrow subject. The better choice depends on whether you value one joined-up routine or maximum depth in a single area.
I would also be cautious about recommending it to someone who needs a very simple, single-purpose interface. A person who only wants a basic spending record may find the broader financial framing unnecessary. Likewise, anyone who prefers desktop-first financial management may not enjoy making a phone the center of the workflow. The app is better suited to users who are comfortable checking money information on Android and who want several related goals close together.
Small workflow choices that make it more inclusive
My first tip is to create a personal vocabulary before using the app regularly. Write down what “spend,” “save,” and “build credit” mean for your own situation. This sounds simple, but it prevents the three ideas from blending together when you are tired or under pressure. It is especially helpful for users who process unfamiliar financial language slowly.
My second tip is to separate observation from action. On one visit, review information only. On another, decide whether an action is necessary. This two-step workflow lowers the risk of making a quick choice because a button is visible or because the user is trying to finish before losing concentration. It also gives someone who uses assistive technology more time to confirm each screen.
My third tip is to use a consistent review moment, such as after a weekly grocery plan. I would compare expected spending with the amount I want to preserve for saving, then consider whether any credit-related task actually belongs in that session. The important insight is that the app becomes easier to understand when it is attached to a familiar routine rather than opened randomly whenever anxiety appears.
My fourth tip is to explain the workflow to a trusted support person without sharing private credentials. If a user has memory difficulties, limited confidence with finance, or trouble reading small text, a second person can help create a checklist: open the app, review the relevant area, read the amount aloud if comfortable, and stop before taking an action that is not understood. Support should improve comprehension, not replace the user’s control.
Finally, I would test the app under the conditions in which I actually plan to use it. Try it with larger text, in a dim room, outdoors, with one hand, or while using the phone’s accessibility controls. A smooth experience at a desk does not guarantee the same result on a crowded train. This kind of personal test reveals more than a general claim that an app is easy to use.
My inclusive verdict
I see Upgrade - Boost Money as a sensible option for Android users who want spending, saving, and credit-building considered together. The free finance app is easy to understand at the concept level, and its 4.1 average from over 170 ratings gives it a reasonably positive public reception. Its audience is not limited to experienced money managers: a beginner may appreciate the single destination, provided they take time to understand each financial area.
Its inclusive potential comes from flexibility of use rather than from any special promise. Users can adapt the surrounding routine by enlarging text, slowing down decisions, using phone-level assistance, or reviewing one goal at a time. Those adjustments matter because financial confidence varies widely, and a person who finds the app comfortable may still need a different pace or support arrangement.
I would skip it if I wanted only a bare-bones expense tracker, if my phone cannot run Android 12 or newer, or if I strongly prefer a dedicated desktop finance system. I would also choose a more specialized alternative when I need unusually deep budgeting analysis or narrowly focused credit education. The combined approach is convenient, but convenience is not the same as completeness.
For the right user, the best reason to try it is not the slogan-like promise of doing everything in one place. It is the chance to build a repeatable money review that connects a purchase today with saving intentions and credit habits over time. The most important accessibility feature is a workflow you can understand, control, and repeat without rushing. Used that way, Upgrade - Boost Money feels like a practical companion for everyday financial decisions, with enough flexibility to help many contexts but enough complexity that careful, deliberate use remains essential.
Pros and Cons
Pros
- Simple interface makes balance upgrades easy to understand.
- Useful for tracking progress toward financial goals.
- Quick access to upgrade-related money features.
- Clear visual feedback helps monitor account improvements.
- Suitable for users who prefer a straightforward money app.
Cons
- Some features may require in-app purchases or subscriptions.
- Benefits can depend on your location and available services.
- May request sensitive financial or personal information.
- Limited value if you do not regularly use upgrade tools.
- Performance and support quality may vary by device.
Advertisements
Other Releases by Upgrade, Inc.
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Upgrade - Boost MoneyUpgrade, Inc. | 4.2 | 50,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |

Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Upgrade - Boost Money, and how does it work?
Upgrade - Boost Money is a financial app designed to help eligible users access personal credit products and manage related account information from a mobile device. After creating an account, you may provide personal and financial details so the service can evaluate eligibility. Available products, rates, limits, repayment terms, and approval decisions vary by applicant and should be reviewed carefully before accepting any offer.
Is Upgrade - Boost Money a legitimate and safe app to use?
The app may be useful for people looking for credit or personal finance services, but users should still verify the publisher, privacy policy, permissions, and customer-support details before signing up. Financial applications handle sensitive information, including identity and banking data, so download the app only from an official store and avoid sharing login codes or account details through unofficial messages or websites.
Does Upgrade - Boost Money guarantee approval or instant access to money?
No financial app can generally guarantee approval for every applicant. Upgrade - Boost Money may review information such as identity, income, credit history, and other eligibility factors before presenting an offer. Even when an application is accepted, funding speed can depend on verification, the selected product, banking institutions, weekends, and other processing conditions. Read the final offer instead of relying on advertising claims.
What fees, interest rates, and repayment conditions should I check?
Before accepting any financing through Upgrade - Boost Money, carefully review the annual percentage rate, interest rate, origination or administrative fees, late-payment charges, loan amount, repayment schedule, and total amount payable. The cost can differ significantly between users. Confirm whether fees are deducted from the amount received and whether early repayment, missed payments, or changes to payment methods create additional costs.
What information and permissions does Upgrade - Boost Money require?
During registration or an application, Upgrade - Boost Money may request information needed to verify your identity, assess eligibility, communicate with you, and connect an approved product to a bank account. Check every permission and disclosure before proceeding, especially access involving contacts, location, notifications, or financial data. Only provide accurate information, and review the privacy policy to understand how data may be collected, stored, and shared.
Advertisements

Download Upgrade - Boost Money
Unlimiteds is available from its official store. We do not host or distribute app downloads.
About This Listing
- Last Checked
- Nov 1, 2026
- Version Reviewed
- 1.3.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.