


Sumio: Net Worth Tracker
Fiduciary
Advertisements
App Specs
- Version
- 1.9.18
- Updated
- Nov 15, 2026
- Android Version
- 7.0
- Installs
- 10,000+
- Developer
- Fiduciary
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
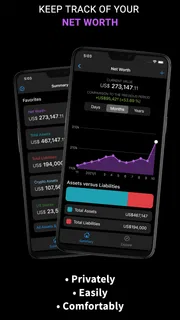
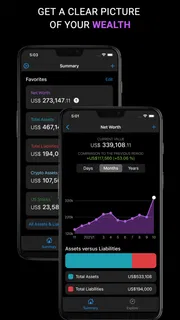
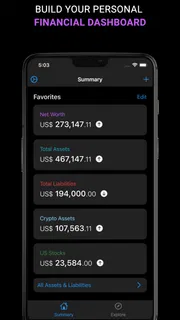
I approached Sumio: Net Worth Tracker as a practical finance app rather than a replacement for a full banking platform. Its purpose is to give you a clearer picture of your overall financial position by bringing net worth, investments, stocks, funds, and other assets into one place. After spending time with it, my main impression is that it works best as a personal overview tool: something you check regularly to understand direction and balance, not something you should treat as a complete trading terminal or financial adviser.
That distinction matters because tracking money on a phone can be surprisingly demanding. A useful tracker has to make financial information understandable while avoiding unnecessary friction when markets move, accounts change, or you simply have a few minutes between errands. Sumio, developed by Fiduciary, aims at that middle ground. It is free to install, although in-app purchases range from around three dollars to around thirty dollars per item, so it is worth checking which parts of the experience are included before making it your long-term system.
How Sumio feels when your connection is part of the experience
The most important practical question is not only what the app tracks, but how much of your routine depends on current information being available. Finance apps are especially sensitive to connectivity because prices, balances, and portfolio details can become outdated quickly. With Sumio, I would plan to use a reliable connection whenever I want to review current investment information or make a meaningful decision based on what I see.
That does not make the app inconvenient, but it changes how I would use it. A quick glance while travelling may be fine for reviewing figures already visible on screen, while a deeper portfolio check is better done when the app can refresh properly. I would not open it in a rush and assume that the first numbers displayed automatically represent the latest possible situation. For any tracker, the difference between a remembered snapshot and a refreshed view is important, especially during a busy market day.
My practical rule is simple: use Sumio for orientation, then verify time-sensitive information before acting. That is good financial hygiene regardless of the app, but it is particularly relevant when a mobile tracker brings several kinds of assets together. A stock price, a fund value, a manually recorded asset, and your broader net worth may not all behave on the same update cycle. Seeing them in one dashboard is useful, yet it should not be confused with every figure changing at exactly the same moment.
Connectivity also affects patience. If you are checking your net worth in a place with an unstable signal, repeated loading or delayed updates can make the experience feel less dependable than it is. I would avoid editing important entries during that kind of session. Instead, I would wait until the connection is stable, review the figures carefully, and then make changes in one deliberate pass. That workflow reduces the chance of mistaking a temporary delay for a missing asset or an incorrect total.
A good fit for short mobile check-ins
Sumio makes the most sense for people who want a compact financial habit. I can imagine opening it after payday, at the end of a month, or before reviewing a savings goal. Those moments do not require the complexity of a brokerage workstation. They require a readable summary that helps answer basic questions: Has my overall position improved? Are investments taking up more of my financial picture than I intended? Have I forgotten to account for an important asset?
The mobile format is also useful when a financial decision is connected to an everyday choice. Suppose I am considering a large purchase. Instead of looking only at the cash in my current account, I can use a net-worth view to think about the wider effect of that purchase. That does not turn the app into a budgeting tool by itself, but it can add context that a simple bank balance misses.
Another realistic use is a monthly household review. One person can update the figures while both partners look at the same broad picture. This is more constructive than discussing finances from memory, particularly when investments, savings, and valuable possessions are spread across different places. I would still agree in advance on how to value less liquid assets, because a tracker can display an amount but cannot decide whether your chosen estimate is sensible.
For investors, the portfolio and stock tracking angle is the strongest reason to try it. I like the idea of keeping an investment view alongside other assets rather than mentally separating everything into unrelated accounts. The trade-off is that a consolidated overview is not the same as a specialist investment app. If you need advanced charting, order execution, tax-lot analysis, or detailed research, your brokerage or a dedicated portfolio service will probably be more appropriate.
What to enter, and how to keep the picture honest
The quality of a net-worth tracker depends heavily on the discipline behind the entries. I would begin with the assets that matter most to my overall position: investment holdings, savings, property or vehicles if relevant, and major liabilities if the app’s setup supports the way I want to represent them. The point is not to capture every tiny item. It is to build a consistent picture that can be compared over time.
One useful approach is to separate stable assets from values that move frequently. A long-term asset may only need occasional attention, while stocks and funds deserve more regular review. Mixing both into one number without remembering their different behaviour can create unnecessary anxiety. A falling market value does not necessarily mean your whole financial plan has failed, just as a temporary rise does not prove that a spending decision is affordable.
I would also record a note for myself about valuation dates, even if that note lives outside the app. For example, if I enter an estimated value for a vehicle or another asset, I would remember when that estimate was made and use the same method next time. Consistency is more valuable than false precision. Updating an asset with a completely different valuation method each month can make the net-worth trend look more dramatic than reality.
This is one of the less obvious strengths of using a dedicated tracker: it encourages you to define what “my finances” actually includes. Many people count investments and bank balances but ignore valuable assets or debts. Others include everything once and then never update it. Sumio cannot solve that habit automatically, but its focus makes the omission visible. I found that the app is most helpful when I treat setup as a small financial audit rather than a quick form-filling exercise.
When the app struggles: delayed information, mistakes, and recovery
Every finance tracker has failure points, and the most realistic ones are ordinary rather than dramatic. A connection can drop, a value can be entered incorrectly, or a portfolio figure can look surprising because one component has not refreshed as expected. My advice is to avoid making a correction while frustrated. First identify whether the problem is an entry, a stale figure, or a broader connection issue.
If something looks wrong, I would compare the relevant holding or asset with its original source, then correct only the item that explains the difference. Changing several entries at once makes it difficult to find the real cause. Keeping a simple personal record of major updates can also help you recover from confusion. It does not need to be elaborate; a date, the asset, and the reason for the change are usually enough to reconstruct what happened.
Recovery is especially important when you use the app after a period away. I would not assume that an old portfolio view is still an accurate reflection of current holdings. Instead, I would review the most changeable items first, then check the slower-moving assets. That order saves time and prevents a large, stable asset from distracting you from a small but rapidly changing investment entry.
The app’s current version is 1.9.18, and I would keep an eye on updates like I do with any finance application. Updates can improve compatibility and reliability, but they are also a reminder to revisit how the app fits into your routine. Before updating or changing your process, I would make sure I understand which figures are manually maintained and which ones depend on refreshed information. A tracker is only reassuring when you know where its numbers come from.
There is also a psychological recovery step. If the total changes sharply, resist the temptation to check it repeatedly. Net worth is a longer-term measure, while individual holdings can move quickly. I prefer using a regular review schedule and investigating unusual changes calmly. Sumio is better at supporting that habit than at replacing it.
Privacy-minded habits for a finance app
Because this is a finance app, I would be deliberate about where and how I use it. A phone screen can reveal more than expected in a public place, especially when the app displays a complete financial picture. I would avoid opening it over someone’s shoulder on public transport and would be careful with screenshots or shared devices. These are simple precautions, but they matter more when one screen combines investments, assets, and net worth.
I would also limit the information I enter to what helps me make decisions. A useful tracker does not need a detailed personal story attached to every asset. Broad, consistent labels are often enough. If I am tracking a vehicle, savings account, or fund, I would use a description that makes sense to me without adding unnecessary personal details. This reduces clutter and makes reviews faster.
Connectivity adds another layer to data-conscious use. I would avoid relying on an unfamiliar public network for sensitive financial activity when I can wait for a trusted connection. If I am only planning a review, I can prepare the questions I want to answer first and then open the app briefly. That is more efficient than leaving a finance screen open while moving between networks or locations.
There is a trade-off between convenience and completeness. The more assets you include, the more useful the total may become, but the more responsibility you take on for maintaining accurate information. I would rather have a smaller, dependable overview than a detailed dashboard filled with stale estimates. This is a particularly important tip for new users: start with the financial items that influence your decisions most, then expand only when the maintenance feels manageable.
Sumio is also not the right choice for someone who wants every financial task in one place. If your priority is strict expense categorisation, bill reminders, automated budgeting, or direct trading, a dedicated alternative may serve you better. A bank app is usually the natural choice for current cash activity, while a brokerage app is better for orders and investment execution. Sumio’s value is in the space between those tools, where you want a broader personal balance sheet.
Who should use it, and who should skip it?
I would recommend trying Sumio if you have accounts and assets scattered across several services and want a single net-worth perspective. It is also appealing for someone who is beginning to invest and wants to understand how a portfolio fits into their wider finances. The free entry point lowers the barrier to testing the workflow, though I would pay attention to which functions require an in-app purchase before building a routine around them.
It is suitable for adults and younger users alike in terms of its Everyone content rating, but suitability depends more on financial maturity than age. A new investor may benefit from seeing the whole picture, while an experienced investor may find it too limited if they expect professional-grade analysis. The app has passed the early adoption stage with over ten thousand installs and an average rating of 3.8 from around eighty ratings, which suggests a modest but real user base rather than a universally acclaimed service.
I would skip it if you want automatic certainty. No tracker can make inconsistent inputs accurate, and a combined net-worth figure can be misleading when its components are not maintained. I would also choose something else if I need a service designed primarily around spending control or active trading. Sumio is most convincing when the question is, “What is my overall financial position?” rather than, “Where did every dollar go this week?” or “How do I place an order right now?”
My final view on connected, mobile net-worth tracking
After looking at the app through the realities of mobile use, I see Sumio as a focused companion for financial awareness. Its best quality is the way it encourages a wider view: investments, stocks, funds, and other assets can be considered together instead of being left in separate mental compartments. That can make monthly reviews more meaningful and help you notice gaps in your own financial picture.
The main caution is to treat connectivity and freshness as part of the workflow, not as invisible background details. I would use a stable connection for updates, verify figures before acting, and keep a consistent schedule for reviewing manually maintained values. Those habits make the app more dependable without asking it to do something it was not designed to do.
My recommendation is positive for people seeking a simple net-worth overview, but conditional for users who need deep automation or advanced investing tools. Start with a small, carefully maintained set of assets, observe whether the review process genuinely helps you, and only then decide whether the paid options are worthwhile. Used that way, Sumio can become a useful checkpoint in your financial routine rather than another app that displays numbers without changing how you understand them.
For a free finance app from Fiduciary, it offers a clear reason to exist and a practical mobile use case. I would not make it my only financial tool, but I would consider it a sensible layer between everyday banking and specialist investment services. Its success depends less on constant checking than on honest entries, sensible interpretation, and a calm habit of reviewing the bigger picture.
Pros and Cons
Pros
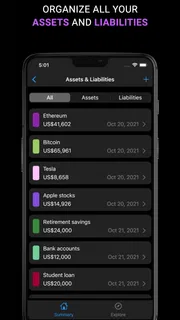
- Clear net worth overview with assets and liabilities in one place.
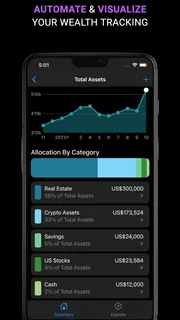
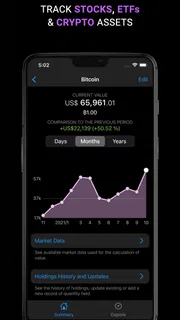
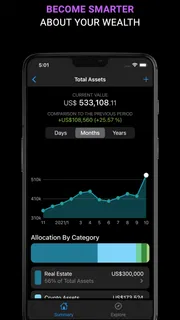
- Useful charts help visualize financial progress over time.
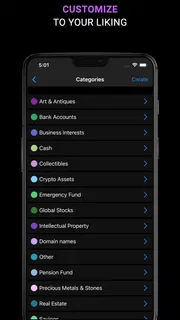
- Supports multiple account and investment categories.
- Regular tracking can encourage better saving and budgeting habits.
- Clean interface makes entering and reviewing finances straightforward.
Cons
- Manual updates can become time-consuming for users with many accounts.
- Some advanced features may require a paid subscription.
- Financial data accuracy depends on consistent, careful user input.
- Limited automation may reduce convenience compared with bank-linked trackers.
- Users may need to verify how their personal data is stored and protected.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Sumio: Net Worth TrackerFiduciary | 3.8 | 10,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 Inter Banking & Money TransferBanco Inter SA | 4.4 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Sumio: Net Worth Tracker used for?
Sumio: Net Worth Tracker is a personal finance app designed to help you monitor your overall financial position in one place. You can record assets such as bank accounts, investments, property, vehicles, and digital currencies, then compare them with debts and other liabilities. The app focuses on net worth tracking rather than replacing a full banking or budgeting service, making it useful for regularly reviewing long-term financial progress.
Do I need to connect my bank accounts to use Sumio?
No, connecting a bank account is not always required. Sumio can generally be used by entering financial information manually, which may be preferable for users who value privacy or whose financial institution is not supported. Depending on the platform and available integrations, automatic synchronization may be offered for selected accounts. Before relying on connected data, check which institutions and regions are supported and review the required permissions.
Is Sumio: Net Worth Tracker safe for managing financial information?
Sumio handles information that can be highly sensitive, so users should review its privacy policy, security documentation, and account-protection options before adding detailed data. Avoid entering unnecessary credentials or confidential information, and enable device security or any available app authentication features. If you use account connections, confirm what access is requested and remember that security also depends on your phone, email account, and connected financial providers.
Can Sumio track investments, cryptocurrency, property, and debts?
The app is intended to provide a broad picture of your finances, so it can be useful for recording different asset and liability categories, including investments, cash accounts, real estate, vehicles, loans, credit cards, and cryptocurrency. However, available tracking methods may differ by category: some values may update automatically while others require manual entry. Review balances periodically because prices, exchange rates, and account values can change.
Is Sumio: Net Worth Tracker free to download and use?
Sumio may be available to download at no initial cost, but some features can depend on a subscription, premium plan, or in-app purchase. The exact offer may vary between Android and iOS and can change over time. Before starting a trial or entering payment details, check the current store listing for included features, billing frequency, renewal terms, and cancellation instructions so there are no unexpected charges.
Advertisements

Download Sumio: Net Worth Tracker
About This Listing
- Last Checked
- Nov 15, 2026
- Version Reviewed
- 1.9.18
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.