


SoFi: Bank, Investing & Crypto
Advertisements
App Specs
- Version
- 3.110.1
- Updated
- Nov 7, 2026
- Android Version
- 8.0
- Installs
- 5,000,000+
- Developer
- Social Finance, LLC
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
When I open SoFi, I think of it less as a collection of separate money tools and more as a place to check the everyday picture: what came in, what went out, what I have set aside, and whether I want to invest. That broad approach is useful if you prefer fewer finance apps, but it also asks you to be clear about which jobs you want the app to handle. I would start with one routine, such as checking spending after payday, rather than trying every section at once.
A practical routine for everyday money
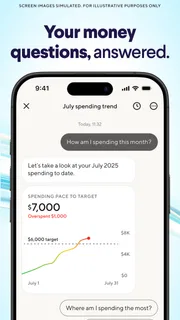
A straightforward way to use SoFi is to connect the accounts you actually want to monitor, then make a habit of checking the activity around a regular moment in your week. For example, after a grocery run or a weekend of errands, I would review the recent transactions and see whether the spending categories tell a useful story. The point is not to scrutinize every coffee; it is to catch a recurring charge or a category that has crept up before it becomes a surprise.
For a person whose income arrives on a predictable schedule, payday can be a useful checkpoint. I would first confirm that deposits and bills look right, then decide what amount can stay available for near-term spending and what amount belongs in savings or investing. Keeping those decisions deliberate matters more than opening every feature. A finance app can make activity easier to see, but it cannot decide which expenses are essential or how much risk feels comfortable to you.
Small choices that make the overview more useful
Account linking is worth approaching selectively. Linking everything may create a fuller snapshot, but it can also make the feed busier and harder to interpret. I would begin with the accounts that answer a specific question—such as whether monthly spending is outpacing income—and add others only if they improve that view. If a transaction is categorized in a way that does not fit your own budget, treat the category as a prompt to review your habits, not as a perfect judgment of how you spend.
It also helps to decide in advance what each visit to the app is for. A quick check of recent activity is different from a longer session spent reviewing investments or credit information. Separating those habits can reduce impulse decisions: I would not buy a stock just because I opened the app to check a bill, and I would not treat a credit score update as a reason to apply for new credit. A useful money dashboard is a starting point for decisions, not a substitute for them.
Where an all-in-one approach can fall short
Compared with a banking app focused mainly on deposits, payments, and balances, SoFi brings investing and other financial tools into the same experience. That can save context switching if you genuinely use several of those services. A dedicated budgeting app may still suit someone who wants detailed control over household categories, while a specialist brokerage may be preferable to an investor who needs a particular research workflow. I see SoFi’s appeal as convenience across several money tasks, not as a guarantee that it is the deepest option for every one.
There is a trade-off to putting more of your financial life in one place: the app becomes more useful as an overview, but you may need to spend time deciding which account details belong there and which decisions should remain separate. People who prefer a simple bank account with no investing prompts may find the broader menu distracting. Likewise, someone who wants hands-on portfolio analysis should compare the investing experience with a dedicated service before making it their main tool.
Who is likely to get the most from it
I would consider SoFi if I wanted banking, saving, spending visibility, and investing close together, and if I were willing to build a regular review habit. It can be especially convenient for someone who is beginning to organize finances and wants to see several parts of the picture without maintaining a separate app for each task. A more experienced user can also benefit by setting a repeatable sequence—check cash flow, review upcoming obligations, then look at investments—so routine money management does not turn into aimless browsing.
I would be more cautious if I needed a highly specialized budgeting system, a particular brokerage tool, or a bare-bones bank interface. Before moving everyday money, I would check that the available account features fit how I receive income, pay bills, and access funds, then test the app with a limited routine. That gives me a chance to see whether its organization suits me before I rely on it as my only financial view.
Hey there! Have you heard about the SoFi - Banking & Investing app? I recently gave it a spin, and let me tell you, it’s quite the game-changer for managing your finances on the go. Whether you're looking to invest, save, or just need a new banking app, SoFi might just have everything you need.
Getting Started with SoFi
First things first, downloading and setting up the SoFi - Banking & Investing app is a breeze. Available for both Android and iOS, it’s just a quick download away. Once you open it, the sleek and intuitive design immediately stands out. The app guides you through the setup process with ease, making it user-friendly even if you’re not a tech wizard. You can link your bank accounts, set up direct deposits, and even start investing with just a few taps.
The Banking Experience
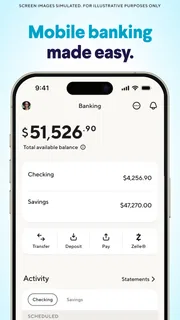
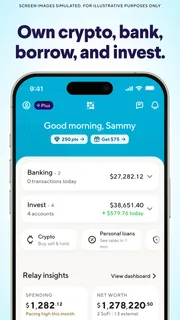
Let’s talk about the banking features. SoFi offers a comprehensive suite of tools to help you manage your money. You can pay bills, transfer funds, and track your spending all in one place. One feature I found particularly handy is the spending tracker. It categorizes your expenses automatically, which is super helpful for keeping an eye on where your money is going. Plus, there are no account fees, which is a major win!
Investing Made Simple
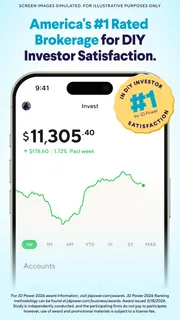
Now, if you’re like me and find the world of investing a bit daunting, SoFi’s got your back. The app offers a range of investment options, from stocks and ETFs to crypto, all accessible with the tap of a button. What’s cool is that they provide educational resources to help you make informed decisions. I started with their automated investing feature, which takes the guesswork out of the equation and helps grow your portfolio based on your risk tolerance and goals.
Additional Features Worth Mentioning
One thing I love about SoFi is the community aspect. They have a feature called SoFi Relay, which lets you connect with other users to share tips and advice. It’s like having a financial support group right in your pocket. Also, their customer service is top-notch, available through chat, phone, or email, which is great if you ever run into any issues.
Another highlight is the SoFi credit score monitoring. It’s a free feature that keeps you updated on your credit status, and they even offer personalized tips to help you improve it. This is a fantastic tool if you’re looking to maintain or boost your credit score.
Final Thoughts
In conclusion, the SoFi app is a fantastic tool for anyone looking to streamline their banking and investing needs. Its user-friendly interface, comprehensive features, and commitment to customer service make it stand out in the crowded field of financial apps. Whether you’re a seasoned investor or just starting out, SoFi provides the tools and resources to help you succeed. So, why not give it a try and see how it can revolutionize your financial life?
What I would check before settling in
SoFi is a free finance app from Social Finance, LLC, and its broad menu is the main reason I would try it. It has a 4.0 average from around 49,000 ratings, with roughly 19,000 reviews, and more than 5 million installs. Those figures suggest plenty of people have taken a look, but they do not tell me whether the combination of banking and investing will match my habits. I would judge it by whether the linked-account overview and the services I actually use make routine decisions simpler.
The app is rated for Everyone, was released on April 10, 2017, and its current version is 3.72.2, with Android 8.0 as the minimum operating system. I would still check that my device can run it and that the specific features I want are available for my situation before planning a switch. Its appeal is not simply that it puts many financial labels on one screen; it is that the same place can support a sequence of small decisions, provided I keep the sequence focused.
Build a repeatable pattern, not a pile of alerts
For a useful weekly check-in, I would follow the same order each time: scan account activity, notice upcoming bills, review spending categories, and only then decide whether there is money to move toward a goal. That order helps separate cash needed soon from money I can afford to leave untouched. It also makes a quick glance more meaningful: a balance alone can look healthy even when several obligations are about to arrive.
A practical example is a week when a regular deposit lands just before rent and other household bills are due. I would first make sure the deposit appears, then account for those obligations before treating the remaining balance as available spending money. If I use savings or investing tools, I would make that choice after checking the near-term picture rather than reacting to a good-looking balance. This small pause is a more dependable safeguard than assuming an all-in-one interface will automatically organize my priorities.
Settings and habits deserve a similar check. I would review which outside accounts are linked, whether the spending categories are telling a clear story, and whether any notifications I have enabled are helpful rather than noisy. The best setup is not necessarily the most complete one. If a linked account makes the overview confusing, removing it may improve the daily view; if a category repeatedly misrepresents a purchase, I would avoid building a rigid budget around that label without checking the underlying transactions.
Use investing tools at the right pace
SoFi can make investing feel approachable, but convenient access is not the same as a recommendation to trade frequently. I would decide on a purpose and time horizon before placing an order, and use educational material to understand terms rather than as a substitute for independent judgment. Someone who is just starting out may find an automated approach less intimidating than choosing every investment, while a person who enjoys selecting and researching holdings may prefer to compare the app with a brokerage built around deeper analysis.
One useful trade-off to keep in mind is that combining an everyday cash view with an investment balance can make the full picture easier to see, yet those balances serve different jobs. Money needed for an upcoming bill should not be treated like long-term investment capital simply because both appear in the same app. I would keep my own mental boundary—or a written plan—between short-term cash and funds exposed to market movement. That distinction matters especially when markets are unsettled and a temporary drop might tempt someone to change a long-term plan impulsively.
Know which questions the app can help answer
SoFi can help me see activity and organize several financial tasks, but I would not expect a spending category to explain why a month felt expensive, or a credit score view to replace a full review of a credit report. If I am trying to solve a specific problem, I would use the app as one source of context and then inspect the relevant transactions or account details. For an error, a missing payment, or an account issue, I would use the available support options rather than assuming that a dashboard display resolves the underlying matter.
Another reasonable question is whether to move all banking to one app. I would not make that decision just because setup looks easy. First I would confirm how deposits, bill payments, transfers, and access to money fit my routine, then try a limited use case and keep my existing arrangement available while I learn the workflow. That is particularly sensible for anyone whose pay schedule or bill timing is irregular. Convenience is valuable, but reliability in the moments I need cash or need a payment to go through matters more.
A considered verdict for different kinds of users
SoFi is strongest for someone who values a connected view and will use more than one part of it—perhaps checking everyday activity, setting money aside, and keeping an eye on investments in a shared routine. I like the possibility of reducing app-hopping, especially for a person who is building financial habits and wants a clear place to review progress. The app’s breadth is also its central compromise: a user who wants a very simple banking screen or specialist-level budgeting and investment controls may be happier with separate tools chosen for those specific jobs.
My advice is to begin with a narrow, repeatable task, such as checking recent spending once a week, and expand only when another feature solves a real need. Keep account links intentional, treat categories as useful clues rather than unquestionable answers, and make investment choices according to a plan instead of convenience. Used that way, SoFi can be a practical financial home base; used without clear priorities, its range may feel like more menu than guidance.
Pros and Cons
Pros
- User-friendly interface for seamless navigation.
- No account fees for basic banking services.
- Wide range of financial products available.
- Free ATM access with no extra charges.
- Competitive interest rates on savings.
Cons
- Limited physical branches for in-person support.
- Some features restricted to U.S. residents.
- Occasional app bugs affecting usability.
- Customer service response time can vary.
- Investment options may be overwhelming for beginners.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 SoFi: Bank, Investing & CryptoSocial Finance, LLC | 3.8 | 5,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is SoFi and what services does it offer?
SoFi is a fintech platform that provides a comprehensive suite of financial services, including banking, investing, personal loans, student loan refinancing, mortgages, and credit cards. The app is designed to help users manage their finances more effectively by offering various tools and resources. It aims to simplify financial management by integrating multiple services into one accessible platform.
Is SoFi safe to use for banking and investing?
Yes, SoFi is considered safe for both banking and investing. It uses advanced security measures such as encryption, two-factor authentication, and continuous monitoring to protect user data. SoFi Bank, N.A. is a member of the FDIC, meaning deposits are insured up to $250,000. Additionally, SoFi Securities is a member of SIPC, providing protection for securities up to $500,000.
Are there any fees associated with using SoFi?
SoFi offers many of its services with no fees, including no account fees for its checking and savings accounts. However, users should be aware that some transactions, such as out-of-network ATM withdrawals, might incur fees. It's important to review the fee structure related to specific services like investing, where certain trade types or transactions may have associated costs.
How does SoFi's investing platform work for beginners?
SoFi's investing platform is designed with beginners in mind, offering a user-friendly interface and educational resources to help new investors. It provides options for both active and automated investing, allowing users to choose individual stocks or ETFs, or opt for a robo-advisor to build and manage their portfolio. Additionally, SoFi offers fractional shares, making it accessible for users to invest with smaller amounts.
Can I access SoFi services on both Android and iOS devices?
Yes, the SoFi app is available on both Android and iOS devices, ensuring accessibility for a wide range of users. The app is designed to offer a seamless experience across different platforms, with regular updates and features to enhance functionality. Users can manage their financial activities, from banking to investing, directly from their smartphones, making it convenient to keep track of their finances on the go.
Advertisements

Download SoFi: Bank, Investing & Crypto
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 3.110.1
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.