


Advertisements
App Specs
- Version
- 0.160.2
- Updated
- Nov 7, 2026
- Android Version
- 11
- Installs
- 100,000+
- Developer
- Ramp Business Corporation
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
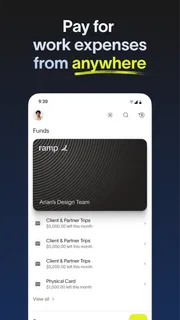
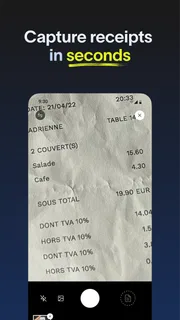
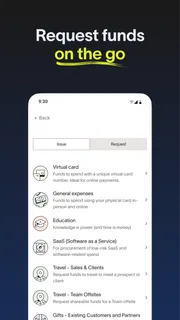
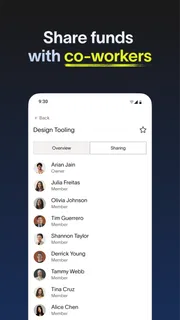
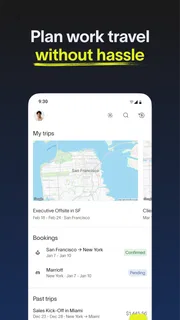
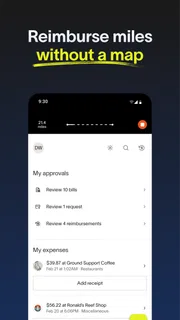
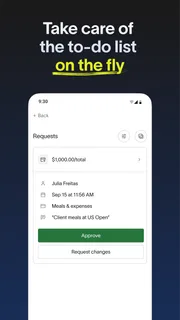
Our Review
 Analysis byUnlimiteds
When I review a finance app, I care less about a polished promise and more about whether it removes a small, repeated annoyance from my day. Ramp caught my attention for that reason. It is a free finance app from Ramp Business Corporation, aimed at making business spending easier to handle from a phone. Its store summary, “Time is money. Save both,” is brief, but the useful question is whether the app actually helps me spend less time moving between approval, payment, and expense tasks.
My overall impression is that Ramp makes the most sense as a companion for people who already work inside a Ramp business account. It is not a general personal budgeting tool, and I would not install it expecting a replacement for a normal banking app. Its value is more focused: keeping business spending work close at hand when I am away from a desk.
That focus is important. A finance app can look impressive while still being awkward during the moment I need it most—when I am trying to check a purchase, deal with an expense, or understand whether a business payment fits the rules. Ramp is strongest when the company has already chosen its financial workflow and employees need a mobile way to participate in it.
Why Ramp’s mobile spending workflow matters
The central capability I noticed is mobile access to business spending activity. Instead of treating the phone as a place to view a balance after the fact, Ramp is designed around the practical work that surrounds company purchases. That changes the experience from passive checking to active handling.
For an employee, this can mean dealing with a work expense while the details are still fresh. For a manager, it can mean staying connected to spending decisions without waiting until returning to a computer. For a finance team, the benefit is less about another screen and more about encouraging people to finish the small steps that make expenses understandable later.
The real advantage is timing: business spending is easier to explain when I record or review it close to the moment it happens. Waiting until the end of a trip or the end of a month creates memory gaps, missing context, and avoidable back-and-forth. A mobile workflow cannot solve every accounting problem, but it can reduce the delay between a transaction and the information attached to it.
This is also where Ramp differs from a typical personal finance app. Personal tools usually emphasize household budgets, account balances, recurring bills, or long-term money habits. Ramp is more relevant to controlled company spending, where the important question is often not “How much money do I have?” but “Can this purchase move through the company’s process cleanly?” That is a narrower job, but it can be a valuable one.
What the app feels like in everyday use
I found the mobile format most useful when I imagined using it between meetings, during travel, or immediately after buying something for work. Those are situations where opening a laptop feels excessive, yet postponing the task makes it easier to forget why the purchase happened. A finance app earns its place on my phone when it handles those short interactions without turning them into a project.
Ramp’s audience should therefore think in terms of workflow, not entertainment or broad financial education. The app is not trying to teach me how to invest or build a household spending plan. It is there to connect business purchases with the people and processes responsible for them.
That distinction also explains why the app may feel limited to someone looking for a complete money-management suite. If my goal is to track personal spending across several banks, compare monthly categories, or plan a private savings target, I would choose a different kind of app. Ramp’s usefulness depends on whether business spending is the problem I actually need to solve.
How I would use Ramp in practice
A realistic example is a work trip. I buy transportation, pay for a meal with a business payment method, and later need to make the expense understandable to the finance team. The best time to deal with the details is not after returning home, when several transactions may look similar. It is while I still remember the meeting, client, or project connected to each purchase.
In that situation, I would open Ramp soon after the transaction, review the item, and complete the relevant business context while it is easy to recall. The practical gain is not dramatic automation; it is reducing the number of loose ends that accumulate during a busy week. A few short mobile actions can be less frustrating than reconstructing an entire trip later.
There is a useful behavioral effect here. When the app is available at the point of need, the person who made the purchase can help create a cleaner record instead of leaving every question for an administrator. That can make responsibility clearer. It also gives finance staff a better chance of understanding an expense without sending repeated messages asking what a vague transaction was for.
For a manager, the same mobile access has a different value. I might be traveling or moving between offices and still need to keep an eye on spending decisions. A phone cannot replace careful review, but it can prevent approvals or checks from becoming dependent on being at my desk. That matters most in small teams, where one delayed decision can hold up someone else’s work.
For an administrator, the app is helpful when it encourages employees to participate in the process rather than treating expenses as paperwork that belongs entirely to finance. The trade-off is that the organization still needs clear internal rules. No app can make an unclear policy clear by itself. If employees do not know which project, purpose, or type of purchase to select, mobile access may simply make confused entries arrive faster.
A workflow tip that makes the mobile approach better
I would use Ramp as a “close the loop immediately” tool rather than opening it only when someone asks for an explanation. After a purchase, I would handle the associated task before switching to the next activity whenever possible. This is a small habit, but it is more effective than relying on memory at the end of the week.
I would also separate urgent review from routine review. A manager may need to respond quickly to a spending decision, while an employee may only need to complete the context around a purchase. Treating every notification as equally urgent can make mobile finance work feel noisy. The better approach is to use the phone for short, time-sensitive actions and reserve deeper analysis for the larger screen when necessary.
Another practical insight is that Ramp works best when the company agrees on naming and responsibility before employees begin using it. Consistent project labels and simple guidance make mobile entries faster. Without that preparation, users may hesitate at every step, and the supposed time saving becomes a series of small decisions.
The best scenario for Ramp
The strongest fit is a business with employees who spend money away from a central office and a finance team that needs timely, organized information. Travel, client work, field operations, and distributed teams are natural examples. In each case, the phone is close to the person making the purchase, while the finance process may be somewhere else.
I can also see value for a growing company where spending responsibility is spreading beyond a small group of founders or administrators. As more people buy equipment, services, meals, or travel, informal messages and spreadsheets become harder to maintain. A focused business spending app can give those purchases a shared place to be reviewed.
The app is less compelling for a very small operation where one person makes every purchase and already knows the full context. In that setting, adding another workflow may not save time. The owner might prefer a banking app, accounting software, or a simple record kept in one familiar place. Ramp becomes more attractive when several people need to interact with the same spending process.
It is also worth thinking about who controls the account. Because Ramp is a business product, the experience depends on the organization’s setup and the role assigned to the user. An employee should not assume that installing the app alone creates access to every function. The company’s account structure determines what the person can do, and that is a normal but important distinction from a personal finance download.
For a remote team, the mobile angle is particularly practical. Someone can finish a spending task from a hotel, a client site, or a train without carrying a laptop everywhere. That convenience is not just about comfort. Faster completion can improve the quality of records because the purchase is still connected to a specific event rather than remembered as a generic charge.
Where the experience has trade-offs
My main reservation is that convenience can encourage shallow review. A phone is excellent for quick actions, but it is not the ideal place to investigate a complicated spending pattern or compare many transactions. If I needed to understand a larger financial picture, I would want a desktop workflow with more space and context. Ramp’s mobile role should complement careful financial work, not replace it.
There is also a learning curve created by business language. Employees who rarely deal with finance systems may not immediately understand why a purchase needs extra context or how their entry affects later review. The app can make the process more accessible, but the organization still has to explain the purpose behind each step. Without that explanation, users may see the workflow as administrative friction.
Another limitation is that the app’s value is tied to adoption across the team. If only some employees use it while others continue sending receipts through email or chat, the company ends up maintaining parallel habits. That weakens the benefit of having one mobile process. I would want a business to decide in advance which tasks belong in Ramp and communicate that decision clearly.
I would also avoid judging the app solely by its rating. Ramp has an average rating of 4.7 from around 2.3 thousand ratings, which suggests that many users find it useful, but ratings cannot tell me whether the workflow fits my company. A finance app can be highly regarded and still be the wrong choice for a freelancer who only needs personal expense tracking.
Support expectations matter too. When a payment or expense is time-sensitive, I want to know who inside the company handles questions and what the escalation path is. The app can put the task on my phone, but it does not remove the need for a responsible finance contact. I would treat that human process as part of the product experience.
Finally, I would check device compatibility before planning a rollout. The current version is 0.160.2 and requires iOS or Android 11 or later. That is reasonable for many modern phones, but an organization with older devices should verify compatibility before telling every employee to depend on the app.
Who gets the most from it
Ramp is best for employees who make legitimate business purchases and want to finish related tasks while the context is fresh. It is also a good match for managers who need mobile access to spending decisions and for finance teams trying to reduce incomplete or delayed expense information.
The app has reached over one hundred thousand installs, and its Everyone content rating makes it broadly suitable from an age-classification perspective. Those details make it approachable, but they do not change the central requirement: the user needs a connection to a participating business account. This is a work tool, not a general-purpose money app for every household.
I would recommend it to a distributed company that wants employees to take more responsibility for the details behind their purchases. I would be more cautious for a business that already has a simple, well-followed process and no meaningful delay in recording expenses. In that case, switching tools may create more training work than value.
I would also skip it if my main need were personal budgeting, bank aggregation, investment tracking, or a simple way to split household costs. A conventional banking or budgeting app would be more natural for those jobs. Ramp is not weaker because it does not cover them; it is simply built around a different kind of financial problem.
For someone deciding whether to try it, my advice is to start with one recurring workflow rather than asking the whole company to change everything at once. A travel expense process or a small group of frequent purchasers is a sensible test. Watch whether people complete tasks sooner, whether finance receives clearer context, and whether managers can act without unnecessary delay. Those results will tell me more than a feature checklist.
At no cost to download, Ramp is easy to consider, but the real investment is organizational: setting expectations, assigning responsibilities, and making the process part of normal work. If those pieces are in place, the mobile experience can turn business spending from an end-of-week chore into a series of manageable actions.
My final view is favorable, with a clear boundary. Ramp is most useful when mobile access changes the timing and ownership of business expenses. It helps people handle spending closer to the moment it happens, which can make records clearer and decisions quicker. It is not a universal finance solution, and it will not fix unclear policies or inconsistent team habits. For the right business, though, that focused purpose is exactly why I would recommend giving it a serious trial.
Pros and Cons
Pros
- Simple interface makes navigation quick and easy.
- Useful for discovering and organizing workout routines.
- Supports goal-focused training for different fitness levels.
- Progress tracking can help maintain motivation over time.
- Convenient access to workouts from a mobile device.
Cons
- Some advanced features may require a paid subscription.
- Workout quality can vary depending on the selected routine.
- Limited guidance may not suit users needing personal coaching.
- Requires consistent input for progress tracking to be useful.
- Not ideal for users seeking highly specialized training plans.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 RampRamp Business Corporation | 4.7 | 100,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Ramp and what can I use it for?
Ramp is a mobile finance and money-management app designed to help users handle everyday financial activities from one place. Depending on your region and account eligibility, it may offer services such as spending management, transfers, payment tools, budgeting features, or access to related financial products. Before downloading, check the official listing to confirm which functions are available in your country and on your device.
Is Ramp available for both Android and iPhone?
Ramp may be available on Android and iOS, but availability can vary according to the country, operating-system version, and the specific Ramp service you want to use. Before installing, review the app-store requirements and confirm that your device is supported. It is also important to download the official application published by Ramp, since similarly named apps or unofficial copies may not provide the same features or security.
Does Ramp require identity verification or personal information?
Because Ramp is associated with financial services, users may be asked to provide personal details and complete identity verification before accessing certain features. This can include your name, contact information, date of birth, address, and identification documents, depending on the product and local regulations. Read the privacy policy and terms carefully, and only submit sensitive information through the official app or website.
Is Ramp free to download and use?
Downloading Ramp may be free, but that does not necessarily mean every service inside the app is free. Depending on your account, location, and the transaction involved, fees may apply for transfers, card usage, currency conversion, withdrawals, subscriptions, or other financial services. Review the current pricing information before using the app, and pay attention to displayed fees and exchange rates before confirming a transaction.
Is Ramp safe to use for managing money?
Ramp should be used with the same care as any financial application. The official app may include security measures such as login protection, device verification, encryption, and transaction monitoring, but no service eliminates every risk. Use a strong, unique password, enable available security features, avoid sharing verification codes, and install updates promptly. If you notice suspicious activity, contact official Ramp support immediately.
Advertisements

Download Ramp
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 0.160.2
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.