


Payday Cash Advance TriceLoans
Trice Loans
Advertisements
App Specs
- Version
- 1.1.6
- Updated
- Nov 1, 2026
- Android Version
- 7.0
- Installs
- 50,000+
- Developer
- Trice Loans
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
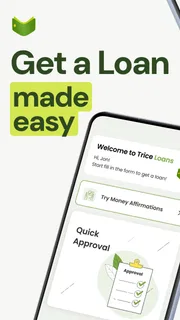
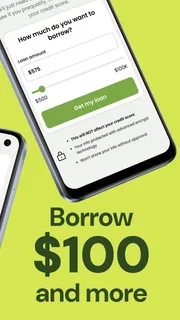
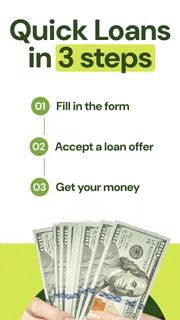
Our Review
 Analysis byUnlimiteds
When an unexpected bill lands between paychecks, the appeal of Payday Cash Advance TriceLoans is easy to understand. This finance app from Trice Loans is built around getting users to a short-term cash advance quickly, with the store positioning it as a fast option that does not require a traditional credit check. After looking at it as a borrowing tool rather than treating it like a general budgeting app, my view is fairly clear: it may be useful for a narrow emergency, but it deserves a much more careful approach than its simple presentation suggests.
The app is free to install and is rated for Everyone, which makes the first step feel approachable. It has reached over 50 thousand installs and holds a 4.7 average from around 7 thousand ratings, so it has attracted meaningful attention. Those figures tell me that the app is not obscure, but they should not be mistaken for a promise that every applicant will receive the same result. A high store rating can describe ease of use, speed, or general satisfaction; it does not replace reading the terms of an individual advance.
What the TriceLoans experience is really suited for
My strongest impression is that this is a focused borrowing app, not a complete financial-management companion. The central task is to help someone explore a payday-style cash advance when cash flow is temporarily tight. That distinction matters. If you are looking for spending categories, long-term savings plans, investment tools, or a detailed debt payoff system, this is not the kind of product I would put at the center of your finances.
The “no credit check” wording is also something I would interpret carefully. It can make an application seem less intimidating, especially for someone with limited credit history or past credit problems. However, no credit check does not mean no eligibility review, no repayment obligation, or no cost. A lender can use other information when deciding whether to offer money and on what terms. I would treat the app as a way to review a possible offer, not as an automatic approval machine.
In practical use, the most important part is not tapping through the application quickly. It is slowing down when the offer appears. I would check the amount deposited, the total repayment, the repayment date, any applicable fee, and what happens if the payment cannot be made on time. A short-term advance can solve today’s problem while creating a larger problem next week if the repayment is not already accounted for.
That is the first non-obvious trade-off with this type of app: speed has value only when the repayment plan is equally clear. A fast application is helpful during an emergency, but speed can also encourage an impulsive decision. I recommend preparing a simple note before applying: current balance, next paycheck, essential bills before that paycheck, and the exact amount that can safely be repaid. If the numbers do not work without borrowing again, the advance is probably not solving the underlying issue.
A realistic emergency scenario
Imagine that a car is needed for work and a necessary repair appears just before payday. An app like this may be worth considering if the repair is genuinely urgent, the amount requested is limited, and the next paycheck can cover the repayment without interfering with rent, food, utilities, or transportation. In that situation, the convenience is understandable: the user can investigate an option from a phone instead of visiting a branch or waiting for a conventional loan process.
But the same app is a poor fit if the repair is only one of several unpaid expenses, or if the user already relies on advances to bridge every pay period. Borrowing for a recurring shortfall can turn a one-time fee into a repeating cycle. In that case, I would look first at negotiating a bill date, asking the service provider about a payment arrangement, speaking with a trusted credit union, or seeking free debt advice. Those alternatives may take more effort, but they can be safer than repeatedly extending a short-term gap.
Where it feels stronger than ordinary alternatives
Compared with visiting a bank for a conventional personal loan, the main attraction is convenience. A bank loan may involve a longer review, stricter credit expectations, and a larger formal application. TriceLoans is aimed at a much more immediate need, and its store summary emphasizes a cash advance rather than a lengthy borrowing relationship. For someone who needs to investigate a small, short-term option outside normal banking hours, that focus is useful.
It may also feel more accessible than relying on a credit card cash advance. A credit card can be convenient, but it may encourage a balance to remain open for months, while a payday-style product is designed around a shorter repayment window. That does not automatically make the app cheaper or better. The right comparison is the total cost and the consequences of missing payment, not simply how quickly money becomes available.
Compared with a budgeting app, the difference is even more important. A budgeting app helps identify why money is running short and can support a longer-term plan. TriceLoans addresses the immediate funding request instead. I would use a budget or banking tool alongside any borrowing decision, because the advance itself does not remove the need to understand upcoming expenses.
One useful workflow is to open the app only after checking alternatives that do not create new debt. Contacting a utility company before the due date, asking a medical provider about installments, or requesting a short extension from a biller can sometimes protect cash flow without adding a loan repayment. If those options fail, then the app can be used to compare the offered terms against the cost of the original problem.
The details I would inspect before accepting anything
I would not judge an offer by the amount shown at the top of the screen. The amount received may not be the same as the amount repaid, especially when fees or other charges are involved. I would write down both numbers and calculate the difference in plain dollars. That small habit makes the cost visible and prevents a “small” advance from being mentally treated as free money.
I would also look closely at timing. A repayment date that seems manageable today may collide with rent, insurance, groceries, or another automatic payment. The key question is not whether the next paycheck is larger than the advance. It is whether enough remains after essential commitments are paid. If the answer is uncertain, I would not accept the offer simply because the application was easy.
Another practical tip is to save the offer details for your own records before completing the process. I would keep the amount, repayment date, total due, and any customer-service instructions together in a note. This is especially useful when several financial apps are installed on the same phone, because it prevents confusion between a requested amount and the amount actually owed.
The app includes in-app purchases priced from $1.99 to $4.99 per item. That makes it especially important to understand what any optional purchase represents before confirming it. I would not assume that an in-app item is part of the advance itself, a required service, or a substitute for reviewing borrowing costs. Any payment screen deserves the same attention as the loan offer: read the label, check whether it is optional, and make sure it is relevant to the decision you are making.
The main weakness: convenience can hide financial complexity
The meaningful weakness is not that the app makes borrowing accessible; accessibility can be valuable. The weakness is that a streamlined mobile experience can make a serious financial commitment feel like a routine checkout. The fewer obstacles there are between a cash shortage and an application, the more discipline the user has to supply personally.
I would also be cautious about the phrase “instant cash advance.” In everyday language, it suggests certainty and immediate access. In reality, an application still depends on the app’s process and the terms presented to the individual user. I would never plan a time-sensitive payment around money that has not actually arrived. A pending application is not the same as available cash, and a displayed possibility is not the same as a completed advance.
The current version is 1.1.6, and the app supports Android 7.0 or later. That broad compatibility is helpful for people using older Android phones, although I would still keep the operating system and the app updated when possible. Finance apps handle particularly sensitive tasks, so I prefer using a device with a screen lock, current security updates, and no unnecessary sharing of access to the phone.
Privacy and security habits matter here even though they are easy to overlook. I would download only the genuine app from the official app marketplace, verify that the developer name shown is Trice Loans, and avoid entering financial information through a message or an unfamiliar page claiming to represent the service. I would never send a password, one-time code, or banking credential to someone who contacts me outside the normal app process.
Who should consider it, and who should skip it
I see the best audience as an adult who has a specific, temporary cash gap, understands the repayment date, and has already checked less expensive alternatives. The app may be worth investigating when the requested amount is modest relative to the next paycheck and the expense is genuinely necessary. Even then, I would compare the full repayment obligation with every available alternative before accepting anything.
I would advise skipping it if the advance is intended for discretionary shopping, gambling, a vacation, or an expense that can safely wait. I would also avoid it when the user is already behind on several bills, has no emergency buffer at all, or expects to use another loan to repay this one. Those situations point to a broader cash-flow problem, and another short-term obligation may make the pressure worse.
It is not my first recommendation for someone who wants to build credit, either. The store summary focuses on access to a cash advance, not on long-term credit development. Someone whose main goal is improving financial history should compare products specifically designed for that purpose and examine whether payments are reported, what fees apply, and what happens over time. A payday-style advance should not be selected merely because a conventional credit product feels harder to obtain.
Likewise, users who need a larger amount or a longer repayment period may be better served by a regulated personal-loan comparison, a credit-union conversation, or a structured payment plan with the creditor. The right alternative depends on the situation, but the principle is simple: match the product to the problem. A short-term app-based advance is not a universal replacement for a longer-term loan, a negotiated bill, or a proper emergency fund.
My final view after weighing the convenience against the risk
My recommendation is conditional: use TriceLoans as an option to investigate, never as a default response to being short of money. Its appeal is clear. It is free to install, designed for a quick cash-advance request, accessible on older Android versions, and presented in a straightforward way for people who may not want a traditional credit-check process. The strong store rating and growing install base suggest that many users find the experience approachable.
Still, approachability is not affordability. The important decision happens after the initial application, when the exact repayment obligation and timing become clear. I would accept an advance only when I could explain the total cost, identify the repayment source, and show that essential bills would remain covered. If I could not do all three, I would close the app and pursue a payment arrangement or other form of assistance instead.
For a carefully planned, one-off emergency, this finance app can be a practical place to explore a short-term solution. For recurring financial stress, it is the wrong tool because it treats the symptom rather than fixing the gap. That is the honest balance: the app may save time in a genuine emergency, but the user must supply the caution that the fast format does not provide.
In the end, I would recommend it only to readers who are comfortable comparing terms and resisting pressure to borrow more than necessary. Everyone else should start with a budget check and a conversation with the biller before taking on a new obligation. The app can be useful, but only when convenience remains subordinate to a repayment plan that already makes sense.
Pros and Cons
Pros
- Quick application process with minimal paperwork
- Clear repayment schedule shown before accepting an offer
- Useful for comparing short-term borrowing options
- Mobile-friendly interface works well on smaller screens
- May help cover urgent expenses when other options are unavailable
Cons
- Short repayment periods can make installments difficult to manage
- Total borrowing costs may be high compared with traditional loans
- Approval and terms can vary based on personal financial information
- Not all applicants may receive an offer after completing the form
- Sharing sensitive financial details requires careful privacy review
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Payday Cash Advance TriceLoansTrice Loans | 4.7 | 50,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Payday Cash Advance TriceLoans?
Payday Cash Advance TriceLoans appears to be a financial service or app designed to help users explore short-term borrowing options, such as payday advances or installment loans. Before downloading or submitting an application, review the provider’s official terms carefully. The app may connect applicants with lenders rather than provide the loan directly, and approval, rates, fees, and repayment conditions can vary according to your location and financial profile.
Is Payday Cash Advance TriceLoans available to everyone?
Availability is usually subject to eligibility requirements, including age, residency, income, employment status, an active bank account, and the ability to repay the requested amount. Requirements may differ by state or country, and submitting an application does not guarantee approval. Users should confirm that the service operates in their area and read its privacy policy before entering personal, employment, or banking information.
How much does a loan through TriceLoans cost?
The total cost depends on the lender, loan amount, repayment period, and applicable local regulations. Short-term loans can carry significantly higher fees or annual percentage rates than traditional bank loans, and additional charges may apply for late or unsuccessful payments. Do not rely only on a payment estimate shown in the app; check the final agreement for the APR, finance charges, due dates, and total repayment amount.
How quickly can I receive money after applying?
Processing times are not guaranteed and can depend on identity verification, lender review, banking hours, weekends, and the method used to deliver funds. Some applications may receive a decision quickly, while others require additional documentation or may be declined. Even after approval, a bank transfer can take additional time. The app should not be treated as a dependable solution for an immediate emergency.
Is it safe to provide my personal information in Payday Cash Advance TriceLoans?
Any loan application may request sensitive details such as your name, address, income, identification information, bank account data, or Social Security number. Before continuing, verify that you are using the official app or website, inspect the developer and permissions, and read the privacy policy. Avoid services that demand upfront payment, request unnecessary access, or promise guaranteed approval without reviewing your financial circumstances.
Advertisements

Download Payday Cash Advance TriceLoans
Unlimiteds is available from its official store. We do not host or distribute app downloads.
About This Listing
- Last Checked
- Nov 1, 2026
- Version Reviewed
- 1.1.6
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.