


Payday Advance Borrow Money
Shpuryk Sergii
Advertisements
App Specs
- Version
- 1.2.1
- Updated
- Nov 6, 2026
- Android Version
- 5.0
- Installs
- 100,000+
- Developer
- Shpuryk Sergii
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
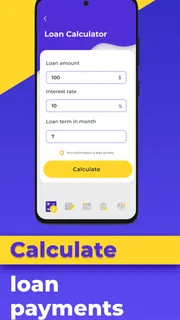
Our Review
 Analysis byUnlimiteds
When a bill arrives before payday, the hardest part is often not finding an app but deciding whether borrowing is the sensible option at all. I approached Payday Advance Borrow Money as a decision tool rather than a promise of effortless cash. Its purpose is to help people look for a suitable payday cash advance, and that makes it most relevant when the need is short term, clearly understood, and supported by a realistic repayment plan.
This is a free finance app from developer Shpuryk Sergii, with an average rating of 4.7 from around 3.2 thousand ratings. It is listed for everyone, so the presentation is aimed at a broad audience rather than a specialist financial user. I would still treat the age label as a description of the app’s audience, not as advice that borrowing is appropriate for every person.
How I would decide whether it fits
The first question is not whether the app can help locate an advance. It is whether the advance solves a temporary timing problem or hides a permanent gap in your budget. If I needed to cover an essential expense and already knew exactly when the money would be available, this type of tool could be useful for comparing a possible short-term route. If I was repeatedly short before every payday, I would see that as a warning sign and look for budgeting help or debt advice instead.
I would also separate the app from the lender that might eventually provide an offer. The application can be a starting point for finding a suitable option, but the important decisions still concern the actual lender: total repayment, due date, late consequences, eligibility, privacy terms, and whether the arrangement is affordable. I would read those details on the final offer rather than assuming that an app’s simple search experience makes the borrowing simple.
My practical test would be straightforward. Before opening the app, I would write down the amount needed, the date it must be paid, and the money that will remain after normal essentials. That small exercise prevents a common mistake: choosing an advance based on the amount available instead of the amount that can safely be repaid. It also makes the app more useful because I can judge results against a real limit rather than browsing out of anxiety.
Another decision point is urgency. A person facing a same-day utility cutoff, medical expense, or necessary repair may value speed more than a long comparison process. Someone planning a nonessential purchase should probably wait. The convenience of a finance app can make borrowing feel less serious than it is, so I recommend using it only after deciding that the expense itself is unavoidable.
What the experience is good at
The strongest idea here is focused discovery. Instead of treating every financial product as interchangeable, the app is built around payday cash advances. That narrow purpose can be helpful when I already understand the kind of short-term borrowing I am considering and want a direct route to possible options. It is less distracting than a broad money-management app if the immediate task is simply to investigate an advance.
I also like the possibility of using it as a screening step rather than rushing into an agreement. I would compare the repayment date with my income calendar, check the full cost, and then close the app if the numbers did not work. That is a better workflow than applying first and asking whether the loan is affordable afterward. The app’s value is therefore partly in the discipline it encourages around the search.
A useful, less obvious habit is to take notes outside the app while comparing choices. I would record the amount received, the amount repaid, the due date, and any consequences connected with missing it. This avoids relying on memory when several offers look similar. It also makes it easier to explain the decision to a partner or family member before committing.
For a realistic everyday situation, imagine that a necessary appliance stops working a few days before salary arrives. I would first check whether a repair, a payment arrangement, or help from an existing emergency fund could solve the problem without new debt. If none worked, I could use this app to explore a payday advance, then compare the repayment obligation with the next paycheck after rent, food, transport, and other fixed costs. If repayment left no breathing room, the correct result would be to keep looking for a different solution, not to select the largest available amount.
The app is also approachable for people who do not want a complicated financial dashboard. Its store presence shows meaningful adoption, with more than one hundred thousand installs, and the current version is 1.2.1. It supports Android devices running version 5.0 or later, which makes it accessible on many older phones. That broad compatibility is useful for someone who does not own a recent handset, although an older device should still be kept updated and protected before entering sensitive financial information.
Where the simple approach has limits
The focused purpose is also the main limitation. This is not the kind of tool I would choose for building a full monthly budget, tracking spending over time, planning investments, or improving credit habits. A banking app may be better for seeing actual balances, while a dedicated budgeting app may be better for identifying why money runs short. Those alternatives address the cause; this app addresses the search for a particular type of borrowing.
I would not assume that a convenient result is the cheapest result. Payday advances can be expensive compared with ordinary bank credit, a credit-union product, an employer-supported option, or an existing emergency fund. The right comparison is the total amount repaid, not just the amount deposited. A smaller advance with a manageable repayment can be safer than a larger one, even if the larger offer appears more helpful at first.
There is also a behavioral risk. A search tool can encourage repeated borrowing if I return to it whenever the next payday feels too far away. I would set a personal rule before using it: one clearly defined emergency, one repayment plan, and no new advance to cover the previous one. If that rule cannot be followed, I would skip the app and seek non-borrowing support.
Another point that deserves attention is the difference between an application and approval. Finding a possible advance does not guarantee eligibility, timing, or acceptance. I would expect the final provider to assess its own requirements and present its own terms. That means I would avoid making a promise to a biller based only on the hope that an application will succeed.
Because the app is free, there is no purchase price for trying it. That does not mean the financial decision is free. The real cost appears in the terms of any advance reached through the process. I would never treat “free to download” as evidence that borrowing will be inexpensive, and I would be particularly cautious about any unclear fee, automatic repayment arrangement, or penalty wording.
How it compares with the usual alternatives
Compared with asking a bank about a personal loan, a payday-advance search app may feel more direct when the need is small and tied closely to the next paycheck. A bank product may be preferable when I need a longer repayment period, a lower overall cost, or a more established relationship with a financial institution. The trade-off is that a bank process may not match the urgency or short-term focus that led someone to open this app.
Compared with a credit union, this app may be easier for initial exploration because it is available as a focused mobile tool. A credit union or community lender may offer a more personal review and potentially a product designed for members facing short-term pressure. I would investigate that route before accepting a payday advance, especially if the expense is larger than a single pay cycle can comfortably absorb.
Compared with borrowing from a friend or family member, the app offers a formal route that does not depend on a personal relationship. That can matter when privacy or independence is important. The downside is that formal borrowing can carry fees and strict repayment consequences, while an informal arrangement might be more flexible if both sides agree clearly. I would not choose one automatically; I would compare the financial and personal costs honestly.
Compared with an overdraft or credit card, the best choice depends on the terms already available to me. An existing facility can be cheaper or more convenient, but it can also create a balance that lingers and accumulates charges. A payday advance may have a clearer end point but a more demanding deadline. I would calculate the total repayment in each case and avoid choosing based only on which option appears fastest.
Finally, compared with a budgeting app, this product is aimed at the immediate funding question rather than long-term prevention. I would use a budget tool after the emergency to find the recurring pressure behind it. The best outcome is not becoming highly efficient at taking advances; it is reaching a point where an unexpected bill no longer requires one.
What switching away would involve
Moving to another option is not difficult technically, but it can require more effort in decision-making. A bank or credit union may involve account checks, eligibility questions, or a longer review. Asking an employer about an advance may require understanding workplace rules. Using savings is faster, but it reduces the cushion available for the next emergency. Each alternative has a different kind of cost, and I would include time, privacy, flexibility, and stress alongside the money itself.
If I had already started an application, I would pause before submitting anything final and review the repayment schedule from the actual provider. Switching at that stage could mean abandoning a convenient route, but that is preferable to accepting terms that do not fit. I would also save copies of important confirmations and make a calendar reminder for any agreed payment date. These are simple steps, yet they reduce the chance of forgetting a deadline during a stressful week.
For someone worried about data privacy, I would keep the process limited to what is necessary and read each screen carefully before continuing. I would avoid entering information into an offer that feels unclear or asks for more than I can reasonably understand. The app can help begin a search, but I would judge the final provider separately and never let urgency replace basic caution.
People often ask whether an app like this is suitable for recurring expenses. In my view, no. A recurring rent, food, or utility shortfall calls for a budget change, a payment arrangement, additional income, or professional advice. Repeating short-term advances can turn a temporary bridge into a cycle, particularly when the next repayment is taken from money needed for essentials.
Another practical question is whether it suits someone with an older Android phone. The listed minimum is Android 5.0, so the compatibility range includes older devices. I would still make sure the phone has current security updates available, use a trusted connection, and avoid completing financial steps on a shared device. Compatibility makes installation possible; it does not remove the need for safe device habits.
My recommendation for the right user
I recommend Payday Advance Borrow Money cautiously to someone who has a specific, short-lived cash need, knows the exact repayment source, and is willing to compare the complete cost before accepting anything. Its free access, clear finance focus, and broad Android compatibility make it a practical place to begin an investigation. The strong 4.7 average also suggests that many users have found the experience useful, though a rating should never replace reading the terms of an individual advance.
I would not recommend it as a routine way to manage monthly spending, as a substitute for a bank or credit union when lower-cost credit may be available, or as a solution for debt that is already difficult to repay. In those situations, the better choice is usually to address the budget problem directly and seek advice before adding another obligation.
My best tip is to decide the repayment limit before searching, then reject any option that exceeds it. My second is to compare the total repayment rather than the advertised advance amount. My third is to use the app once as a controlled search, not as a standing emergency button. Those habits matter more than speed because they keep the tool in its proper role.
Overall, I see this as a focused doorway into payday-advance options, not a complete financial safety net. It can save time when a short-term need is genuine and the numbers are already understood, but it cannot determine affordability for me. If I could repay comfortably and had ruled out safer alternatives, I would consider trying it. If repayment depended on another loan, another advance, or skipping essentials, I would close it and choose a different path.
For that reason, my final view is positive but deliberately measured: use it for comparison, read the final terms with care, and keep the borrowing event exceptional. The app is most helpful when it supports a decision I have already thought through, rather than making the decision on my behalf.
Pros and Cons
Pros
- Quick access to short-term cash for urgent expenses.
- Simple application process with minimal paperwork.
- Loan options may be available to users with limited credit history.
- Clear repayment dates can help with short-term budgeting.
- Funds may be deposited directly into a linked bank account.
Cons
- High fees and interest can make borrowing very expensive.
- Short repayment periods may create pressure on your budget.
- Late payments can lead to extra charges or collection activity.
- Approval and loan terms may vary by location and eligibility.
- Repeated borrowing can contribute to a cycle of debt.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Payday Advance Borrow MoneyShpuryk Sergii | 4.7 | 100,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Payday Advance Borrow Money?
Payday Advance Borrow Money is a financial app designed to help users explore and request short-term cash advances through a mobile device. After installing it, users can review the available borrowing options, enter personal and financial information, and check the repayment terms before submitting a request. Approval, loan amounts, fees, and interest rates may vary depending on eligibility and the lender’s policies.
How does the borrowing process work in the app?
The process generally starts with creating an account and completing an application that may request identity, employment, income, banking, and contact details. The app or its lending partners then review the information to determine whether an offer is available. Before accepting anything, carefully read the annual percentage rate, finance charges, repayment schedule, late-payment rules, and any automatic-debit authorization.
What are the costs and risks of using Payday Advance Borrow Money?
A payday advance can be convenient in an emergency, but it may be expensive compared with other forms of credit. Depending on the offer, you could encounter origination fees, service charges, high interest, rollover costs, or late-payment penalties. Borrowing more than you can repay may lead to repeated extensions, overdraft fees, or damage to your financial situation, so compare the total repayment amount first.
Is Payday Advance Borrow Money safe and legitimate to use?
Before providing sensitive information, verify the app’s developer, privacy policy, customer-support details, lender disclosures, and permissions requested on your device. A trustworthy service should clearly explain who provides the loan, how data is shared, and what consumer protections apply. Avoid services that guarantee approval, demand upfront payment, hide the lender’s identity, or pressure you to accept an offer immediately.
What should I check before downloading or accepting an offer?
Check whether the service operates legally in your country or state, because payday lending rules differ widely and may not be available everywhere. Read recent user reviews, confirm the app’s official download source, and examine the repayment date and total cost. Make sure your income can cover the payment without affecting rent, utilities, food, or other essential expenses.
Advertisements

Download Payday Advance Borrow Money
About This Listing
- Last Checked
- Nov 6, 2026
- Version Reviewed
- 1.2.1
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.