


MyCard - Contactless Payment
Road Dogs
Advertisements
App Specs
- Version
- 1.21
- Updated
- Nov 1, 2026
- Android Version
- 5.0
- Installs
- 10,000+
- Developer
- Road Dogs
- Category
- Finance
- Content Rating
- Everyone
- Price
- $17.99
Screenshots
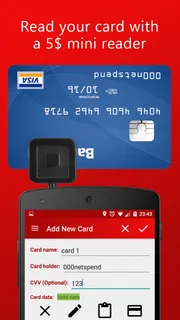
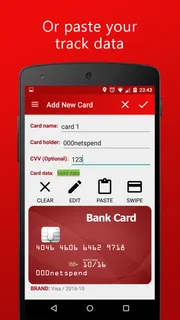
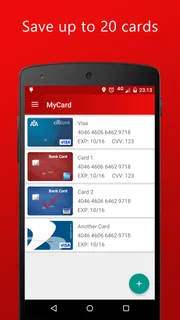
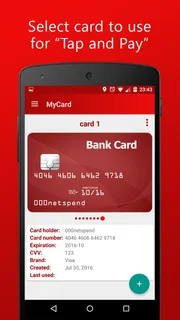
Our Review
 Analysis byUnlimiteds
I find contactless payment most useful when it removes a small daily snag: getting a phone out instead of searching through a bag for a wallet. That convenience is the appeal of MyCard - Contactless Payment, a finance app from Road Dogs. It is presented as a way to use a phone for card-style payments, but the practical question is whether it fits your bank, device, and usual places to pay. I would treat those checks as part of deciding whether it is right for you, rather than assuming that a tap-to-pay app will work identically everywhere.
Where setup can become a sticking point
Setting up a payment app can feel simple right up to the moment it asks you to connect a card or complete a verification step. The important thing is to follow the prompts carefully and use details that match your financial account. If a step does not work, I would pause and check the information rather than repeatedly submitting it; a mismatch or a bank-side check can be the obstacle, not the phone itself. Payment apps depend on more than a clean interface, so a short setup process does not guarantee that every account is ready to use.
Before relying on it for a purchase, I would confirm that the card and account I intend to use can actually be added and accepted during setup. I would also make sure the phone is suitable for contactless payments and that its NFC function is available. NFC is the short-range communication that lets a phone interact with a payment terminal. If that setting is disabled or the device lacks the necessary capability, holding the phone near a terminal will not solve the problem. These basic checks are more useful than troubleshooting the app at checkout.
Getting a dependable tap-to-pay routine
Once setup is complete, I would test the routine somewhere low-pressure before making it my only way to pay. A small purchase gives you a chance to learn how the phone needs to be positioned and whether you need to open or unlock anything first. I would not assume the same motion works on every device or terminal. Keep your physical card nearby on the first few outings, then decide whether the phone is dependable enough for your normal errands.
For example, imagine stopping for coffee on the way to work. If your phone is already in your hand, a contactless payment can be quicker than taking out a wallet, especially when the queue is moving. But if the phone is nearly out of battery, the terminal is having trouble, or you are unsure whether the payment registered, the convenience can disappear quickly. My practical tip is to wait for the terminal’s confirmation before moving away, and to check your account through your usual banking channel if the result is unclear. That avoids accidentally trying the same purchase again.
A second useful habit is to keep a backup payment method available, particularly while you are still learning how the app behaves in your routine. This is not a knock against phone payments; it is sensible planning for any single point of failure. A physical card can cover a dead battery, a device issue, or a terminal that does not cooperate. If you depend on contactless payment for a commute or a quick lunch break, having that fallback can prevent a minor technical snag from becoming a problem.
When a payment does not go through
If a tap fails, I would first separate a phone problem from a terminal or account problem. Check that NFC is enabled, the phone is positioned close to the reader, and the terminal is ready for payment. If the terminal still declines it, try the backup card or another accepted payment method rather than holding the phone against the reader repeatedly. A decline can come from the card issuer or the merchant’s equipment, and repeating the same attempt is not a reliable fix.
If the app appears stuck, closing and reopening it or restarting the phone can be a reasonable general troubleshooting step. Before doing that, note what the terminal displayed so you can distinguish a completed payment from an unsuccessful attempt. If your account shows a charge but the purchase was not completed, contact the relevant bank or payment provider through its normal support route; the merchant’s terminal and the account record matter more than guessing from the phone screen. I would avoid deleting or reinstalling a payment app as a first reaction, since that may mean repeating setup without addressing the underlying issue.
It is also worth checking the basics before leaving home: a working phone, enough battery for the trip, and a backup way to pay. These are small habits, but they matter more for a payment tool than they do for an app you can simply open later. A tap-to-pay routine is only convenient when the device is ready at the moment you need it.
Choosing it over familiar payment options
Compared with carrying a bank card, paying by phone can reduce the need to take out a wallet, but it adds reliance on the phone’s battery, settings, and successful setup. Compared with cash, a mobile payment is quicker when the shop supports contactless terminals, yet cash remains a straightforward fallback where electronic payment is inconvenient. A bank’s own payment option may be a more natural choice for someone who wants card management and payment support in one place. I would choose based on which method works consistently with the accounts and shops I already use, not on the assumption that a newer method is automatically better.
This app is most appealing to someone who already prefers paying by phone and wants a focused way to make contactless transactions. It is less suitable for a person who rarely uses contactless payment, does not want to troubleshoot device settings, or needs a payment option that works without a charged phone. It may also be the wrong pick if your card cannot be linked during setup. In those cases, a physical card or the payment method offered by your bank is the simpler choice.
Cost is another part of the decision. At $17.99, I would want the app to fit a regular payment routine rather than install it for occasional use. That price makes it worth checking compatibility and setup before treating it as a casual experiment. It has an Everyone age rating, a 4.0 average from 285 ratings, and over 10K installs, which offers some context about its audience but does not tell me whether it will work with a particular person’s card or phone. I would weigh those figures alongside the practical fit, not use them as a substitute for it.
What I would check before depending on it
MyCard is currently at version 1.21 and runs on Android 5.0 or later. Those details can help Android users decide whether their operating system is within the stated range, but they do not replace checking that NFC is available on the device. The app was released on March 22, 2016, and is developed by Road Dogs. For a payment app, the useful question is less about how long it has been around and more about whether setup works with your current phone and payment account.
I would also think about how you handle payment records. If you regularly review purchases through your bank’s app or statements, keep using that as your dependable record rather than assuming a payment tool should replace your usual account checks. If you are trying to understand spending, a consistent habit of reviewing transactions is more valuable than installing an app and expecting it to change your budget by itself. That is especially true when your purchases are split between cash, cards, and phone payments.
One realistic way to assess fit is to use it for a few ordinary errands while keeping your normal payment method with you. Notice whether the checkout process feels quicker, whether you can complete setup without confusion, and whether the payment record is easy enough to verify afterward. If those steps feel smooth, the phone can become a convenient part of your routine. If you keep reaching for a card because the app or terminal slows you down, there is little reason to force the change.
Getting Started with MyCard
At first glance, setting up MyCard - Contactless Payment is a breeze. After downloading it from your preferred app store, the installation process guides you through linking your existing bank accounts or credit cards. It's pretty straightforward, and within minutes, you're all set to make your first contactless payment. The user interface is intuitive, which I appreciated because who wants to spend hours figuring out how an app works?
Smooth Transactions
One of the standout features of MyCard is its ability to perform transactions quickly and securely. Whether you're buying a morning coffee or paying for groceries, just a simple tap with your phone is all it takes. I found this incredibly handy, especially when you're in a rush and don't want to fumble around with cash or cards. Plus, the app provides instant notifications after each transaction, so you can keep track of your spending effortlessly.
Security Features
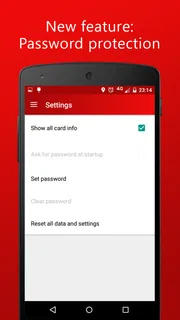
In a world where digital security is paramount, MyCard doesn't skimp on the necessary protections. With robust encryption and biometric authentication options, you can rest assured that your financial data is safe from prying eyes. I particularly liked the fact that it offers real-time fraud detection, which adds an extra layer of security and peace of mind.
Additional Perks
Aside from its primary function of facilitating contactless payments, MyCard comes with a few extra bells and whistles. For instance, you can easily track your spending habits with detailed analytics provided within the app. This feature is perfect for those of us who are trying to budget better and want a clear view of where our money is going. Additionally, there are personalized offers and discounts based on your spending patterns, which is a nice touch.
Overall, MyCard - Contactless Payment is a solid choice for anyone looking to streamline their financial transactions. Its ease of use, coupled with top-notch security features, makes it a must-have app for those who value convenience and safety. If you're ready to ditch the clutter of physical cards and embrace the future of contactless payments, give MyCard a try and see how it can simplify your life. You might just wonder how you ever managed without it!
Pros and Cons
Pros
- Seamless contactless payments
- User-friendly interface
- Quick setup process
- Supports multiple cards
- Secure transactions
Cons
- Limited to certain locations
- Requires internet connection
- Compatibility issues on some devices
- No cash back rewards
- Occasional app crashes
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 MyCard - Contactless PaymentRoad Dogs | 4.0 | 10,000+ | $17.99 |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is MyCard - Contactless Payment?
MyCard - Contactless Payment is an innovative mobile application designed to facilitate easy and secure contactless payments. Users can link their credit or debit cards to the app and make transactions by simply tapping their phone on a compatible payment terminal, eliminating the need for physical cards.
How secure is MyCard for making payments?
Security is a top priority for MyCard. The app uses advanced encryption and tokenization technologies to safeguard your financial data. It also incorporates biometric authentication methods, such as fingerprint scanning or facial recognition, to ensure that only authorized users can access and make payments using the app.
Can I use MyCard internationally?
Yes, MyCard can be used for international transactions wherever contactless payment is supported. However, it's important to check with your card issuer regarding any foreign transaction fees that might apply. Additionally, ensure that your mobile device has roaming capabilities if you're using the app outside your home country.
What devices are compatible with MyCard?
MyCard is compatible with most modern Android and iOS devices that support NFC (Near Field Communication) technology. Users should ensure their smartphones have the necessary hardware and software updates to use contactless payment features effectively. Refer to the app's official documentation for a detailed list of supported devices.
How can I troubleshoot issues with MyCard?
If you encounter any issues with MyCard, start by checking your internet connection and ensuring that your app is updated to the latest version. For persistent problems, consult the app's help section or contact customer support for personalized assistance. They can guide you through troubleshooting steps or escalate the issue if needed.
Advertisements

Download MyCard - Contactless Payment
Unlimiteds is available from its official store. We do not host or distribute app downloads.
About This Listing
- Last Checked
- Nov 1, 2026
- Version Reviewed
- 1.21
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.