


MAJORITY: Mobile banking
Advertisements
App Specs
- Version
- 5.14.0
- Updated
- Nov 7, 2026
- Android Version
- 9
- Installs
- 1,000,000+
- Developer
- MAJORITY USA, LLC
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
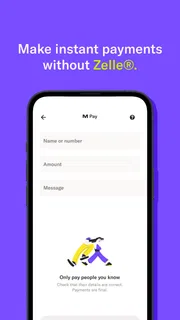
Our Review
 Analysis byUnlimiteds
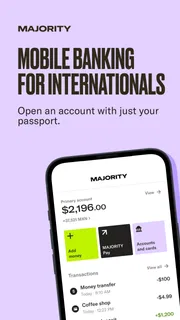
I judge a banking app less by how polished its first screen looks than by what happens when a sign-up step stalls or a transfer needs a second look. MAJORITY is built around a practical mix: access to a US account and debit card without an SSN, alongside ways to send money internationally. That focus makes it especially relevant to people settling into life in the United States or supporting family abroad. In my view, its appeal depends on whether those needs match your own; it is not automatically a replacement for every bank or payment app.
Where people can get stuck
The biggest point to understand before starting is that “without an SSN” does not mean that every person can skip every identity or account-opening step. It describes a distinctive part of the service, not a guarantee that signup will be instant or identical for everyone. I would approach registration with care, read each request on screen, and enter information exactly as it appears on the documents or details being used. If a step does not accept an entry, repeatedly trying different versions can create more confusion than checking the spelling and format first.
The same caution applies to international transfers. Sending money across borders can involve details that need to match the recipient’s situation, and a small typo may matter. Before confirming a payment, I would check the recipient information, the destination, and the amount rather than treating the final screen as a formality. If the app presents a fee, exchange rate, delivery estimate, or other terms for a particular transfer, review those details at that moment; they can be more useful than relying on assumptions based on a previous transaction.
MAJORITY may also be a poor fit if you expect every banking feature you know from a traditional bank to be present in the same way. I would first identify what you need most: receiving money, everyday card use, sending funds abroad, or a broader set of banking services. A focused app can be convenient when it solves a clear problem, but convenience does not make it a universal financial home.
Checks that make setup smoother
Before opening the app, I would make sure the phone has a stable internet connection and enough time to complete the process without rushing. Use your own device if possible, keep the app updated, and make sure you can access any contact method or information that the signup flow asks you to verify. These are ordinary precautions rather than special requirements, but they help separate a genuine account issue from a temporary connection or device problem.
MAJORITY is a free finance app from MAJORITY USA, LLC. It has been available since April 26, 2019, and its current version is 4.0.0, with a minimum operating-system requirement of 9. Its age rating is Everyone. Those details are useful when checking basic compatibility, especially if you are setting it up on an older phone. The app has a 4.8 average from around 17,000 ratings, with roughly 9,000 written reviews and over a million installs. I would treat that popularity as context, not as proof that every feature or signup attempt will work the same way for every user.
One practical setup habit is to pause at each confirmation screen and save yourself a later support conversation: check names, account information, and any transfer details before moving on. I would also keep track of which email address or phone number I used, so I know where to look if I need to recover access. That simple note is especially helpful when a financial app is used alongside several other services with different sign-in details.
Recovering a workflow without making it worse
If signup, login, or a transfer appears to freeze, I would start with the least disruptive checks: confirm the connection, close and reopen the app, and see whether the same screen behaves differently after a short pause. Avoid submitting the same payment repeatedly just because the first attempt does not immediately show a clear result. Check the transaction history or any on-screen status first; duplicate attempts can create uncertainty even when the original action is simply taking time to display.
If a card or account action is involved, separate what you know from what you are guessing. Note the time, the screen you reached, and any message shown, then contact support through the app if the issue remains. A concise report makes it easier to explain the problem: “I reached this step, saw this message, and have not repeated the payment” is more useful than a vague description. I would never send passwords or full sensitive details in an informal message while trying to troubleshoot.
For a transfer, keep the recipient and amount at hand when asking for help, but share only the information the official support flow requests. If a payment is time-sensitive, do not promise a recipient that it has arrived until the app shows a completed status or you otherwise have confirmation. That may feel cautious, but it avoids a common real-world mix-up: one person assumes the transfer is done while the sender is still resolving a pending step.
Using MAJORITY in everyday life
I use this section to think through how MAJORITY might fit into an ordinary week, rather than treating account access and international transfers as separate selling points. A small habit—setting aside money for upcoming expenses before deciding what to send—can make the app easier to use thoughtfully. From there, the next section looks at the practical choices that help determine whether it belongs in your regular financial routine.
A useful routine for cross-border money
Imagine getting paid, setting aside money for rent and groceries, then sending a planned amount to a relative in another country. I would treat those as separate decisions rather than transferring whatever happens to be left in the account. First, reserve the money needed for near-term bills; then check the transfer details and decide what amount is genuinely available. That routine makes an international transfer less likely to collide with an upcoming domestic expense.
The app’s central trade-off is also its clearest strength: it puts a US account and debit card together with international sending, which can reduce the need to jump between unrelated services for those particular jobs. But users should still compare the actual terms shown for a transfer with the alternatives available to them. A bank transfer, a dedicated remittance service, or another payment app may be preferable for a particular destination, timing, or cost. I would compare the amount the recipient is expected to receive and the final terms, not just the convenience of starting the payment from one app.
For day-to-day use, it helps to decide what role the account will play. Some people may want it as their main place for routine spending; others may prefer to use it for receiving or moving money while keeping their existing bank as the hub for savings and bills. The second approach can be a sensible trial: it lets you learn how the app fits your habits without immediately moving every recurring payment. Just remember that splitting activity across accounts requires a little more attention to balances and due dates.
Who is likely to benefit—and who may prefer another option
I would recommend considering MAJORITY if you need a US account without an SSN and value having international money transfers in the same app. It may also suit someone who is new to the US financial system and wants a straightforward mobile-first place to handle a defined set of money tasks. The best reason to try it is a concrete need, such as receiving funds or sending support to family—not simply the vague idea that another finance app might be useful.
On the other hand, if you already have a bank that handles your account, card, bill payments, and international transfers on terms you like, adding another app may not simplify anything. It can mean another balance to monitor, another sign-in to maintain, and another place to check when a payment is unclear. Someone who needs a particular service not central to MAJORITY’s stated focus should compare providers before switching or relying on it as their only account.
I would also be careful about treating any mobile account as a substitute for a personal budget. An app can help organize financial activity, but a screen cannot decide how much you can safely spend or whether a transfer fits your priorities. Before relying on it for a major recurring commitment, make sure you understand how you will fund the account, monitor activity, and handle a problem if you lose access to your phone.
What to check before relying on it
A sensible first use is a small, ordinary task rather than a complicated, urgent one. Once your account is ready, explore the screens and make sure you understand where to review activity and how to reach help. If you plan to send money, take time to verify the recipient and the transaction terms shown in the app. This gives you a chance to learn the workflow before an important deadline or family need makes every delay feel stressful.
People often want to know whether they can start without an SSN, whether they need a particular phone, and whether the app costs anything. The service is specifically described as offering a US account and debit card without an SSN, it supports Android and iOS, and it is free to download. That does not mean every device will be compatible: the minimum operating-system requirement is 9. I would check the phone’s software version and the current signup steps before making plans around immediate access.
Another reasonable question is whether it can replace a traditional bank. My answer is: only if its actual services cover the tasks you personally depend on. The combination of account access and international sending is appealing, but the right comparison is not “app versus bank” in the abstract. Write down the transactions you make in a typical month, then compare which provider supports them and what each transaction costs or requires. If your needs are broader than MAJORITY’s focus, keeping a separate bank account may be the more practical choice.
My practical verdict
In my view, MAJORITY makes the most sense as a purpose-driven mobile banking option for people who need a US account without an SSN and want international transfers close at hand. Its free price and availability on both major mobile platforms make it easy to consider, while its established user base suggests that it is not a niche experiment. Still, those points do not remove the need to check the terms of a specific transaction or confirm that the service fits your own financial routine.
I would approach it with a simple plan: confirm compatibility, complete setup carefully, learn where to review account activity, and test the workflow with a non-urgent task before depending on it for something time-critical. If that routine feels clear and the available services match your needs, it could become a useful part of managing money between the US and home. If you need a wider set of banking tools or already have an arrangement that works smoothly, there is no reason to add another account just for the sake of it.
In today's fast-paced world, managing finances on the go is a necessity, not a luxury. Enter MAJORITY, a mobile banking app designed to cater to the modern user's needs. Whether you're sending money back home, paying bills, or just keeping track of your spending, MAJORITY aims to make your financial life as seamless as possible.
Getting Started with MAJORITY
First off, let's talk about the setup process. Downloading and installing the app is a breeze. Available on both Android and iOS, it doesn't matter what device you're using; MAJORITY has got you covered. The signup process is straightforward, and within minutes, you're ready to take control of your finances.
User-Friendly Interface
Once you're in, the first thing you'll notice is the clean and intuitive interface. Everything is laid out beautifully, making it easy to navigate even for those who might not be tech-savvy. I found myself breezing through the app without any hiccups, which is always a plus in my book. Plus, the app's design is pleasing to the eye, which never hurts.
Features that Stand Out
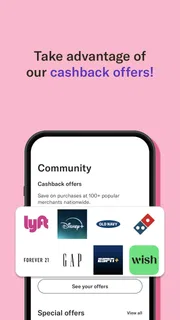
One of the standout features of MAJORITY is its ability to cater to immigrants. It offers a host of services aimed at making life easier for those who have moved to a new country. From free international money transfers to discounts at local stores, it's clear that this app is designed with its users in mind.
Another feature worth mentioning is the budgeting tool. It's perfect for keeping track of your expenses and making sure you don't overspend. The app sends alerts for upcoming bills and low balances, which I found incredibly helpful.
Security and Support
When it comes to mobile banking, security is always a top concern. Thankfully, MAJORITY takes this seriously. With robust encryption and secure login features, you can rest easy knowing your information is safe. And if you ever run into any issues, their customer support is just a tap away. They're responsive and eager to help, which is always reassuring.
In conclusion, if you're looking for a mobile banking app that offers more than just the basics, MAJORITY is worth checking out. Its range of features tailored to immigrants, combined with its user-friendly interface and strong security measures, make it a standout choice in the crowded world of mobile banking apps. Give it a try, and you might just find it becomes an indispensable part of your financial toolkit.
Pros and Cons
Pros
- User-friendly interface for easy navigation.
- Instant notifications for all transactions.
- Supports bill payments and transfers.
- Secure login with biometric authentication.
- 24/7 customer support available.
Cons
- Limited international transfer options.
- Occasional app crashes reported.
- Some features require premium account.
- Slow loading times during peak hours.
- Limited language support options.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 MAJORITY: Mobile bankingMAJORITY USA, LLC | 4.7 | 1,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is MAJORITY and how does it work?
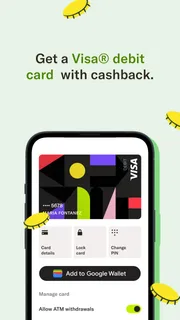
MAJORITY is a digital banking app designed for immigrants, offering a holistic solution beyond traditional banking services. It provides international money transfers, an FDIC-insured account, a Visa debit card, and access to a community of immigrants with special deals and events. The app simplifies financial management by offering services tailored to the unique needs of its users, ensuring a seamless banking experience.
Is MAJORITY safe to use for my financial transactions?
Yes, MAJORITY is safe to use for your financial transactions. The app partners with an FDIC-insured bank to protect your funds up to the legal limit. Additionally, it utilizes advanced encryption and security measures to ensure the safety and privacy of your personal and financial information, making it a reliable choice for managing your banking needs.
Can I transfer money internationally using MAJORITY?
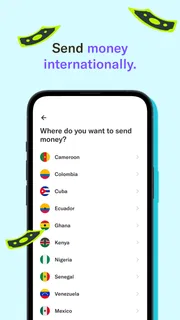
Absolutely, MAJORITY allows users to send money internationally with ease. The app provides competitive exchange rates and low fees, making it an affordable option for international transfers. Whether you need to send money to family abroad or pay for services in another country, MAJORITY supports your needs with efficiency and reliability.
What are the eligibility criteria for opening a MAJORITY account?
To open a MAJORITY account, you need to be at least 18 years old and reside in the United States. The app caters primarily to immigrants, so having a valid government-issued ID and a US address is essential. No Social Security Number is required, making it accessible for those who might face challenges in opening a traditional bank account.
Does MAJORITY offer customer support if I encounter issues?
Yes, MAJORITY provides robust customer support to assist users with any issues they might encounter. The app offers support via phone, chat, and email, ensuring that help is readily available. Additionally, their community-focused approach means users can also find support and answers through engagement with other members, enhancing the overall user experience.
Advertisements

Download MAJORITY: Mobile banking
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 5.14.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.