


Instant Borrow - Cash Now
Advertisements
App Specs
- Version
- 1.0.5
- Updated
- Nov 7, 2026
- Android Version
- 7.0
- Installs
- 500,000+
- Developer
- LM GROUPS
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
When an unexpected bill lands between paydays, the hardest part is often not the amount itself but the time pressure. Instant Borrow - Cash Now is a finance app from LM GROUPS built around that narrow moment: you need to explore a borrowing option quickly rather than spend hours comparing complicated processes. I found its appeal easy to understand, especially for someone who wants a simple mobile starting point instead of visiting a branch or making several calls.
That convenience needs to be viewed carefully. This is a borrowing tool, not free money, and a fast application is not the same thing as guaranteed approval or a suitable deal. My overall impression is that it works best as a focused first step when an urgent expense cannot wait, provided I slow down before accepting anything and check the repayment details properly.
From an urgent expense to a borrowing decision
I’ll use this section to frame borrowing as a decision about timing and affordability, not just a race to find money. Before opening a fast-focused finance app, I find it useful to identify the exact shortfall and when it must be covered; that gives the next section a practical starting point and helps keep urgency from deciding on my behalf.
Starting with the problem, not the app
The most realistic way to use this app is to begin with a clearly defined expense. Imagine a necessary household payment arriving just before your income does. Instead of opening the app with a vague hope of “getting some cash,” I would first write down the exact amount needed, the date the expense is due, and the date I expect to have funds available. That small preparation makes the later decision much safer.
The app’s store summary presents it as a fast way to cover urgent expenses, and that focus is important. It is not the kind of finance product I would open casually for entertainment, long-term investing, or everyday budgeting. Its value is concentrated in short, stressful situations where speed and a straightforward route matter more than extensive financial planning tools.
Because it is free to install and rated for Everyone, the initial barrier is low. The application is available for Android devices running version 7.0 or later, so it can suit people using older compatible phones as well as newer models. Free access is useful, but I would not confuse the absence of an installation charge with the total cost of borrowing. Any offer still needs to be judged by its repayment obligations, timing, and conditions.
What I would prepare before opening it
A smooth borrowing workflow begins before the first screen. I would have my personal details, income information, and a realistic repayment plan ready, while also making sure I am using a private connection and a phone I control. This is not unnecessary caution: rushing through financial forms increases the chance of entering something incorrectly or overlooking an important term.
My most useful preparation tip is to create a simple “can I repay this?” test. Start with the amount that must be returned, then subtract rent, food, transport, utilities, and existing commitments from the income expected before repayment is due. If the remaining money is already tight, a quick application may solve today’s problem while creating a larger one later. In that situation, asking the bill provider for more time or using an established bank facility may be better.
I would also decide in advance what information I am unwilling to guess. If an application asks for a figure I cannot verify, estimating it just to move forward is poor practice. A finance app can make the process feel easy, but the responsibility for accurate information remains with me.
Moving through the application flow
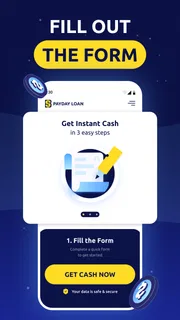
The central experience is designed around borrowing rather than a broad collection of financial tools. I would expect to move from the need for funds toward an application or borrowing request, supplying the information required to assess the request. The attraction is the reduced friction: the phone becomes the place where I start the process, rather than merely a place to read general financial advice.
That simplicity is helpful when concentration is limited. During an urgent situation, a long form with unrelated products and distracting menus can make mistakes more likely. A focused borrowing app keeps attention on the immediate task. I especially appreciate that the concept is easy to explain to another person: open it, review the available route, provide truthful details, and examine the outcome before deciding.
Still, “instant” should be treated as a description of the intended experience, not a promise that every request will finish immediately. The speed of a financial process can depend on the information supplied, eligibility checks, device conditions, and the handoff between the app and the service handling the request. I would never schedule a bill on the assumption that money must arrive at a precise minute simply because the product name emphasizes speed.
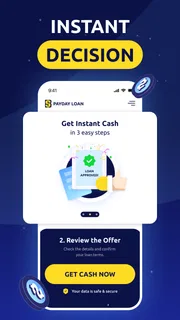
A practical workflow is to pause at every confirmation screen. I would check the requested amount against my original note, read the repayment information, and save a personal record of what I submitted. If the app presents an offer, the important question is not only “How quickly can I receive this?” but also “What exactly will I need to repay, and when?” That shift from urgency to total obligation is the key discipline this type of app requires.
The handoffs that matter
Borrowing rarely ends inside one screen. There is a handoff between me and the application when I submit information, another between the app and the service reviewing the request, and potentially another when funds or repayment instructions move through the relevant financial channel. These transitions are where expectations can become confused.
I would keep notifications available while a request is being processed, but I would not treat a notification as a substitute for reading the full result. A short message may tell me that something changed, while the actual screen contains the amount, timing, or next action that determines whether the offer is useful. If I were helping a friend use it, I would specifically tell them to distinguish an application update from confirmed access to funds.
Another non-obvious point is that the app may be most valuable as a comparison checkpoint, even when I do not ultimately borrow through it. If I already have a bank overdraft, a credit-union option, or help available from the bill provider, I can compare the real repayment burden rather than choosing the first fast-looking route. The app’s speed is an advantage in gathering an option, not a reason to skip alternatives.
This is also where privacy awareness matters. Financial applications involve information that deserves careful handling. I would review each request for details before submitting it, avoid completing the process on a shared device, and remove any screenshots containing sensitive information after I have recorded the necessary dates and amounts. These habits do not slow the process much, but they reduce avoidable exposure.
What a useful outcome looks like
A successful outcome is not simply seeing money become available. For me, it would mean receiving a borrowing option that matches the amount I actually need, understanding the repayment commitment, and knowing how that commitment fits into the next income cycle. If the request is unsuitable, a clear decision not to proceed is also a useful outcome because it prevents an impulsive agreement.
In an everyday scenario, suppose a required repair cannot be postponed. I would use the app to investigate a possible short-term solution, compare the total repayment with the repair’s urgency, and then decide whether the convenience justifies the obligation. If I proceed, I would immediately place the repayment date in my calendar and keep the confirmation details somewhere secure. The app helps with the front end of that process; it cannot replace the budgeting work that follows.
One strength is the low commitment at the discovery stage. Since the app is free, I can install it and see whether its route is relevant without paying merely to access the application. Its broad age rating also makes it approachable for general users, although being allowed to install a finance app does not mean every person will qualify for or benefit from borrowing. Eligibility and affordability are separate questions.
The app has also attracted substantial attention. It has passed half a million installs and holds a 4.7 average from roughly twenty-six thousand ratings, with hundreds of written reviews. Those figures suggest that many people find the basic concept useful, but popularity is not proof that an individual offer will fit my circumstances. I would use the rating as a reason to investigate the app, never as a substitute for checking the terms in front of me.
Where the flow becomes less comfortable
The biggest friction is built into the category itself: urgent borrowing encourages rushed decisions. A clean interface can reduce navigation problems, yet it cannot remove the financial risk. If I am already struggling to cover regular expenses, adding another repayment may be the wrong answer even when the application feels effortless.
There is also a meaningful difference between a fast request and fast access to usable funds. A request can require review, clarification, or a further step outside the app. That is why I would use it earlier in the day when possible, keep a backup plan for the bill, and avoid promising a payment to someone else until the funds are actually available. This is a small workflow change, but it prevents the app’s speed-focused identity from creating false certainty.
Another limitation is that a focused borrowing app is not a replacement for a complete money-management system. I would not choose it if my main need were tracking spending, building savings, monitoring several accounts, or planning debt over many months. A banking app may be better for seeing existing balances, while a budgeting app may offer a clearer view of recurring commitments. A lender I already understand may also be preferable when its terms are transparent and its repayment schedule fits my income.
Version 1.0.5 shows that the product is still a relatively early-stage experience compared with long-established financial platforms. That does not make it unusable, and the release is compatible with Android 7.0 and above, but I would keep my expectations practical. If a screen behaves unexpectedly, a request stalls, or the next step is unclear, I would not repeatedly submit the same request. I would save the status, check the available support route inside the app, and avoid creating duplicate applications without understanding the consequences.
The developer, LM GROUPS, has positioned the product around immediacy, so the best user is someone who values a quick starting point and is prepared to read carefully. The worst fit is someone looking for guaranteed cash, a way to avoid repayment, or a substitute for professional debt advice. It is also a poor choice for a non-urgent purchase that could wait until the next normal income date.
My practical way to use it responsibly
I would follow a five-part routine. First, define the expense and borrow only for the genuine shortfall. Second, calculate what can be repaid without sacrificing essentials. Third, complete the application with verified information rather than guesses. Fourth, inspect the complete offer and record the repayment details. Finally, treat the repayment as a fixed upcoming bill from the moment I accept.
That routine reveals a useful trade-off. The app can save time at the beginning, but it does not save me from making a careful decision. In fact, the faster the initial route feels, the more deliberately I should examine the final commitment. Convenience is valuable when it removes pointless administration; it becomes dangerous when it encourages me to skip comparison or affordability checks.
I would recommend trying it when an urgent expense is real, the amount is clearly known, and repayment is already supported by predictable income. I would first compare it with a bank option, a credit union, an employer advance if available, or a payment arrangement with the company requesting money. The best alternative depends on the actual total cost and timing, not on which screen opens fastest.
For someone asking whether it is worth installing, my answer is cautiously positive. The free entry, focused purpose, broad device compatibility, and strong user response make Instant Borrow - Cash Now a reasonable app to investigate when time matters. I would not install it expecting an automatic solution, and I would not accept an offer without understanding the repayment burden.
My final view is that this is a useful doorway, not a financial safety net. It can turn a stressful search into a more organized borrowing workflow, especially when I prepare the amount and repayment plan beforehand. Its real value appears when speed is paired with restraint: use the app to explore a solution, verify every obligation, keep alternatives in mind, and walk away when the numbers do not fit. The safest result is not the fastest approval; it is a repayment plan I can genuinely keep.
Pros and Cons
Pros
- Quick application process with minimal paperwork
- Clear repayment terms shown before accepting an offer
- Useful for covering unexpected short-term expenses
- Loan options may suit different borrowing needs
- Application can be completed from a mobile device
Cons
- Approval and loan availability may vary by location
- Interest and fees can make borrowing expensive
- Late payments may lead to additional charges
- Requires sharing personal and financial information
- Not suitable as a long-term solution for recurring expenses
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Instant Borrow - Cash NowLM GROUPS | 4.7 | 500,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Instant Borrow - Cash Now, and how does it work?
Instant Borrow - Cash Now is presented as a financial app designed to help users explore short-term borrowing options through a mobile device. After creating an account, applicants may be asked to provide personal, employment, income, and banking information so the service can evaluate eligibility. Available offers, approval decisions, loan amounts, repayment periods, and funding times can vary depending on the user’s profile, location, and participating lenders.
Is Instant Borrow - Cash Now a direct lender?
Not necessarily. Apps in this category may operate as loan-matching or lead-generation services rather than providing the money themselves. Your request could be shared with third-party lenders or service providers that may contact you with offers. Before accepting anything, carefully check the lender’s name, licensing information, annual percentage rate, fees, repayment schedule, and privacy terms. Never assume that submitting an application guarantees approval or funding.
What information is required to apply through the app?
The application may request details such as your full name, address, date of birth, phone number, email address, employment information, income, bank account details, and identification data. This information can be sensitive, so only enter it through the official app or a verified website. Review the privacy policy to understand how your data is collected, stored, shared, and used for marketing or lender matching.
How much does borrowing through Instant Borrow - Cash Now cost?
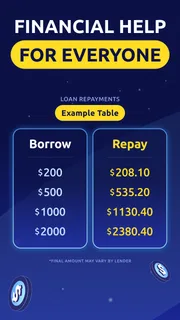
The total cost depends on the lender and the specific offer you receive. Potential costs may include interest, an annual percentage rate, origination or administration fees, late-payment charges, and other service fees. Some short-term loans can be considerably more expensive than traditional credit. Read the complete agreement before accepting an offer, confirm the amount you will repay, and avoid relying on unclear or incomplete pricing information.
Is Instant Borrow - Cash Now safe to use, and what should I check first?
Use caution before submitting financial or identity information. Download the application only from a legitimate store or verified source, inspect the developer details, and read recent user reviews for recurring complaints. Be especially careful if the service requests upfront payment, promises guaranteed approval, pressures you to act immediately, or asks for unnecessary permissions. Also verify lender licensing, data-protection practices, repayment conditions, and customer-support contact details before proceeding.
Advertisements

Download Instant Borrow - Cash Now
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 1.0.5
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.