


Gerald - Cash Advance
Advertisements
App Specs
- Version
- 69.0.13
- Updated
- Nov 7, 2026
- Android Version
- 7.0
- Installs
- 500,000+
- Developer
- Gerald Technologies, Inc.
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
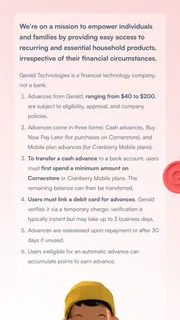
Our Review
 Analysis byUnlimiteds
When an unexpected bill lands before payday, the problem is usually not long-term budgeting; it is the awkward gap between money leaving your account and your next paycheck arriving. That is the situation I focused on when trying Gerald - Cash Advance, a finance app from Gerald Technologies, Inc. Its central appeal is simple: it is designed to help eligible users request cash without a traditional credit check or interest charge. I found that promise useful for a narrow, practical emergency, but it does not turn a short-term advance into free money or remove the need to understand the repayment flow.
The app is free to install and carries an Everyone age rating, which makes it approachable for a broad audience. It has built a sizeable user base, with more than half a million installs, and its average score sits at 4.4 from roughly ten thousand ratings. Those figures suggest that many people find the basic experience worthwhile, although a rating alone cannot tell you whether the service fits your particular income schedule or banking situation.
Following a cash-advance request from need to outcome
I’d treat the request as a small, traceable process rather than a single tap: note the amount, the expense it will cover, and the income event you expect to repay it from. That gives me a clear way to judge whether the advance actually helped, even if the app’s timing differs from my hopes. From there, the key question is how to handle the moments when several money tasks compete for attention.
Starting with the right kind of shortfall
I would not begin with this app simply because I want extra spending money. The more sensible starting condition is a clearly defined, temporary shortage: a utility payment, grocery run, transport cost, or another necessary expense that arrives before money you already expect to receive. That distinction matters because a cash advance can solve timing, but it cannot solve an income problem that repeats every pay cycle.
The store summary presents the service as fast cash with no credit check and no interest. In practical terms, I read that as a reason to investigate the app when a conventional credit product feels excessive, not as a guarantee that every request will be approved or delivered instantly. Eligibility, account connections, verification, and the eventual repayment arrangement all influence what happens after installation.
Before starting, I would have the information needed to identify myself and connect the financial account the app requires. I would also check that the account is active, accessible, and linked to the income pattern I expect to use. This preparation is easy to overlook, yet it is one of the first places a supposedly quick request can slow down. If the app cannot recognize the relevant account activity or the connection needs attention, the urgent part of the problem remains unsolved.
My first practical tip is to decide the repayment source before requesting anything. I would write down the expected incoming date, the amount that must remain available for essential bills, and the amount I can safely return. That small exercise changes the app from an impulse button into a controlled bridge. It also exposes an important trade-off: avoiding interest does not mean the advance has no consequences if repayment collides with rent, food, or another automatic payment.
Moving through the request instead of guessing
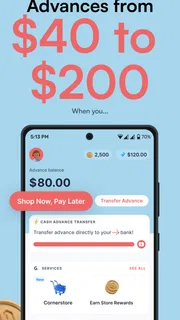
The initial flow is built around opening the app, reviewing the available cash-advance path, and completing the requested account or identity steps. I would read each screen rather than tapping through quickly, especially where the app explains timing, eligibility, and what happens after accepting an advance. Financial apps deserve slower attention than ordinary shopping apps because a missed detail can affect the next handoff.
One useful way to approach the process is to separate three questions. First, am I currently eligible to request money? Second, how much can I responsibly use without creating a larger shortage? Third, how will the repayment fit alongside my existing commitments? The app may help with the first question, but the second and third still require my judgment. That is where many users can make a better decision than they would by focusing only on the headline promise of fast access.
I would also keep the request as small as the situation allows. If the need is a modest grocery purchase, taking a larger advance simply because it appears available increases the pressure on the next income event. A smaller request gives the service a more defensible role and makes it easier to see whether the app is genuinely helping with timing rather than encouraging repeated borrowing.
The absence of a traditional credit check is especially relevant for someone who may not want a conventional loan inquiry to determine access. It can make this type of service feel less intimidating than a bank or credit-card application. At the same time, it should not be confused with an absence of screening. A provider still needs enough information to assess the request and move money safely, so users should expect the app’s process to depend on the financial details and connections they submit.
Understanding the handoffs between the app and my bank
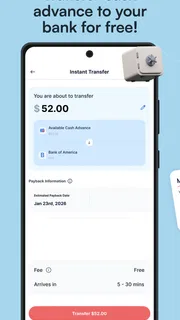
The most important part of the journey is not the bright request button; it is the handoff between Gerald, the user, and the connected financial account. I see the app as the coordinator of that handoff. I begin the request in Gerald, provide the information needed for the service to evaluate it, and then wait for the next step that connects the approved advance with the account or delivery method involved.
That is also where expectations need to stay realistic. “Fast” is useful language for someone facing a deadline, but the actual experience can depend on verification and banking processes outside the app’s direct control. If the request is urgent, I would start it before the bill becomes overdue rather than treating the service as a guaranteed last-minute rescue.
A second non-obvious tip is to monitor the connected account after the request, not just the app’s main screen. The account balance is the place where an incoming advance and a later repayment can affect real spending decisions. I would avoid spending the full balance immediately after seeing money arrive, because the next obligation may already be part of the arrangement. Keeping a small written record of the requested amount and expected repayment is more reliable than trusting memory during a stressful week.
This handoff also explains why the app may suit one person better than another. Someone with a regular income pattern and a stable bank account can use a short-term advance as a predictable bridge. Someone whose income is irregular, whose account frequently changes, or whose essential expenses already consume nearly everything may find the same workflow much harder to manage. The app does not remove those underlying constraints.
What the result feels like in everyday use
Consider a realistic example: I notice that a necessary payment is due several days before my next paycheck. I open Gerald, review whether I can request an advance, complete the required steps, and choose an amount that covers only the immediate gap. Once the money reaches the relevant account or delivery path, I use it for that defined expense rather than treating it as a general increase in my budget. When the paycheck arrives, I make sure the repayment does not compete with the following week’s essentials.
In that scenario, the app’s value is convenience and access. I do not have to turn a small timing problem into a larger traditional credit application, and the no-interest positioning makes the cost easier to understand than a product built around accumulating interest. For a person who can repay comfortably, that can be a meaningful difference.
However, the result is not simply “cash received.” The real result is a shift in timing. Money becomes available now, and the future balance becomes tighter. I would judge success by whether the advance prevented a specific problem without causing another one. If it allows me to keep an essential payment on track and repayment fits naturally into the next income cycle, the workflow has done its job. If I need another advance immediately afterward, the app is probably masking a larger shortfall.
The app’s free price is another reason it may be worth examining before considering a more expensive alternative. Still, I would read the in-app terms carefully and distinguish the absence of interest from the total cost and conditions of using the service. A free download does not automatically mean every possible transaction or optional arrangement has the same financial effect. That is not a criticism unique to Gerald; it is simply the level of care I expect from any financial tool.
Where the flow can break down
The first weak point is eligibility. The app’s description may attract someone who needs immediate money, but access is not something I would assume until the request has passed the app’s own checks. If the service cannot complete verification or identify suitable account activity, the user may end up back at the original problem with less time available to solve it.
The second weak point is timing. A request can feel urgent to me while the financial network involved follows its own schedule. I would not use this as the only plan for a payment that could trigger serious consequences if delayed. A direct conversation with the bill provider, a planned emergency fund, or a conventional bank option may be safer when the deadline is immovable.
The third is behavioral. A no-interest advance can feel harmless because there is no interest meter visibly growing. Yet repayment still reduces future spending power. If I repeatedly use the service for ordinary purchases, the convenience can become a cycle: one advance fills a gap, repayment creates the next gap, and another request follows. Gerald is better suited to occasional timing problems than to ongoing expenses that exceed income.
There is also a comparison to make with familiar alternatives. A credit card may offer a reusable line and wider purchasing flexibility, but carrying a balance can become expensive when interest applies. A bank overdraft may be integrated with an existing account, yet its terms can vary and the consequences of an overdrawn balance may be unpleasant. A personal loan can provide a larger, structured amount, but it is excessive for a small temporary shortage and usually involves a more formal application. A savings buffer remains the cleanest option when available because it avoids creating a future repayment obligation.
Gerald sits in a narrower space between those choices. It is more focused than a general credit card, potentially less burdensome than a loan for a small gap, and more useful than an overdraft when the user wants to explore a dedicated advance flow. It is not a replacement for savings, and it is not the right tool for financing a purchase that I could postpone. That positioning is important: the app’s strength is solving a short bridge, not offering broad financial flexibility.
Who will get the most from it
I think this app is most suitable for an adult who has a foreseeable incoming payment, needs a limited amount for an essential expense, and can review the repayment impact calmly. The Everyone rating makes the product broadly accessible from a content perspective, but financial suitability is a separate question. I would still expect users to be able to understand the terms and manage the connected account responsibly.
It can also be useful for someone who wants to avoid a conventional credit check for a small, short-lived need. That does not make the app a universal answer for people with limited credit history; it simply means the product’s approach may be more relevant than a standard credit application. The best candidate is someone who needs timing assistance, not someone searching for a permanent source of income.
I would advise skipping it when the expected paycheck is uncertain, when several bills are already overdue, or when repayment would require another advance. In those cases, a nonprofit financial counselor, a negotiated payment date, employer support, or a carefully reviewed bank product may address the underlying issue more safely. I would also skip it for discretionary spending. Waiting, saving, or choosing a cheaper purchase is preferable to borrowing for something that is not necessary.
What I noticed about the app’s maturity and maintenance
Gerald has been available since July 2021, and the current version is 69.0.9. I mention that because a financial app’s maintenance history matters to me: users are trusting it with sensitive account activity and time-sensitive decisions. The developer is Gerald Technologies, Inc., and the app’s continued presence alongside its substantial install base gives it the feel of an established product rather than a brand-new experiment.
That said, a mature version number does not remove the need to update carefully or review changes before using the service. I would keep the app current, use a secure device, and avoid beginning a request on an unreliable connection. Those are simple habits, but they matter more when the app is part of a money movement workflow than when it is only displaying information.
I also appreciate that the product is easy to categorize: this is a finance app centered on access to a cash advance, not a budgeting course or a full replacement for a bank account. That clarity helps me set reasonable expectations. I would use it for the specific bridge it offers and keep broader money management—budgeting, saving, bill negotiation, and long-term debt planning—in the tools or conversations designed for those jobs.
My recommendation after following the complete workflow
My overall view is positive but deliberately limited. Gerald - Cash Advance makes sense when a short-term cash gap is the only obstacle, the requested amount is modest, and repayment is already visible on the horizon. The lack of a traditional credit check and the no-interest positioning can make it more approachable than common borrowing alternatives, while the free app and straightforward purpose lower the barrier to investigating it.
I would not recommend opening it with the vague hope that money will solve a recurring monthly deficit. The most important discipline is to define the expense first, confirm that the future repayment fits, and treat every handoff—verification, account connection, delivery, and repayment—as part of the financial decision. That workflow is less exciting than the promise of fast cash, but it is what separates a useful bridge from a repeating problem.
For me, the app earns a place among short-term options rather than becoming my default financial tool. If your situation matches that narrow use case, it is worth considering and comparing with a savings buffer, a direct payment arrangement, or a lower-cost bank option. If your situation is unstable or the advance would only postpone an unavoidable shortage, I would choose a solution that addresses the cause instead. Used with that boundary, Gerald can be practical; used without it, its convenience may become the very friction it was meant to remove.
Pros and Cons
Pros
- Simple application process with minimal paperwork required.
- Can help cover urgent expenses before your next paycheck.
- Repayment terms and fees are shown before accepting an offer.
- Useful for users who prefer managing finances from a mobile device.
- May provide access to multiple borrowing options in one place.
Cons
- Availability and loan offers may depend on your state and eligibility.
- Cash advances can become expensive if fees or tips are applied.
- Repayment may be scheduled quickly
- leaving little time to budget.
- Approval is not guaranteed after submitting your personal information.
- Late or missed payments could lead to additional costs or financial stress.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Gerald - Cash AdvanceGerald Technologies, Inc. | 4.4 | 500,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Gerald - Cash Advance, and how does it work?
Gerald is a financial app designed to provide eligible users with access to cash advances and other money-management features. After creating an account and completing the required identity and financial checks, you can view the amount available to you and request funds through the app. Approval, advance limits, repayment terms, and available features can vary depending on your profile and Gerald’s current policies.
Who can use Gerald, and what requirements must applicants meet?
Eligibility is not guaranteed for every applicant. Gerald may require users to be adults, reside in supported areas, provide valid identification, and connect an eligible bank account or other financial information. The app can also review account activity and income-related details when determining access. Requirements may change, so users should check the latest terms inside the app before applying or relying on an advance.
How much money can I receive through Gerald?
The amount available through Gerald depends on several factors, including your eligibility, account history, income information, and the product offered to you. New users may receive a smaller limit, while limits can change over time based on repayment behavior and account activity. The app should display your specific available amount before you confirm a request, so do not assume that every user receives the same advance.
Are there fees, interest charges, or repayment requirements?
Before requesting money, carefully review the cost and repayment information shown by Gerald. Depending on the feature and your account, charges may include subscription costs, optional expedited-transfer fees, or other disclosed fees; terms can differ by user and location. Cash advances generally must be repaid according to the schedule presented in the app. Late or unsuccessful repayment could affect access to future advances.
Is Gerald safe to use, and what personal information does it require?
Gerald may request sensitive information such as your name, contact details, identification data, bank-account information, and financial activity in order to verify your identity and provide its services. Use the official app-store listing, review the privacy policy, and enable device security protections before signing up. No financial app is completely risk-free, so avoid sharing login codes and contact official support if you notice suspicious activity.
Advertisements

Download Gerald - Cash Advance
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 69.0.13
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.