


EarnIn: Why Wait for Payday?
Advertisements
App Specs
- Version
- 16.57
- Updated
- Nov 7, 2026
- Android Version
- 8.0
- Installs
- 10,000,000+
- Developer
- Activehours Inc.
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
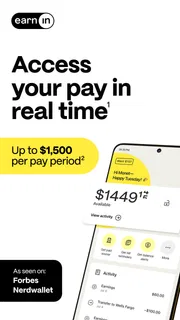
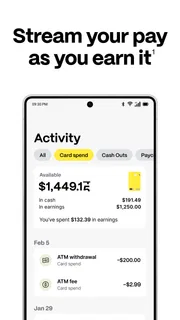
Our Review
 Analysis byUnlimiteds
A shared household is often where an early-pay app feels most useful—and where its limits matter most. Imagine a car needs an unexpected repair just before payday, while rent and groceries are already planned. If I’m the person who earned the wages and manages the account, accessing part of that pay might help cover the immediate bill. But that does not make the money extra income: it is pay arriving sooner, and the next payday still has to cover the rest of the month. I’d treat that timing shift as a short-term choice, not as a household budget strategy.
That distinction is especially important when several people share a device or make financial decisions together. An account connected to someone’s work and bank details should remain under that person’s control. I would not pass around login access just so a partner or housemate can check the balance, and I would agree in advance how an early withdrawal affects shared bills. EarnIn can help one worker manage a tight gap; it does not replace a conversation about who pays what.
Keep the account tied to the person who earned the pay
EarnIn is a finance app from Activehours Inc., and its basic premise is access to earned wages before the regular payday. That makes setup a personal financial step rather than a casual household sign-up. Before relying on it, I’d make sure the work and bank information being connected belongs to the person using the account, and that this person understands what an early cash-out does to later cash flow.
In a shared-device home, I’d also be deliberate about when and where I open a financial app. A phone left on a kitchen counter can make private details easier to see than intended, even when everyone in the home is trusted. The practical boundary is simple: keep account access with the account holder, avoid treating a shared screen as a shared account, and talk through any bill that another person expects the early money to cover.
Coordinate the bill, not just the withdrawal
A realistic use case is a utility bill landing a few days before wages arrive. If I were considering EarnIn for that gap, I’d first check the bill’s due date, the amount already available in my bank account, and which scheduled expenses will hit after payday. Then I’d decide whether taking some pay early solves a genuine timing problem or merely moves the shortfall to a later week.
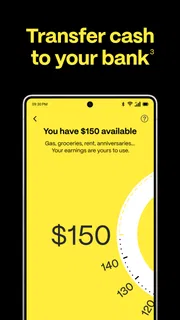
That quick check is more valuable than focusing only on the amount available to withdraw. The app’s store summary describes access of up to $150 a day, with a maximum of $1,000 per pay period, but a personal limit is not the same as a recommendation to use it. I’d take only what addresses the specific expense and write down which later bill or spending category must be adjusted. For a shared household, telling the other person responsible for the bill about that plan can prevent the same money from being counted twice.
Another useful habit is to keep a small note of each early withdrawal and its purpose. This is not an app feature; it is a simple way to see whether the service is handling an occasional mismatch or becoming part of ordinary weekly spending. If I repeatedly need it for groceries or routine bills, I’d revisit the budget and due dates rather than assume another cash-out will fix the underlying pattern.
Age, trust, and realistic expectations
The app is rated Everyone, but that content label should not be confused with permission or suitability for every person in a household. It is intended for an adult dealing with their own earnings and finances, not for a child to manage or for a family member to use on someone else’s behalf. I’d keep the account holder involved in every decision and avoid sharing sensitive financial access as a shortcut to household coordination.
EarnIn is free to download, and it has a 4.7 average from around 279,000 ratings, with over 10 million installs. Those figures can help show that it is widely used, but popularity does not tell me whether a particular withdrawal fits someone’s budget. I’d judge it by whether the terms shown in the app are clear to me, whether the money arrives in time for the bill, and whether I can handle the following pay period without another advance.
It also helps to separate an early-pay option from a loan or a longer-term fix. Someone who needs a one-off bridge between wages and a bill may find this approach more relevant than applying for a conventional short-term loan. Someone facing recurring shortfalls, uncertain income, or a bill that cannot wait for the app’s transfer timing may be better served by contacting the biller, asking about a payment arrangement, or seeking local financial guidance. I would not rely on an advance as emergency savings.
Where it fits among everyday alternatives
Compared with waiting for the normal payday, EarnIn offers flexibility around timing, but the trade-off is that money taken early is unavailable later in the pay cycle. Compared with a credit card, it does not simply add a purchase to a revolving balance; it makes earned pay available sooner. That can be useful for a known, necessary expense, but it still calls for a plan. For someone who can delay a non-urgent purchase, leaving the paycheck untouched is usually the cleaner option.
For a bill with a little flexibility, I’d compare the cost and consequences of paying late or arranging a due-date change with the consequences of shifting wages forward. For an overdraft risk, EarnIn’s listed Balance Shield notification may be a helpful prompt, but a warning is not the same as moving money or preventing every fee. I would still check the bank balance and upcoming transactions directly rather than treating an alert as a guarantee.
Timing deserves attention too. The published summary describes early payday access, but the original article’s claim about next-business-day delivery and its specific withdrawal amount should not be treated as a promise for every situation. I’d check the current amount and transfer timing presented in the app before depending on funds for a deadline. If a payment must clear immediately, a transfer option with timing I can verify—or a direct arrangement with the biller—may be safer.
My household verdict
EarnIn is most appealing to a worker with predictable pay who occasionally faces a mismatch between when a necessary expense is due and when wages arrive. It is less compelling for someone whose income changes sharply from week to week, who already struggles to cover the next pay period, or who would need to withdraw repeatedly for ordinary expenses. In those cases, the convenience can hide the fact that the same paycheck is being stretched across more days than it can comfortably cover.
The app is free, currently at version 16.21, and supports devices running OS 8.0 or later. I would still make the decision based on the account holder’s actual situation rather than on device compatibility or broad popularity. Before installing, it is worth asking: Is this for a specific bill? Can I manage after receiving less on payday? Do I understand any optional costs and the transfer timing shown in the app? If those answers are clear, an occasional use may be easier to manage than an improvised borrowing choice.
Have you ever found yourself in a pinch, waiting for payday, but the rent is due tomorrow? We've all been there! Enter EarnIn: Make Every Day Payday, the app that claims to revolutionize how we access our hard-earned cash. Let me walk you through my experience with this intriguing app.
What is EarnIn?
So, let's get down to business. EarnIn is an app that allows you to access a portion of your paycheck before payday arrives. The concept is simple: you work today, you get paid today. It's like having a financial buffer without the daunting interest rates of payday loans. Sounds like a lifesaver, right?
How Does It Work?
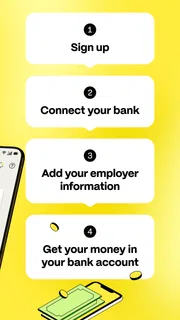
Setting up EarnIn is as easy as pie. You just download the app from the Google Play Store or App Store, link it to your bank account, and provide your employment details. Once set up, you can track your work hours through the app. When you need some cash, just tap the amount you want to withdraw, up to $100 per day, and it’s in your account the next business day. The best part? There are no mandatory fees! You can tip whatever you feel the service is worth.
Features That Stand Out
The app isn't just about getting your money early. EarnIn offers a few other nifty features:
- Balance Shield: A notification that warns you when your bank balance is low, helping you avoid overdraft fees.
- Cash Out: Allows you to withdraw cash whenever you need it, as long as you've worked the hours.
- Lightning Speed: An option to get your money instantly for a small fee, perfect for those "can't wait" moments.
My Personal Take
Honestly, using EarnIn felt like having a friend who always has your back. It's incredibly empowering to know that you can access your money on your terms. The app's interface is user-friendly and intuitive, making navigation a breeze. Plus, the Balance Shield feature is like having a financial guardian angel!
However, it’s important to remember that while this app can be a great tool, it shouldn’t replace effective budgeting. It's easy to get in the habit of cashing out frequently, which might lead to financial mismanagement if not handled wisely.
Conclusion
In a world where financial stress is all too common, EarnIn: Make Every Day Payday offers a refreshing approach to managing your earnings. It gives you the flexibility to access your pay when you need it, without the pitfalls of traditional payday loans. If you often find yourself counting down the days to your next paycheck, this app could be a game-changer. Just remember, with great power comes great responsibility!
Pros and Cons
Pros
- Instant cash advances available.
- No hidden fees or interest.
- User-friendly interface.
- Track hours and earnings easily.
- Supports financial planning.
Cons
- Limited to $100 per day.
- Requires bank verification.
- Not available in all states.
- Dependent on employer's payroll.
- May encourage poor budgeting.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 EarnIn: Why Wait for Payday?Activehours Inc. | 4.8 | 10,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is EarnIn and how does it work?
EarnIn is a financial app that allows users to access a portion of their earned wages before their actual payday. Users can connect their bank accounts and work information to the app. Once verified, they can cash out small amounts of their paycheck, which are then deducted from their account on their next payday. This service is designed to help users manage unexpected expenses or emergencies without waiting for their regular pay cycle.
Is there a fee to use EarnIn?
EarnIn does not charge mandatory fees or interest for accessing your wages early. Instead, it operates on a tip-based model. Users can choose to leave a voluntary tip when they withdraw money, which supports the app's operation. This model allows users to decide what the service is worth to them, making it a flexible financial tool.
What are the eligibility requirements for using EarnIn?
To use EarnIn, users must have a consistent pay schedule, an active checking account, and a job where they are paid via direct deposit. Additionally, users need to have a fixed work location or electronic timesheet to verify their work hours. These requirements ensure that the app can accurately track earnings and provide access to funds.
How much money can I withdraw using EarnIn?
The amount you can withdraw from EarnIn depends on several factors, including your earnings and usage history with the app. New users typically start with a lower withdrawal limit, which can increase over time as they build a history with the app. The maximum limit is usually around $100 per day or $500 per pay period, although this can vary.
Is EarnIn safe to use and how does it protect my information?
EarnIn employs bank-level security measures to protect users' information, including encryption and secure data storage practices. The app requires minimal personal information and does not store user banking credentials. Additionally, EarnIn's systems are regularly tested for vulnerabilities, ensuring that users' data is secure while using the app.
Advertisements

Download EarnIn: Why Wait for Payday?
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 16.57
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.