


Build & Fix Credit - Dovly AI
Advertisements
App Specs
- Version
- 9.5.0
- Updated
- Nov 7, 2026
- Android Version
- 7.0
- Installs
- 1,000,000+
- Developer
- Dovly.com
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
When a household is trying to make sense of credit, the hardest part is often separating one person’s finances from everyone else’s advice. I’d treat Dovly as a personal workspace, not a shared family dashboard: the credit picture and any decisions connected to it belong to the individual using the account. That distinction matters if a partner or relative is helping someone get organized, or if the app is installed on a device other people also use.
Keep the account personal, even on a shared device
In a shared-use situation, I would begin by deciding whose credit journey the app is meant to support. The person whose information is involved should be the one who signs up, reviews the app’s prompts, and makes choices about next steps. A relative can sit alongside them to help read a screen or talk through a coaching tip, but that is different from treating the account as a household record everyone can browse.
This is a useful boundary for couples, adult children helping a parent, or anyone who sometimes lends a phone to family. A credit score is personal financial information, so I would avoid leaving the app open when handing the device to someone else. If you share a tablet or phone, make a habit of closing the app when finished and keep account access with the person it represents. That simple routine is more practical than assuming a shared device automatically means shared financial visibility.
Set expectations before following a plan
Getting started involves signing up and providing basic details, so I would take a moment to read each prompt carefully rather than rushing through setup while another person is waiting. If someone is helping, they can offer a second set of eyes, but the account holder should understand what they are entering and why. That is especially important when the goal is to review credit information or act on a possible report error.
I also wouldn’t approach the app as a quick score-boost button. Credit changes depend on the underlying situation and on what happens over time; an app can help organize actions, but it cannot make every negative item disappear or guarantee a particular result. Before disputing anything, check that the information is genuinely inaccurate and gather the details you need to explain the issue. An organized, accurate dispute is more useful than sending one simply because a number feels disappointing.
Coordinate without taking over
For two people working on separate credit goals, I’d keep the routines separate even if they discuss progress together. One person might use a coaching suggestion as a reminder to review a report, while the other may have a different issue to address. A shared conversation can help with accountability, but copying someone else’s plan without checking whether it fits your own report is a poor shortcut.
A realistic example: after a household budget check-in, one partner notices a score change and opens the app to see what has shifted. They can review the notification and decide whether it calls for attention, while the other partner helps them note questions to investigate. That’s useful coordination without handing over control of the account or assuming the change requires an immediate dispute. I’d treat alerts as prompts to look, not as instructions to act before checking the details.
Age, trust, and the limits of family help
Dovly is a finance app for adults managing their own credit rather than a family budgeting tool. Its age rating is Everyone, but that label should not be confused with a reason for a child to manage an adult’s financial account. If a younger family member is curious about credit, I’d explain general concepts together instead of sharing account access or asking them to make decisions about someone else’s report.
Trust also means being clear about what help is being offered. A family member may be comfortable discussing a score but not sharing account details, and that boundary deserves respect. The app can support an individual’s credit routine; it should not become a substitute for direct consent or a reason to pressure someone into revealing personal financial information.
Getting Started with Dovly
First things first, downloading and setting up Dovly was a breeze. Available on both Android and iOS, you can easily find it on your respective app store. Once you fire it up, you'll need to sign up and provide some basic details to get started. Don't worry, the app ensures your data is safe and sound.
Features That Make Dovly Stand Out
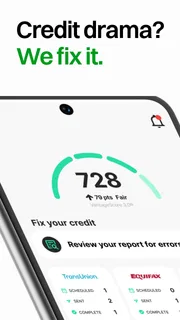
The user interface is clean and intuitive, which is something I always appreciate in an app. Right off the bat, Dovly gives you a clear snapshot of your current credit score. The app then takes you through a personalized plan to help boost that number. One feature that I found particularly useful is the automated credit dispute process. Rather than spending hours trying to fix discrepancies, Dovly does the heavy lifting for you.
Another nifty feature is the credit coaching tips they offer. It’s like having a financial advisor in your pocket, offering you insights into what you can do to improve your credit score. The app also sends out notifications to keep you updated on any changes to your credit report, which is super handy for staying on top of things.
Does It Really Work?
Now, the million-dollar question: does it actually work? From my experience, I noticed a gradual improvement in my credit score after following the app’s recommendations. It’s not an overnight miracle worker, but it certainly sets you on the right path. The key here is consistency and following the advice given by the app.
One thing I must mention is the community support. Dovly has a forum where users can share their experiences and tips. It’s always reassuring to know that others are in the same boat and you can learn from their journeys too.
How it fits alongside other credit tools
I see Dovly as a guided credit-improvement companion, not a replacement for every financial tool. Compared with checking a score through a bank or a basic credit-monitoring service, its appeal is the combination of a score snapshot, coaching, alerts, and help with disputes. Those pieces can make it easier to turn “I should deal with my credit” into a specific task. A simpler score checker may be enough if you only want occasional visibility and already know how you plan to respond to changes.
It also isn’t the same as a full personal-finance app built around budgets, bills, and spending categories. If your main challenge is figuring out where each paycheck goes, a budgeting tool is likely a better first stop. Dovly makes more sense when the central question is what is happening with your credit and what steps might be relevant. I’d use it alongside a budget if both needs matter, rather than expecting one app to solve unrelated money problems.
A practical routine that avoids busywork
To get value without turning credit checking into a daily chore, I’d use a small routine: review the score and report-related updates when they arrive, make a note of anything unfamiliar, then investigate before acting. For an apparent error, compare the item with your own records and keep the explanation focused on the specific mismatch. The dispute workflow can reduce the effort of handling the process, but it doesn’t remove the user’s responsibility to check that a claim is accurate.
Coaching is most useful when I treat it as a prompt to examine a habit or understand a factor, not as a promise that one action will produce a fixed result. If a tip feels unclear or doesn’t fit the account holder’s circumstances, pause and verify what it means before changing a financial routine. This is a small but important trade-off: guided steps can make the process less intimidating, while a person still needs to bring judgment and patience.
Who will get the most from it?
I’d recommend considering Dovly if you are new to credit management, want a clearer routine for checking your score, or have a specific report issue you need to investigate. It can also suit someone who benefits from reminders and plain-language coaching rather than searching through scattered advice. The app is free to download, and it has a 4.7 average from around 49,000 ratings, which suggests many users find the approach useful; that should be a starting point for your decision, not a guarantee that your own experience will match theirs.
By contrast, I’d skip it if you are looking for instant score gains, a household account everyone can manage together, or a complete budget-and-bill system. It may also be unnecessary if you already review your credit through another service and are comfortable handling report questions yourself. Dovly’s value is in guided credit tasks; paying attention to whether you need that guidance is a better test than downloading every finance app that promises improvement.
Free to start, but check the purchase choice
Dovly is free, with in-app purchases ranging from $0.99 to $199.99 per item. I’d look closely at any paid option before committing and ask what problem it solves for me, rather than assuming a purchase is required to make progress. If you’re helping a family member, let the account holder review that choice themselves; another person’s willingness to pay should not be confused with consent to use or manage their financial account.
The app comes from Dovly.com, has been available since April 25, 2022, and its current version is 7.0.13, with Android 7.0 as the minimum OS. It has passed 500,000 installs and is rated for Everyone. Those details offer a quick sense of its reach and compatibility, but the practical question is still whether its credit-focused workflow fits your own needs and the device you plan to use.
Final Thoughts
Overall, I can say that Dovly is worth a shot if you're looking to improve your credit score. It's user-friendly, informative, and offers practical steps to help you out. While it does require some patience and commitment, the results are worth it. So, if you're tired of being haunted by your credit score, give Dovly a try and see for yourself.
For a household, my verdict is more specific: it can be a helpful personal tool that family members discuss together, but I would keep each person’s account and decisions firmly separate. The strongest reason to try it is the mix of credit visibility, coaching, and a structured way to approach possible report errors. The main reason to look elsewhere is if you need shared financial management, detailed budgeting, or a guaranteed outcome. Used with realistic expectations and careful account boundaries, it can make credit maintenance feel more manageable without turning one person’s financial information into everyone’s business.
Pros and Cons
Pros
- User-friendly interface for easy navigation.
- Real-time credit score updates.
- Customizable alerts for credit changes.
- No hidden fees or charges.
- Free credit report insights.
Cons
- Limited features in free version.
- Requires access to sensitive data.
- No live customer support available.
- Occasional app glitches reported.
- Limited educational resources.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Build & Fix Credit - Dovly AIDovly.com | 4.7 | 1,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Dovly and how does it work?
Dovly is a credit improvement app designed to help users monitor and enhance their credit scores. By connecting the app to your credit profile, Dovly uses advanced algorithms to identify and dispute negative items on your credit report. It's a simple and automated process that aims to optimize your credit health over time, making it easier for you to achieve better financial opportunities.
Is Dovly safe to use with my personal information?
Yes, Dovly prioritizes user data security and privacy. The app uses bank-level encryption to protect your personal information and complies with all relevant data protection regulations. Dovly ensures that your sensitive information is only used for the purpose of improving your credit score and is never shared with unauthorized parties.
How long does it take to see improvements in my credit score with Dovly?
While results may vary depending on individual circumstances, many users report seeing improvements in their credit scores within a few months of using Dovly. The app continuously works to dispute inaccuracies and optimize your credit profile, leading to gradual improvements. Patience is key, as credit repair is a process that can take time to yield significant results.
Does using Dovly guarantee an increase in my credit score?
While Dovly is designed to help improve your credit score, it cannot guarantee specific results. The app works by disputing inaccuracies and negative items on your credit report, which can lead to improvements. However, the outcome depends on various factors, including the nature of the items being disputed and the responsiveness of credit bureaus.
Are there any costs associated with using Dovly?
Dovly offers both free and premium subscription plans. The free version provides basic credit monitoring and dispute features, while the premium version includes more comprehensive services such as enhanced dispute capabilities and personalized credit insights. Users can choose the plan that best suits their needs and budget, with transparent pricing details available on their website.
Advertisements

Download Build & Fix Credit - Dovly AI
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 9.5.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.