


Debt Payoff Planner & Tracker
Advertisements
App Specs
- Version
- 2.54
- Updated
- Nov 7, 2026
- Android Version
- 6.0
- Installs
- 500,000+
- Developer
- Easily get a plan and stick to it - OxbowSoft LLC
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
Getting out of debt is rarely difficult because people cannot do basic arithmetic. The harder part is turning several balances, due dates, interest rates, and competing priorities into one plan that is easy enough to follow on an ordinary Tuesday. I found Debt Payoff Planner & Tracker most useful in that exact starting condition: when the numbers feel scattered and motivation disappears after the first payment.
This is a free finance app from Easily get a plan and stick to it - OxbowSoft LLC. Its purpose is focused rather than broad. It is not trying to be a complete banking replacement or an all-purpose household budget. Instead, it helps you organize debt, choose a payoff direction, track progress, and keep the goal visible. That narrow focus is its strongest quality, although it also explains why some people will eventually want a more comprehensive money-management tool.
From scattered balances to a payoff routine
I start this section with the point where a debt plan becomes useful: turning a jumble of statements and remembered figures into a routine I can revisit without dread. I’ll focus on how to make that first inventory dependable, because small entry errors can quietly distort later choices. From there, the next section looks at how to choose a payoff approach that fits both the numbers and the person following it.
Starting with the uncomfortable inventory
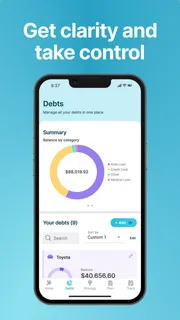
The first useful step is also the one many people avoid: putting every debt in one place. I recommend opening the app when you have your latest statements nearby, rather than trying to remember figures from memory. The quality of the plan depends on the quality of the starting information, so rushing through this stage can create false confidence later.
For each account, the important details are the balance, interest information, minimum payment, and payment timing. Entering these carefully turns a vague thought such as “I need to pay off my cards” into a defined list of obligations. That change matters psychologically. A debt that exists only in your head can feel endless; a debt that appears in a structured plan has a next action.
I would not treat the app as a financial detective. It works best when you already have access to your statements and understand which figures belong to which account. If your debts are changing frequently, take a moment to verify the entries after each statement cycle. A planner can organize what you enter, but it cannot correct an outdated balance or a forgotten account.
Choosing a strategy instead of guessing
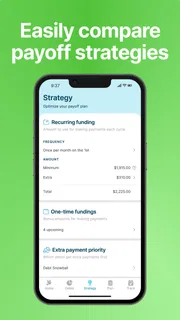
Once the debts are organized, the central decision is how to direct extra money. Many users know the familiar choices: paying the smallest balance first can create quick wins, while targeting the most expensive interest can reduce the cost of borrowing. The right choice depends on both mathematics and behavior. A technically efficient plan that you abandon is less useful than a slightly less efficient plan you can follow every month.
This is where the planner’s focused design makes sense. Rather than leaving the decision as a vague promise, it gives you a framework for seeing how payments affect the order and pace of repayment. I found that especially helpful when comparing a motivating short-term victory with a more interest-conscious approach. The app does not remove the personal judgment from the decision, but it makes the consequences easier to consider.
A practical tip is to test the plan against your real cash flow before committing. Use an amount you can maintain after rent, food, transport, utilities, and a modest buffer. A payoff schedule built around an optimistic month can become discouraging when an ordinary expense arrives. The most useful number is not the largest payment you could make once; it is the payment you can repeat without creating another emergency.
Making the plan fit an ordinary month
The app becomes more valuable when the plan is connected to a routine. I would choose a regular review point, such as the day after payday or the evening when you normally check bills. At that moment, open the planner, confirm what has been paid, and update the relevant balances. This turns progress tracking into a small recurring task instead of a dramatic monthly audit.
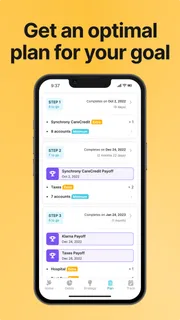
A realistic household example might involve several revolving balances and one fixed loan. The user has limited extra cash after minimum payments, but expects a little more room after a seasonal expense ends. Rather than immediately assigning every possible dollar, I would record the current situation, maintain the minimums, and use the planner to see what happens when the extra amount becomes available. That creates a staged plan instead of pretending the future is already certain.
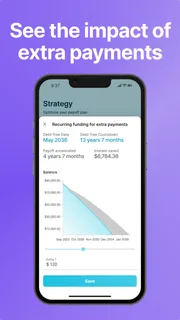
Another useful workflow is to separate “planned” money from “available” money. The amount shown in a payoff plan should not be confused with cash sitting in your account today. Before making an extra payment, I would check upcoming bills and keep enough for essentials. The app can support the decision, but it should not encourage you to empty your emergency cushion simply because the projected finish looks better.
Tracking the handoff from plan to payment
The app does not replace the lender, card issuer, or bank where the actual payment takes place. That handoff is important. I would use the planner to decide what should happen, then make the payment through the creditor’s normal channel, and finally return to the app to record the result. Thinking of it as a three-part loop—plan, pay, update—prevents a common mistake: assuming that a planned payment has already been made.
This manual handoff is both a strength and a limitation. It keeps the planner centered on your decisions rather than turning it into a complicated banking dashboard, but it also demands discipline. If you make payments in several different places, the app will not remove the need to check confirmations and statements. I prefer that separation for a focused debt tool, but users expecting automatic account synchronization may find the process less convenient than they hoped.
To reduce errors, I would update the app only after the payment has been processed or after the lender’s account clearly reflects it. Recording a payment too early can make the projected balance look healthier than reality. Keeping the dates and amounts aligned with the creditor’s records also makes the planner more useful when you review your progress later.
Using progress as a behavioral tool
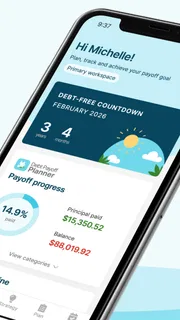
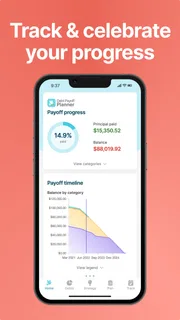
The emotional side of repayment deserves attention. Minimum payments can feel like movement without visible change, especially when interest consumes part of the effort. A tracker gives you a place to notice the balance declining and to mark milestones that are meaningful to you. That does not change the debt mathematically, but it can make a long process easier to continue.
I would use milestones carefully. Celebrating a cleared account can be motivating, but the celebration should not become a new credit-card expense. A better reward might be a free activity, a planned rest day, or simply sharing the achievement with someone who supports the goal. The app is most effective when its progress display reinforces a habit rather than encouraging impulsive spending.
One non-obvious benefit of tracking is that it exposes the difference between a busy month and a broken plan. If a payment is smaller than expected once, that does not necessarily mean the strategy failed. Looking at the overall direction can help you adjust the next payment without abandoning the entire system. I would rather revise an honest plan than preserve a perfect-looking projection that no longer matches life.
What the app does well for different users
This is a strong fit for someone who has multiple debts and wants a dedicated place to organize them without learning a full budgeting system. It is also useful for a couple who needs a shared conversation starter, even if only one person enters the information. Sitting together with a visible list can make it easier to agree on which balance receives extra attention and how much the household can safely commit.
It can also help people who have already chosen a strategy but keep losing track of the details. In that situation, the main value is not discovering a magical method. It is reducing the mental load of remembering balances, payment order, and progress. The app’s focused purpose makes it easier to return to the same goal instead of getting distracted by unrelated financial features.
On the other hand, I would look elsewhere if your main need is a complete spending plan, investment tracking, bank aggregation, or detailed income forecasting. A debt planner can sit beside those tools, but it is not a substitute for them. Someone with one simple loan and a stable automatic payment may also find a dedicated tracker unnecessary; a calendar reminder and the lender’s statement could be enough.
Free access, paid expansion, and everyday expectations
The app is free to install, with optional in-app purchases ranging from around seven dollars to around forty-two dollars per item. I would begin with the free experience and decide whether the workflow genuinely helps before paying for anything. The important test is not whether extra options look attractive; it is whether they make your own repayment routine clearer and easier to maintain.
Because financial information is personal, I would also approach setup deliberately. Use a private moment, avoid entering figures while distracted, and review the entries before relying on the projected outcome. The Everyone age rating makes the app broadly accessible, but younger users dealing with debt may still need an adult or trusted adviser to understand interest, minimum payments, and the consequences of missed due dates.
The app has been available since early 2015 and supports Android 6.0 or later. Its current version is 2.54, and its longevity suggests that it is not a brand-new experiment. I would still keep the app as a planning aid rather than my only financial record. Statements from creditors remain the authority for balances, fees, and payment status.
Where the workflow starts to break
The biggest friction is the gap between planning and execution. You still have to make the payments elsewhere and keep the entries current. That is manageable for a small number of accounts, but it becomes more demanding when balances change often, payments are split across dates, or a household has irregular income. The app can show a plan, yet the plan remains only as accurate as the updates you provide.
Another limitation is that debt repayment is not isolated from the rest of life. A strategy that directs every spare dollar toward balances may look impressive while leaving no room for car repairs, medical costs, or a temporary reduction in income. I would use the planner alongside a basic emergency-fund decision, not as an instruction to prioritize debt at any cost.
Interest rates and creditor rules can also complicate a simple payoff order. Promotional rates may expire, minimum payments may change, and some loans have conditions that deserve closer reading. When those details matter, I would confirm the plan against the lender’s terms or ask a qualified financial professional. The app can help structure the conversation, but it should not be treated as personalized legal or financial advice.
Finally, motivation can fade even when the numbers are correct. If you need automatic reminders, shared household permissions, direct transaction importing, or a broad view of spending, another finance product may be a better center for your system. In that case, this planner could still play a supporting role, but it may not be the one app you open every day.
My result after using the complete loop
What I like most is the clear progression from confusion to action: gather the debts, choose a payoff direction, set an amount that fits reality, make the payment through the proper channel, and update the record afterward. That loop gives the app a practical purpose beyond displaying balances. It helps turn debt repayment into a repeatable process that can survive an imperfect month.
Its audience is specific. If you want a dedicated debt payoff planner with a motivation-friendly progress view and you are willing to maintain the information yourself, Debt Payoff Planner & Tracker is an approachable choice. Its 4.5 average from around 4.7 thousand ratings and more than 500 thousand installs indicate that many people have found the concept useful, while the roughly 1.2 thousand written reviews show that it has attracted substantial user feedback.
My recommendation is to treat it as a practical companion, not a financial autopilot. Start with accurate statements, choose a sustainable payment, keep the lender’s records as the final authority, and review the plan whenever your income or obligations change. For someone who needs a focused path from “I owe money in several places” to “I know what I am doing this month,” it can provide exactly the structure that is easiest to lose.
Pros and Cons
Pros
- Clear payoff projections help you understand when debts may be cleared.
- Supports multiple debt accounts in one organized dashboard.
- Useful progress tracking can keep repayment goals visible and motivating.
- Lets you compare different payoff strategies before choosing one.
- Simple interface makes regular balance updates quick to complete.
Cons
- Some advanced planning features may require a paid subscription.
- Results depend on entering accurate balances
- rates
- and payment details.
- It may not connect directly to every bank or lender account.
- Users with irregular income may find fixed payment planning limiting.
- The app does not replace professional advice for complex debt situations.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Debt Payoff Planner & TrackerEasily get a plan and stick to it - OxbowSoft LLC | 4.5 | 500,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Debt Payoff Planner & Tracker used for?
Debt Payoff Planner & Tracker is designed to help you organize debts and create a realistic repayment plan. After entering balances, interest rates, minimum payments, and due dates, the app can show how different strategies may affect your payoff timeline. It is useful for monitoring progress, prioritizing accounts, and keeping repayment information in one convenient place.
Does Debt Payoff Planner & Tracker support different debt repayment strategies?
Yes, the app is generally built around popular approaches such as the debt snowball and debt avalanche methods. The snowball method focuses on paying smaller balances first, while the avalanche method prioritizes debts with higher interest rates. Comparing these options can help you choose a strategy that matches your financial goals, motivation, and available monthly budget.
Can I use the app for credit cards, loans, and other types of debt?
The app is intended for tracking multiple kinds of personal debt, including credit cards, personal loans, medical bills, and similar accounts. You can typically add details for each debt separately, such as the current balance, interest rate, minimum payment, and payment frequency. Accurate information is important because incorrect entries will produce unreliable payoff estimates.
Is Debt Payoff Planner & Tracker a financial advisor or a debt-relief service?
No. Debt Payoff Planner & Tracker is a planning and tracking tool, not a licensed financial advisor, lender, credit counselor, or debt-relief company. Its calculations are estimates based on the information you provide and should not be treated as professional financial advice. Before changing payments, refinancing, or closing accounts, consider consulting a qualified professional.
Is my financial information safe when using Debt Payoff Planner & Tracker?
Before entering sensitive information, review the app’s current privacy policy, permissions, and data-handling practices in the Google Play Store or Apple App Store. Avoid entering passwords, full bank login details, or unnecessary personal identifiers. Keep the app updated, use device security features, and remember that storing debt information on a phone can still involve privacy risks if the device or account is compromised.
Advertisements

Download Debt Payoff Planner & Tracker
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 2.54
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.