


DailyPay On-Demand Pay
Advertisements
App Specs
- Version
- 52.0.0
- Updated
- Nov 7, 2026
- Android Version
- 9
- Installs
- 1,000,000+
- Developer
- DailyPay Inc
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
I see DailyPay as a useful way to make a pay schedule less rigid, not as extra income or a fix for an ongoing budget gap. It is a finance app from DailyPay Inc that gives eligible employees a route to reach wages they have already earned before payday. That distinction matters: the service can help with timing, but it does not make the underlying cost of living smaller. For someone who occasionally needs money before their normal pay date, that can be a practical difference.
DailyPay is free to download, rated for Everyone, and has a 4.7 average across around 203,000 ratings. More than a million people have installed it, which suggests that on-demand pay is a familiar need rather than an unusual one. Those figures make it worth a look, but they do not tell me whether it will work for a particular employee: access depends on the employer’s participation, so checking that first is the sensible starting point.
Getting to Know DailyPay
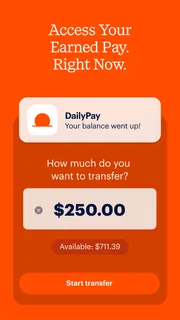
So, what exactly is DailyPay? Well, imagine having the power to access the money you've already earned whenever you need it, instead of waiting until payday. That’s the magic of this app. It’s designed to give employees control over their finances by allowing them to transfer earned but unpaid wages to their accounts before payday. This isn’t a loan; it’s your money, available when you need it.
When Earlier Access Actually Helps
The strongest case for an earned-wage app is a mismatch between when a bill is due and when wages arrive. Imagine your phone bill is scheduled to come out a few days before payday, while your account is otherwise short. If DailyPay is available through your workplace, being able to move a portion of wages already earned may help you avoid a late payment or an overdraft. That is a narrower, more realistic benefit than treating early access as a general spending boost.
I would use it most carefully for a defined, necessary expense: work transport, a household bill, or a prescription that cannot wait. Before transferring, I’d check what amount is actually needed and what will remain for the rest of the pay period. Taking only the shortfall is a useful safeguard; routinely moving the largest available amount can leave payday feeling smaller, even though the wages are simply arriving earlier.
That timing trade-off is easy to miss. A transfer solves the immediate cash-flow problem, but the next scheduled paycheck may be reduced by money already accessed. It is therefore worth looking at the whole pay cycle, not just the balance displayed today. If the same shortfall appears every week, early access may be a signal to revisit bill dates, spending commitments, or available support rather than a sustainable answer by itself.
How It Works
Setting up DailyPay is a breeze. Once you download the app and register, you link it to your employer’s payroll system. The interface is user-friendly, with a dashboard that shows your available balance and a simple transfer process. You can choose to transfer any amount up to your available balance, and the money is usually deposited into your bank account instantly or by the next business day. It’s as simple as ordering a pizza online!
The key practical question is not only how much the screen says is available, but whether the app can serve the purpose you have in mind. I would first confirm that my employer is supported, then make sure the account details I use are the ones where I can actually receive and manage the money. A transfer intended to cover a same-day expense is less helpful if I have not checked the delivery timing shown for that transaction.
For a first use, I’d make a small, planned transfer rather than relying on the app in the middle of an urgent situation. That gives me a chance to understand the steps, review the fee disclosure, and see how the timing fits my own bank and bill schedule. It is a low-effort way to learn the workflow without building a habit around transferring whenever the balance becomes available.
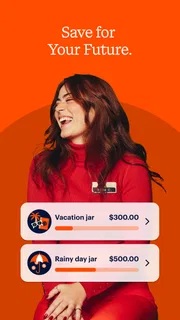
One of the standout features is the app’s transparency. It clearly outlines any fees associated with the transfers before you go ahead, so there are no surprises. Plus, you get notifications about your earnings and the option to save a portion of your paycheck automatically, which is a nifty feature for those trying to build a savings habit.
What the Convenience Costs
Despite its benefits, there are a few things to consider. The app charges a small fee for each transaction, which can add up if you frequently dip into your earnings. It’s something to weigh against the convenience and peace of mind that the service offers.
I would treat the fee as part of the price of solving a timing problem, not as a detail to ignore because the transfer is convenient. Before confirming, compare the displayed cost with the consequence you are trying to avoid. If the expense can wait until payday without a penalty, waiting may be the cheaper choice. If the alternative is a costly late charge, the transfer could make more sense, but that depends on the actual amounts in front of you.
Frequency matters as much as the fee on any one transfer. Several small withdrawals can make it harder to see how much of the next paycheck is already spoken for, and each transaction may carry its own cost. Grouping a planned need into one transfer, when practical, can make the expense easier to track. I would still avoid taking more than necessary just to reduce the number of transactions: a larger early withdrawal can create a tighter finish to the pay period.
The savings option deserves a similar bit of thought. Setting aside part of a paycheck can support a useful routine, but savings and early access pull in different directions if both are used without a plan. I’d choose a manageable amount to save and keep enough available for known bills, rather than assuming a savings setting will automatically fix an uneven budget. The value is in making the choice deliberate.
Who It Fits, and Who Should Look Elsewhere
DailyPay is most appealing to employees whose workplace supports it and whose main difficulty is the calendar: money is coming, but an essential expense arrives first. It may also suit people who want a more structured alternative to borrowing for a one-off cash-flow gap, provided they understand the fee and the effect on their next pay. The app’s current version is 37.0.0, and its finance focus is clear: access and manage earned wages, rather than replace a bank account or provide a complete budgeting system.
It is not the right option for someone whose employer does not participate, or for anyone who needs a guaranteed transfer method without checking the timing presented in the app. It is also a poor fit if the need is recurring because income does not cover regular costs. In that situation, repeatedly drawing wages forward can shift the pressure from one date to another. A conversation about changing bill due dates, a budget review, or a more suitable form of financial assistance may address the root problem better.
Compared with waiting for a standard payday, DailyPay’s advantage is access before that date; the trade-off is that money is moved forward and a fee may apply. Compared with a credit card, it is tied to wages already earned rather than a revolving credit balance, but that does not make every transfer cost-free or automatically wise. Compared with a personal loan, it is aimed at short-term timing needs rather than borrowing a separate lump sum to repay over time. These are different tools, and the right comparison is the real cost and repayment pressure in the user’s own situation.
For a person who simply needs more visibility, a basic spending plan or bank balance check may be enough and may avoid transaction fees. If the goal is to build savings over time, setting an automatic transfer after payday can be more predictable than relying on early wage access. I would choose DailyPay when timing is the specific obstacle, not just because the app makes available wages feel more spendable.
Why You’ll Love It
Let’s talk convenience. I can’t emphasize enough how liberating it feels to have control over your wages. Whether it’s an unexpected bill or an impulse buy, knowing you can access your money when you need it is a massive relief. It’s like having a financial safety net that’s always there to catch you.
For me, the most valuable part is the ability to make a more considered choice when a necessary payment arrives at an awkward time. The app may give someone an alternative to a high-interest payday loan or to putting an urgent expense on a credit card, but the comparison should be made carefully. A fee still matters, and a transfer does not erase the obligation to cover the rest of the pay period. I see it as one possible buffer, not a reason to spend more freely.
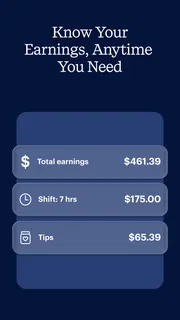
Notifications can also help make earnings and transfers more visible, which is useful if you otherwise lose track of what has already been earned or moved. I would use those prompts as a reminder to check the numbers, not as a cue to withdraw. A quick look at upcoming bills before acting can turn convenience into a deliberate decision instead of an automatic habit.
Moreover, the app helps reduce financial stress. By giving you access to your earned wages, it minimizes the need for high-interest payday loans or credit card debt. It’s like having a financial buffer that can help you manage your finances more effectively.
That benefit has limits. If a user draws early wages frequently, the following payday can become a recurring squeeze, and the app cannot make an income shortfall disappear. I would consider the service successful when it helps bridge an occasional gap and makes the next few days easier, while leaving a clear plan for the rest of the pay period. If every pay cycle requires another transfer, that pattern is worth taking seriously.
A Sensible Way to Try It
Before depending on DailyPay, I’d verify employer access, review the amount available for the intended transfer, and read the fee and delivery details on the confirmation screen. I’d also note which upcoming expenses still need to be paid from the next paycheck. Those checks answer the practical questions that matter most: can I use it at work, how much will this cost, when should the money arrive, and what will this mean for payday?
I would keep a simple record of early transfers alongside ordinary spending. It need not be complicated: the date, amount, and reason are enough to reveal whether the service is solving an occasional mismatch or becoming part of routine budgeting. If the same category of expense keeps prompting a transfer, changing its due date or setting aside money from a prior paycheck may be a better long-term fix.
DailyPay is a finance app developed by DailyPay Inc, and its straightforward purpose is its main strength. It does not need to be treated as a full financial planner to be useful. The best experience will likely come from using it with a specific amount and reason in mind, checking the terms each time, and resisting the temptation to regard an available balance as money beyond the wages already earned.
Things to Keep in Mind
Also, while DailyPay is expanding its partnerships, not all employers offer it yet. So, it’s worth checking if your workplace is on board before getting too excited.
That employer requirement is the first real filter, and it is better to check it before planning around an early transfer. Even when access is available, the usefulness depends on whether the balance, delivery timing, and fee suit the particular expense. I would not assume that an app designed for earlier pay will solve every urgent cash need in the same way each time.
My overall view is positive but measured: DailyPay can make earned wages more accessible when a bill and a payday do not line up, and the option to see costs before transferring helps users make an informed choice. The catch is that repeated access can become an expensive routine or leave less money for the next pay date. Use it for a defined short-term need, keep an eye on the full pay cycle, and look for another approach if the same gap keeps returning.
In conclusion, if you’re looking for financial flexibility and peace of mind, DailyPay is definitely worth considering. It’s a modern solution to an age-old problem, offering a fresh take on how we think about payroll. So, why wait for payday when you can get paid today?
Pros and Cons
Pros
- Instant access to earned wages.
- User-friendly interface design.
- Secure and encrypted transactions.
- 24/7 customer support available.
- Customizable notification settings.
Cons
- Limited to partnered employers.
- May encourage impulsive spending.
- Fees for instant transfers.
- Requires bank account linking.
- Not available in all regions.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 DailyPay On-Demand PayDailyPay Inc | 4.7 | 1,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is DailyPay On-Demand Pay and how does it work?
DailyPay On-Demand Pay is an innovative financial app that allows employees to access their earned wages before the standard payday. Instead of waiting for a bi-weekly or monthly paycheck, users can see and transfer earned wages as they accrue, giving them more control over their financial wellbeing. This service can be particularly useful for managing unexpected expenses or cash flow needs without resorting to high-interest loans.
Is DailyPay On-Demand Pay safe to use?
Yes, DailyPay On-Demand Pay is designed with security in mind. The app uses bank-level encryption and complies with financial regulations to ensure the safety of user data and transactions. Additionally, it does not store sensitive information on the user’s device, which adds an extra layer of protection. Users can confidently use the app knowing their personal and financial information is secure.
Do I need to pay any fees to use DailyPay On-Demand Pay?
DailyPay offers a transparent fee structure. While there is typically a small fee for instantly transferring funds to your bank account, users can also opt for a no-fee transfer that arrives on the next business day. The app provides clear information about any fees before transactions occur, allowing users to make informed decisions based on their financial needs.
Can DailyPay On-Demand Pay affect my work payroll or employment status?
No, using DailyPay won't impact your payroll schedule or employment status. The app simply provides early access to wages already earned, without altering your employer's payroll processes. Your official payday remains unchanged, ensuring that all standard deductions and contributions are accurately applied. Employers partner with DailyPay to offer this benefit without any negative impact on employment terms.
Which employers offer DailyPay On-Demand Pay to their employees?
DailyPay partners with a variety of employers across different industries to provide its services. The availability of DailyPay depends on whether your employer has an agreement with them. It’s best to check with your HR department or the DailyPay website to see if your company participates. The growing list of participating employers includes large corporations, as well as small to mid-sized businesses, enhancing accessibility for many employees.
Advertisements

Download DailyPay On-Demand Pay
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 52.0.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.