


Daily Loan - Money Tracker
Advertisements
App Specs
- Version
- 1.0.6
- Updated
- Nov 7, 2026
- Android Version
- 7.0
- Installs
- 1,000,000+
- Developer
- SUMMIT CITY PROSTHETICS & ORTHOTICS, INC.
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
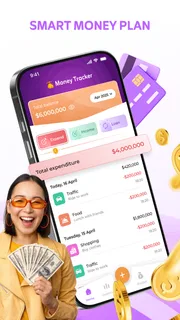
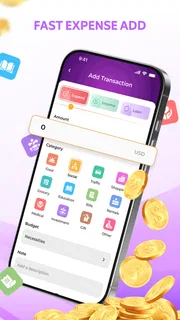
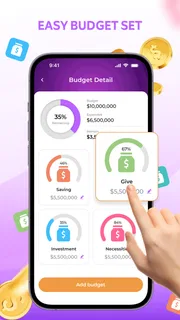
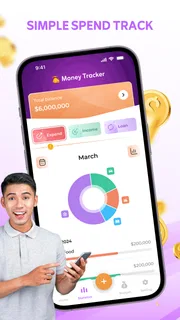
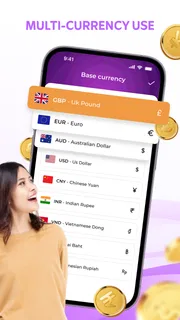
Our Review
 Analysis byUnlimiteds
Managing everyday borrowing and spending is one of those jobs that sounds simple until several small payments begin competing for attention. Daily Loan - Money Tracker takes a focused approach: it is a free finance app built around tracking expenses and organizing a budget, with its short store description identifying it as “Daily Loan.” I found the most useful way to think about it is not as a complete banking replacement, but as a lightweight place to record money movement before it disappears from memory.
That distinction matters. A budgeting tool only helps when it fits the moment in which you actually spend. If entering a purchase feels like paperwork, the record quickly becomes incomplete. This app is most appealing to someone who wants a direct routine for noting daily expenses and keeping loan-related money visible without committing to a large financial-management system.
Putting daily money tracking at the center
The app’s main value is the connection between two habits that people often handle separately: recording what leaves their pocket and checking whether the remaining plan still makes sense. A budget made at the beginning of the month can look reassuring, but it becomes useful only when real purchases are compared with it. Daily Loan - Money Tracker gives that comparison a central role instead of treating expense notes as an afterthought.
In my experience, the strongest use is a short entry routine. After paying for groceries, transport, lunch, or a household item, I would record the amount while the reason was still clear. Later, I could look at the running picture and ask a more practical question than “Where did my money go?”: “Which type of spending is using more of my plan than expected?” That small change in wording makes the tracker more actionable.
The app is listed in the finance category and is free to use. It is also marked for Everyone, which makes the basic idea approachable for a broad audience, including someone who has never used a budgeting app before. Its public listing shows a 4.5 average from around 7.4 thousand ratings and more than 1 million installs, so it has attracted a substantial audience despite its narrow presentation.
One detail I would keep in mind is the developer name, SUMMIT CITY PROSTHETICS & ORTHOTICS, INC. That is unusual for a personal finance product. It does not automatically make the app unusable, but it is a reason for me to be careful about entering sensitive information and to treat the app as a manual organizer rather than a place for banking credentials or confidential documents.
Why manual recording can be useful
Automatic bank connections are convenient, but they can also make spending feel invisible. A transaction arrives in a feed, receives an imperfect label, and gets forgotten. Manual tracking adds a moment of attention. That extra step is a weakness when I am in a hurry, but it can be a strength when the goal is to notice patterns rather than merely collect transactions.
This is especially relevant for cash purchases, informal loans, shared household costs, and small recurring payments that do not always appear neatly in one financial account. A person lending money to a friend can use a simple daily record to remember the amount and keep it separate from ordinary shopping. A student can note small purchases that would otherwise seem too minor to matter. Several “minor” entries often explain a budget problem better than one large purchase.
The trade-off is straightforward: the quality of the picture depends on the quality of the entries. I would not expect the app to rescue a budget that is updated only occasionally. The practical solution is to make the habit almost automatic—open the tracker after a purchase, enter the amount, and use a consistent description. The fewer decisions I make at that moment, the more likely I am to keep doing it.
A realistic way to use it during a normal week
Imagine a week in which I receive money on Monday, pay a loan installment, buy groceries, cover commuting costs, and make several inexpensive purchases during work breaks. On Monday, I would first establish the amount available for the week and note the loan-related payment separately from flexible spending. That separation matters because a fixed obligation should not be mistaken for money that can be freely reduced later.
Each day, I would add purchases soon after making them. I would avoid vague labels such as “stuff” and instead use descriptions that will still make sense several days later. “Lunch near work” is more useful than “food” if I am trying to understand why the weekly allowance is shrinking. At the end of the week, I would review the entries together and adjust the next week’s plan based on actual behavior, not an idealized estimate.
This workflow also helps with irregular income. If my available money changes from week to week, a monthly budget can create false confidence. A shorter planning cycle lets me set a realistic limit from what I have now. I would still keep a separate note of larger upcoming obligations, because a daily tracker should not be the only place where important payment dates live.
For shared expenses, I would record the full purchase and add a clear reminder in the description about the portion another person owes. I would not treat that amount as recovered until it actually returned. This is a small but important accounting habit: expected reimbursement is not the same as money currently available.
Three habits that make the tracker more useful
- Record timing, not just totals. Entering a purchase on the day it happens makes it easier to connect spending with a situation, such as a busy commute or an unplanned evening out. That context can reveal a trigger that a monthly total hides.
- Separate obligations from choices. Loan payments, rent, and essential bills should be mentally distinct from flexible spending. Even if the app presents them within one money picture, I would use consistent wording so I can tell which costs are negotiable.
- Review before the budget breaks. Waiting until the end of a month turns the tracker into a history book. A brief midweek check gives me time to change the next few purchases while the information can still influence behavior.
These are not flashy tricks, but they are where a manual finance app earns its place. The important feature is not merely the ability to type in an expense. It is the feedback loop between an entry, a budget decision, and the next purchase.
Where it sits beside common alternatives
Compared with a notebook, the app offers a more dedicated space for financial entries and makes the habit easier to keep separate from ordinary notes. A notebook remains better for people who want complete freedom over layout or who dislike using a phone for every purchase. The app is more convenient when I want my daily records and budget thinking in one focused location.
Compared with a spreadsheet, Daily Loan - Money Tracker should feel less demanding for basic tracking. A spreadsheet can handle custom formulas, detailed debt schedules, shared editing, and long-term analysis, but it requires more setup and maintenance. I would choose a spreadsheet for a household with complicated categories or multiple repayment scenarios. I would choose this app when the priority is getting an entry recorded quickly without building a financial model.
Compared with a bank’s own spending dashboard, a manual tracker can include cash and informal transactions that banking data misses. The bank dashboard is usually the better source for confirming actual account activity. I would use both only if I were disciplined enough to avoid double-counting. The app works best as a deliberate planning layer, not as a substitute for checking balances and statements through the financial institution itself.
Compared with a feature-heavy budgeting service, the appeal here is restraint. Someone who wants detailed reports, automatic categorization, account synchronization, or a multi-person financial workspace may find a specialized alternative more suitable. Someone who feels overwhelmed by those systems may appreciate a smaller routine. The right choice depends less on the category label and more on whether I will consistently use the method.
Important limits before making it your financial home
The first limitation is the burden of manual accuracy. If I forget several purchases, the budget can look healthier than reality. That is not a minor flaw; it changes the meaning of every later decision. I would recommend starting with a narrow goal, such as tracking discretionary spending or loan-related cash flow, instead of trying to reconstruct an entire financial life immediately.
The second is the risk of overinterpreting a simple record. A list of expenses can show what happened, but it does not automatically explain whether a purchase was necessary, whether a bill is due soon, or whether a debt is becoming unaffordable. I would still keep official statements, payment confirmations, and any formal loan documents outside the app.
Privacy also deserves practical attention. Because the developer identity is not what I would normally associate with a finance tracker, I would avoid entering account passwords, full card details, identity numbers, or anything that could create serious harm if exposed. I would use ordinary descriptions and amounts only, then confirm that the app behaves as expected on my device before building a long history inside it.
The listing shows a current version of 1.0.6 and support for Android 7.0 or later. That makes compatibility fairly broad for older Android devices, but I would still test the experience on the particular phone I plan to use. A finance routine is only dependable if the app opens reliably and lets me make an entry without friction.
Another limitation is that a tracker can encourage false precision. Writing down every purchase may create the feeling that money is under control even when income is too low for the obligations involved. I would use the records to make decisions, not to replace an honest assessment of affordability. If a loan payment leaves no room for essentials, better categorization alone will not solve the problem.
Who is most likely to benefit
I think this app is a good fit for a beginner who wants a simple daily money habit, a cash user whose spending is poorly represented by bank dashboards, or someone trying to keep ordinary expenses distinct from loan-related payments. It can also suit a person who has tried elaborate budgeting software and abandoned it because there were too many screens, categories, or setup decisions.
It is less suitable for a user who expects automatic account imports, professional debt-management guidance, advanced forecasting, or a shared household ledger. I would also skip it as a primary tool if I needed formal records for business accounting. In those situations, a spreadsheet, accounting product, or bank-connected budgeting service would provide a stronger foundation.
Parents could use the basic approach to teach a teenager how daily purchases affect a limited allowance, while an individual with irregular freelance income could use shorter budget periods rather than pretending every month will look the same. The app’s Everyone age rating supports its approachable character, but age suitability should not be confused with financial suitability: younger users still need guidance about what information is safe to enter.
For someone deciding whether to try it, I would begin with a seven-day experiment. Record every relevant expense, mark loan payments clearly, and review the result before changing the budget. If the process feels quick enough to repeat, the app may become a useful daily checkpoint. If recording feels like a chore or the information needed is more complex than a simple list and plan, moving to a more capable alternative will save time.
My final take on the daily workflow
The real strength of Daily Loan - Money Tracker is the pause it creates between spending and forgetting. Its value comes from turning scattered purchases into a conversation with the budget, particularly when loans, cash, or small daily costs make the overall picture difficult to see. I would recommend it as a focused manual tracker, not as a bank replacement or a complete financial adviser.
The free price lowers the barrier to trying that habit, and the large install base suggests that the straightforward concept has found an audience. Still, I would keep expectations realistic: consistency, careful descriptions, and sensible privacy choices matter more than the app alone. If those conditions fit the way I handle money, this can be a practical companion for daily expense awareness. If I need automation, complex debt planning, or shared financial controls, I would choose a different tool rather than forcing this one to do a job it was not designed to handle.
Pros and Cons
Pros
- Simple interface for tracking daily loan payments
- Helps organize borrowed and lent money in one place
- Useful reminders can reduce missed repayment dates
- Supports quick entry of loan amounts and due dates
- Makes it easier to review outstanding balances
Cons
- May lack advanced budgeting and financial planning tools
- Personal loan data may require careful privacy management
- Features can vary depending on device or app version
- Manual entries may become time-consuming for many loans
- Not a substitute for official banking or lending records
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Daily Loan - Money TrackerSUMMIT CITY PROSTHETICS & ORTHOTICS, INC. | 4.5 | 1,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Daily Loan - Money Tracker used for?
Daily Loan - Money Tracker is designed to help users organize and monitor personal borrowing and repayment information in one place. It can be useful for tracking loans, recording payment amounts, checking outstanding balances, and keeping notes about due dates or lenders. It should be viewed as a budgeting and record-keeping tool, not as a guaranteed source of financial assistance or approved credit.
Does Daily Loan - Money Tracker provide loans or connect users with lenders?
The app’s name may suggest that users can request money, but a money-tracking application is generally intended to record and manage loan information rather than approve or issue loans itself. Before entering personal details or expecting a cash advance, carefully review the app description, permissions, terms, and privacy policy. Availability of lending features, if any, can also vary by country and provider.
Is Daily Loan - Money Tracker safe to use with financial information?
Users should treat any financial-management app carefully, especially when entering loan amounts, repayment schedules, income details, or personal contact information. Before using Daily Loan - Money Tracker, check its requested permissions, developer information, privacy policy, and data-handling practices. Avoid entering banking passwords, card PINs, or unnecessary identity documents unless the app clearly explains why they are required and how they are protected.
Is Daily Loan - Money Tracker free, and are there any additional costs?
The basic download may be free, but the exact pricing model can depend on the version available in the Android or iOS store. Some applications include advertising, optional purchases, premium tools, or subscription plans. Check the store listing and in-app payment screen before confirming anything. If the app presents loan offers, also review interest rates, service charges, late fees, and repayment conditions rather than focusing only on the advertised amount.
What should I check before downloading Daily Loan - Money Tracker?
Before installing the app, confirm that it is published by the expected developer and that the download comes from the official Google Play Store or Apple App Store. Read recent reviews, examine the update history, and compare the permissions with the app’s stated purpose. You should also verify whether it supports your currency and region, works offline if needed, and allows you to export or delete your records.
Advertisements

Download Daily Loan - Money Tracker
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 1.0.6
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.