


Current - Mobile Banking
Advertisements
App Specs
- Version
- 8.15.0
- Updated
- Nov 7, 2026
- Android Version
- 8.0
- Installs
- 5,000,000+
- Developer
- Current
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
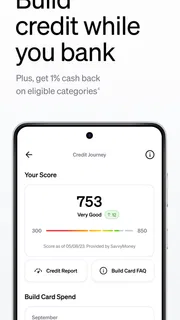
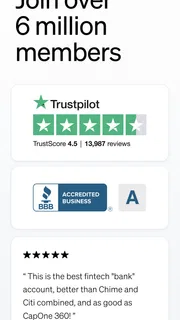
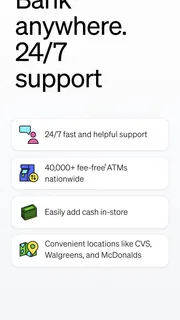
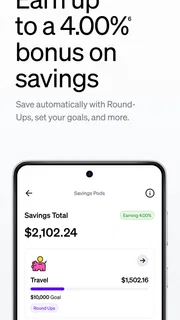
Our Review
 Analysis byUnlimiteds
I judge a finance app not only by what it can do, but by how it behaves when I need it in a hurry. A balance check in a checkout line, a payment update while I’m out, or a savings decision between errands all depend on a phone and a working connection. Current: The Future of Banking is built around managing money on mobile, and its appeal is strongest when that quick access fits the way you already handle everyday spending.
When a connection is part of the task
Banking on a phone can make routine money checks feel immediate, but that convenience depends on being able to reach the service when you need it. I’d treat Current as a useful place to check in during ordinary connected moments, rather than assuming that every action will be available regardless of network conditions. If I were about to rely on an app for a time-sensitive payment or account decision, I’d check it before leaving home instead of waiting until the last possible moment.
That simple habit matters most when plans are moving quickly: checking a balance before meeting friends, reviewing a purchase after tapping to pay, or seeing whether a savings goal still fits the week’s budget. The app’s focus on mobile money management makes those small check-ins a natural part of the day. It is less compelling if you want to do all your financial planning in one long desktop session and rarely reach for your phone.
Useful in the places where spending happens
The everyday setting is where I can see a mobile finance app earning its place. Imagine I’m buying lunch, then picking up groceries on the way home. A spending notification can make those transactions easier to notice while they are still fresh, rather than leaving me to reconstruct the day from memory later. The practical benefit is awareness, not a promise that an alert will prevent every budgeting mistake.
I’d also use a quiet moment on a commute or during a break to look at a savings goal and decide whether it still makes sense. That is a better fit than trying to make a serious financial decision while distracted at a checkout. Small screens encourage short sessions, so I find it useful to know what I want to check before opening the app: a recent purchase, a balance, or the progress of a goal.
What to do when access is interrupted
A dropped connection can turn a simple account check into a frustrating pause. I wouldn’t assume that an action has gone through just because I tapped a button before the screen stopped responding. When something important appears uncertain, I’d reconnect, reopen the app, and verify the current status before trying again. That extra check can help avoid repeating a transaction or making a decision based on an old screen.
This is one reason I would keep another way to handle urgent money matters available, especially when travelling or dealing with a payment that cannot wait. Current can be a convenient daily companion without being the only route I depend on in every situation. The distinction is sensible for any connected finance app: use it for routine visibility, but give important actions enough time to confirm.
Making mobile data work for you
Frequent checks and notifications can be useful, but they can also turn money management into a stream of interruptions. I’d keep alerts focused on the information that genuinely helps me notice activity, then open the app when I have time to interpret what I’m seeing. A notification is a prompt to review a purchase, not a complete picture of spending or a substitute for checking the account itself.
If I’m trying to limit phone use or mobile data, I’d make deliberate check-ins part of a routine instead of refreshing the app repeatedly. For example, I could look over recent spending after lunch and revisit savings progress at the end of the week. The trade-off is straightforward: fewer interruptions can make the experience calmer, while less frequent reviews mean I may spot a pattern later.
A more personal way to manage everyday money
If you've ever found yourself daydreaming about a banking app that feels as seamless as scrolling through your favorite social media feed, then hold on to your smartphone because Current: The Future of Banking is here to shake things up. This app has been making waves in the finance world, and I had to see what the fuss was all about. Let’s dive into what makes this app tick and why it might be your next financial sidekick.
First Impressions: A User-Friendly Experience
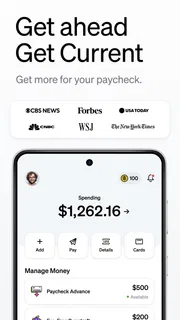
From the moment I downloaded Current, I was immediately impressed by its sleek design and intuitive user interface. The app opens up to a dashboard that is not only visually appealing but also incredibly easy to navigate. Whether you're tech-savvy or someone who prefers simplicity, Current’s layout makes managing your finances feel like a breeze. It's like having a bank in your pocket that you actually enjoy interacting with!
That easy-to-scan layout is most helpful when I have a specific question, not when I expect a polished dashboard to do my thinking for me. Before relying on a mobile account as my main view of money, I’d make a habit of checking that I can find the figures and activity I care about without hunting through menus. A friendly first screen is valuable only if it helps me answer practical questions quickly.
Features That Matter
Now, let’s talk features because, honestly, this app is packed with them. One of the standout aspects is its real-time notifications. You get instant updates on your spending, which feels like having a personal accountant with you 24/7. No more surprises when you check your balance at the end of the month!
Current also offers a feature that rounds up your purchases to the nearest dollar and moves the extra cents into a savings pod. It’s a small gesture with a big impact, especially if you’re trying to save without even thinking about it. Plus, the ability to set savings goals within the app is a game-changer for anyone looking to make their financial dreams a reality.
I see round-ups as a way to make saving feel automatic, not as a shortcut to a large goal. The useful move is to connect a pod to something concrete—such as a future purchase or a buffer for an irregular expense—and check whether the pace suits your budget. If cash is tight, even small transfers deserve attention; an automatic habit should still reflect what I can comfortably set aside.
For someone paid on an uneven schedule, a goal can also serve as a visual reminder rather than a rigid promise. I’d choose a modest target, review it after a pay cycle, and adjust if essential expenses have changed. That keeps the feature practical: it supports a decision I make, rather than replacing the decision with a feel-good number on a screen.
Security and Support
In today’s digital age, security is paramount, and Current doesn’t skimp on this aspect. With robust encryption and biometric login options, your financial data is locked down tighter than Fort Knox. And should you run into any issues, their customer support team is just a chat away, ready to assist with any queries or concerns you might have.
Even with convenient sign-in and help options, I would still use the same care I bring to any financial account: protect access to my phone, avoid sharing sensitive details casually, and read prompts before confirming an action. If a payment or account issue is urgent, I’d contact support with a clear description of what happened and when, rather than repeatedly retrying an uncertain step. That makes a support conversation more useful and reduces the chance of creating confusion.
The Social Side of Banking
One of the unique features I found intriguing is the app’s social aspect. You can connect with friends and share expenses, making it easier to split bills or even plan a group savings goal. It adds a community feel to banking, which is something I never thought I’d say!
For a shared meal or a group trip, this can make the money conversation less awkward by giving everyone a common point of reference. I’d still agree on the amount and timing outside the app before treating a shared expense as settled. Friends may use different banking tools or have different comfort levels about linking money matters socially, so the feature works best when participation is voluntary and expectations are clear.
Who will get the most from it
I can see Current fitting people who like to manage day-to-day money from a phone, want spending activity to stay visible, and find small savings routines easier than occasional big transfers. The combination of notifications, round-ups, savings pods, and goals gives a practical set of prompts for someone who wants to build habits while handling ordinary purchases. Its social tools may also appeal to friends who regularly split costs and prefer keeping those plans together with their personal money tasks.
It is less suitable for someone who wants a primarily desktop-based system, dislikes account activity notifications, or needs a single tool for detailed financial planning across multiple accounts. A traditional bank app may be a better fit if the priority is staying with an existing banking setup, while a dedicated budgeting tool may suit someone who wants more deliberate category-by-category planning. I would compare the everyday workflow, not just the feature names: which option makes it easiest to review transactions, keep savings separate, and resolve a problem?
Current is a finance app from Current, and it is free to download. It has a 4.5 average from around 173,000 ratings, with more than 5 million installs; its age rating is Everyone. The app first appeared on May 5, 2017, and version 7.43.0 is listed for devices running Android 8.0 or later. Those details make it easy to place in the mobile finance landscape, but they do not answer the more personal question of whether its approach suits your habits.
What I would check before making it a routine
Before moving daily money management into any app, I’d test the parts I expect to use most: finding recent activity, understanding how a savings goal is progressing, and locating the right help channel. I’d also decide which alerts are useful enough to keep turned on. That small setup exercise can reveal whether the app supports my routine or simply adds another place to check.
I’d be especially thoughtful about whether automatic round-ups fit my spending pattern. They may feel painless when purchases are frequent and the amounts are modest, but they can be less predictable than a planned transfer. If I prefer exact control, I may be better off setting a savings amount manually; if I value gentle, repeated nudges, round-ups can make saving easier to remember. Neither approach is automatically better—the right choice depends on how steady my cash flow is and how closely I want to supervise it.
Another question is how much social interaction belongs in a finance app. I’d use shared expense features for a specific group task, such as coordinating a meal or trip, rather than assuming every friend wants to connect money accounts or savings plans. Keeping the purpose narrow helps preserve privacy and avoids turning a convenient tool into a source of social pressure.
Current is also not a replacement for paying attention. A notification can help me catch a transaction, but it cannot tell me whether that purchase fits my priorities. A savings pod can make progress visible, but I still need to choose a realistic goal and revisit it when circumstances change. The app’s best role is as a convenient layer for staying aware and building small routines, not as an automatic answer to every financial decision.
My connectivity verdict
For me, the strongest case for Current is the way it brings spending awareness and small saving actions into the same mobile routine. Notifications can make recent activity easier to notice, and round-ups and goals offer a low-effort starting point for saving. The social angle gives it another use for shared plans, provided everyone involved is comfortable with that approach.
The trade-off is that a phone-centered finance routine depends on access, attention, and sensible expectations. I would not treat an unanswered screen as proof that an action failed or succeeded, and I would keep a backup route for urgent needs. I’d also choose a different kind of app if I wanted deep budgeting controls, a desktop-first workflow, or fewer digital prompts.
Overall, I’d recommend Current to someone who wants everyday banking tasks to feel approachable and who will use its mobile tools thoughtfully. I would not recommend choosing it just because the interface looks modern or because automated saving sounds effortless. If its mix of activity alerts, savings goals, round-ups, and shared expenses matches the way you actually handle money, it is worth considering; if not, a simpler bank app or a more hands-on budgeting tool may serve you better.
Pros and Cons
Pros
- User-friendly interface for easy navigation
- Quick setup process saves time
- No fees on international money transfers
- Real-time transaction notifications
- Supports multiple currencies seamlessly
Cons
- Limited customer support options
- Requires stable internet connection
- Not available in all countries
- Some features hidden behind paywall
- Occasional bugs with transaction history
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Current - Mobile BankingCurrent | 4.4 | 5,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Current: The Future of Banking?
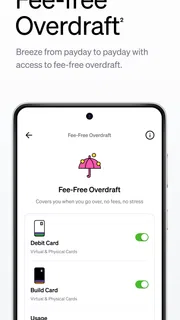
Current: The Future of Banking is a modern mobile banking app designed to simplify financial management for users. It offers features such as instant spending notifications, budgeting tools, and fee-free overdrafts, all while providing a user-friendly interface. The app aims to make banking more accessible and efficient for everyone.
How secure is the Current app?
The Current app prioritizes user security with bank-level encryption, ensuring all financial data is kept safe. Additionally, it offers features like two-factor authentication and biometric login options, such as fingerprint or facial recognition, to further protect user accounts from unauthorized access.
Are there any fees associated with using Current?
Current offers a free basic account with no monthly fees, but it also provides premium accounts with additional features for a monthly subscription. Users can choose the plan that best fits their needs, with the assurance that there are no hidden fees or charges for basic banking transactions.
What features make Current different from traditional banks?
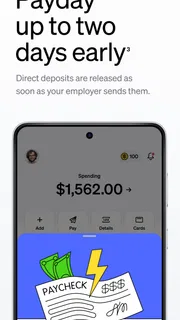
Current stands out from traditional banks with its innovative features like real-time spending notifications, instant money transfers, and early access to direct deposit funds. It also provides tools for budgeting and saving, making it easier for users to manage their finances directly from their smartphones.
Can I deposit checks with the Current app?
Yes, you can deposit checks using the Current app. It offers a mobile check deposit feature that allows users to take a picture of their checks and deposit them directly into their account, eliminating the need to visit a bank branch. This feature adds to the convenience and efficiency of managing your finances on the go.
Advertisements

Download Current - Mobile Banking
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 8.15.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.