


Cleo AI: Cash Advance & Money
Advertisements
App Specs
- Version
- 3.73.0
- Updated
- Nov 7, 2026
- Android Version
- 10
- Installs
- 5,000,000+
- Developer
- Cleo AI
- Category
- Finance
- Content Rating
- Teen
- Price
- Free
Screenshots
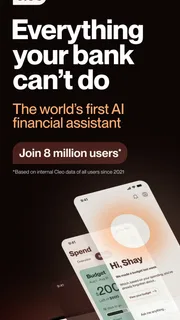
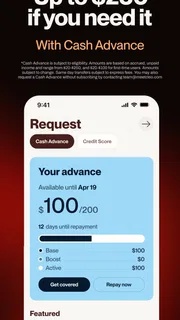
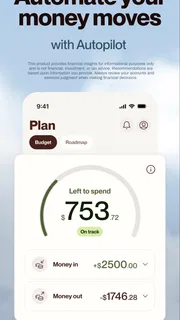
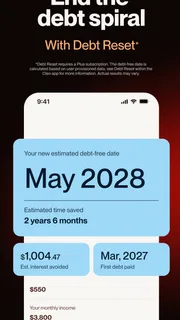
Our Review
 Analysis byUnlimiteds
I judge a money app by whether it helps me make a better decision on an ordinary Tuesday, not just whether it looks clever on a good day. Cleo AI: Cash advance & Credit is aimed at people who want budgeting, spending awareness, savings support, credit guidance, and access to a cash advance in one place. That broad mix is useful, but it also means the right question is whether you want an all-round money companion or a focused tool for one specific task.
Start with the job you need done
If your main problem is losing track of small purchases, the appeal is straightforward: seeing spending grouped into categories can make a vague sense of “where did my money go?” more concrete. If you want to improve your credit, the credit guidance may be more relevant than the budgeting prompts. And if you are considering an advance, treat that as a separate borrowing decision rather than as another budgeting feature. A short-term cash boost can solve a timing problem, but it does not replace a plan for the next pay cycle.
I would also decide in advance what you expect the app to do with your attention. Cleo’s conversational, playful style can make money feel less intimidating, but some people prefer a quiet dashboard and direct figures. If jokes and nudges help you check in regularly, that tone is an advantage. If you find chatty prompts distracting, or would rather review a spreadsheet without commentary, a more conventional budgeting app may suit you better.
Where an all-in-one approach helps
The useful idea here is the connection between day-to-day spending and longer-term goals. A budget is easier to act on when you can relate it to a real choice, such as whether there is room for a planned purchase or whether a frequent convenience expense is crowding out savings. Credit information adds another perspective: it can help turn an abstract score into a topic you can review and work on, rather than something you only think about when applying for credit.
That combination may be especially handy if you are just starting to organize your finances and do not yet have a routine. Instead of choosing one specialist app for expenses, another for credit, and a separate method for saving, you can begin with a single place to check several parts of your money picture. The trade-off is that a broad app may not offer the depth or presentation you want from a dedicated credit-monitoring service or a detailed budgeting system.
A practical way to use it is to make a brief weekly review part of an existing habit. I might check the categories after paying bills, note one spending pattern worth changing, and choose a realistic amount to set aside before the next check-in. That is more actionable than opening an app repeatedly without a question in mind. For credit guidance, I would focus on one suggested habit at a time and give it room to become routine, rather than expecting an instant change from checking a score.
When another kind of tool is a better fit
People who already keep a dependable budget in a notebook, spreadsheet, or banking app may not gain much from adding another place to monitor their money. If your current method tells you what you need and you actually use it, switching for a livelier interface is not automatically an improvement. A focused savings tool may be preferable if your only goal is to build a regular saving habit, while a specialist credit service may be a better choice if you want credit information to be the central feature.
The cash advance deserves particular care. It can be tempting to treat available borrowing as part of normal income, especially when a tight week keeps recurring. I would reserve it for a genuine shortfall with a clear repayment plan, and look at the next month’s budget before accepting an advance. If the same gap appears every pay cycle, the underlying issue needs attention; repeatedly borrowing can make the next cycle feel tighter rather than easier. Anyone who prefers not to borrow, or who cannot confidently plan repayment, should use the budgeting and credit tools without relying on the advance.
Make the first check-in useful
Before relying on any money app, I like to decide what information I am comfortable reviewing in it and what I want to learn from the first few check-ins. Start with a simple question: which spending category is hardest to predict, or what financial habit would make the next month feel more manageable? That gives the app a purpose and makes its prompts easier to judge. If the categories do not reflect how you think about your spending, use them as clues rather than as a perfect account of your priorities.
It is also worth separating observation from action. A spending breakdown can show a pattern, but it cannot decide whether a purchase was worthwhile or whether a budget is realistic for your circumstances. I would use the information to choose one small adjustment, then see whether it is sustainable. A budget that leaves no room for ordinary surprises is likely to be abandoned, even if it looks tidy on screen.
For a realistic example, imagine an unexpected household expense landing shortly before payday. I would first check upcoming bills and the money already committed, then decide whether the expense can be covered by changing discretionary spending or whether an advance is genuinely necessary. If I did use one, I would note how repayment affects the following pay period. That sequence matters: it turns a fast fix into a deliberate choice and helps prevent the same shortfall from being invisible next time.
Meet Cleo, Your Financial Buddy
First off, let’s talk about what Cleo AI really is. Imagine having a sassy financial assistant that gives you a heads-up on your spending habits, but doesn’t make you feel guilty about that extra coffee you bought this morning. That's Cleo! This AI-driven app is designed to help you track your spending, manage budgets, and even offer cash advances when you’re in a pinch. It’s like having a friend who’s really good with money.
Simplifying Budgeting
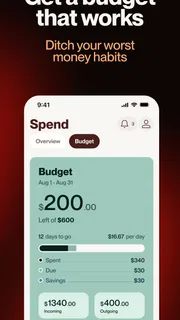
One of the coolest features I found is the budgeting tool. Cleo breaks down your spending into categories, which makes it super easy to see where your money is going. Are you spending too much on takeout? Cleo will let you know with a cheeky nudge. It’s like having a mini financial advisor in your pocket, minus the hefty fees.
For me, the most useful way to read those categories is as a prompt to ask a better question, not as a verdict. If takeout spending looks high, I would compare it with the weeks when I was busiest or had fewer groceries at home before deciding what to change. A category view can point to a pattern, but the reason behind it is still yours to work out. That small distinction can keep budgeting from turning into guilt over every ordinary purchase.
It can also help to use categories for planning ahead, not just reviewing what has already happened. If a regular expense is likely to recur, I would account for it before treating the remaining balance as freely available. Then, when an unexpected cost appears, I can tell whether it is truly unusual or simply something I failed to plan for. This kind of check is especially useful for people whose income or weekly spending varies, because a single snapshot can otherwise give a misleading sense of how much room they have.
Cash Advance to the Rescue
We’ve all been there – it’s a week before payday, and your bank account balance is giving you anxiety. Enter Cleo’s cash advance feature. You can get an advance up to $100, which can be a lifesaver for those unexpected expenses. What’s great is that it’s interest-free if you pay it back on time. It’s like borrowing money from a friend who trusts you to pay it back.
I would not make the advance the first thing I reach for when a balance looks low. First, I would check whether a bill is due before payday, whether shifting a nonessential purchase would cover the gap, and what the repayment timing means for the next stretch of expenses. The advance can be useful for a one-off timing mismatch, but the key is to know what happens after the immediate pressure passes. If repaying it would create another shortfall, it is not really solving the problem.
One practical habit is to write down the reason for using an advance and revisit it during the next budget check. Was it an unusual expense, or did several smaller costs accumulate because they were not visible? That reflection makes the feature more useful as an emergency option and less likely to become a regular bridge between paydays. I would also read the current in-app terms carefully before accepting, since any borrowing decision should be based on the conditions shown at that moment, not on an assumption carried over from an earlier use.
Credit Score Insights
Worried about your credit score? Cleo’s got your back with its credit score insights. It breaks down your credit report in a way that’s easy to understand, so you know exactly what’s helping or hurting your score. Plus, it offers tips on how to boost your credit, which is invaluable if you’re looking to make a big purchase like a car or a house.
I would treat this as an approachable starting point, especially if credit language usually feels opaque. A clear explanation can help you understand what to pay attention to and what questions to ask before a major application. Still, anyone making a consequential borrowing decision should check the relevant details with the lender or a dedicated credit resource as well. A simplified explanation is helpful for orientation, but it should not be mistaken for a guarantee about how a future application will be assessed.
The most useful follow-through is to turn a tip into a habit you can maintain. Rather than checking a score repeatedly and hoping for a quick movement, I would choose a practical action, keep it consistent, and return to the guidance later. That makes credit improvement a process rather than a series of anxious refreshes. If your priority is detailed credit monitoring above all else, a specialist option may give you a more focused experience than an app whose attention is shared across budgeting and borrowing.
Who will get the most from it
Cleo is likely to make the most sense for someone who wants a friendly nudge to look at spending and is curious about credit, but does not want to begin with a complex financial setup. It can also suit a person who benefits from conversational prompts: being asked to think about a pattern may feel more approachable than opening a blank spreadsheet. The best results will come from treating it as a companion to your own decisions, not as an authority that can judge what you should spend.
I would be more cautious if you need exact, highly customizable planning, already have a system you trust, or want to avoid borrowing altogether. The app’s mix of tools is not a reason to use every feature. You can focus on budgeting and credit information while leaving the advance aside, or decide that a focused tool better matches your needs. That flexibility in how you approach it matters more than trying to turn every feature into part of a daily routine.
As a finance app from Cleo AI, it is free to download, has a Teen content rating, and has been available since February 21, 2019. It has a 4.4 average from around 107 thousand ratings, alongside roughly 35 thousand written reviews, and has passed over one million installs. Version 3.20.0 requires Android 10 or later. Those figures suggest that many people have tried it, but they do not tell me whether its tone or approach will fit your own habits; that is something to judge through the way you actually use it.
Overall, using Cleo AI feels like having a smart, witty buddy who’s always looking out for your best financial interests. It’s packed with features that make managing money less of a chore and more of a fun challenge. Whether you need to stick to a budget, get a quick cash boost, or keep tabs on your credit score, Cleo’s got you covered.
So, if you’re tired of feeling overwhelmed by your finances, give Cleo AI: Cash advance & Credit a try. It just might be the financial wingman you’ve been waiting for!
Pros and Cons
Pros
- Instant cash advance feature available
- User-friendly budgeting tools
- No hidden fees or interest charges
- Customizable spending alerts
- Secure and private data handling
Cons
- Limited to UK and US users only
- Requires access to bank account
- Advanced features need paid subscription
- Occasional app glitches reported
- Not suitable for all financial needs
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Cleo AI: Cash Advance & MoneyCleo AI | 4.7 | 5,000,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Cleo AI and how does it work?
Cleo AI is a financial assistant app designed to help users manage their finances with ease. It provides insights into spending habits, offers budgeting tools, and even gives cash advances if needed. The app connects to your bank accounts securely, analyzes your spending patterns, and provides personalized advice to help you improve your financial health. Cleo also offers a fun, interactive chat interface, making financial management more engaging.
Is Cleo AI safe to use for my banking information?
Yes, Cleo AI prioritizes user security and uses bank-level encryption to protect your information. It connects to your bank accounts via secure, read-only access, ensuring that your data is safe and cannot be altered. Furthermore, Cleo does not store your login information, providing an additional layer of security for users concerned about data privacy.
Can Cleo AI help improve my credit score?
While Cleo AI offers features like cash advances and spending insights, it is primarily a financial assistant app and not a credit repair service. However, by helping you manage your spending and budget more effectively, Cleo can indirectly aid in improving your credit score if you use its tools to avoid overspending and ensure timely payments. Users looking for direct credit score improvement should seek specialized services.
What are the eligibility criteria for obtaining a cash advance with Cleo AI?
To be eligible for a cash advance with Cleo AI, users must have an active bank account linked to the app and a history of regular income deposits. Cleo evaluates your financial behavior and income patterns to determine eligibility and the amount you can borrow. It is important to note that Cleo’s cash advance feature is designed to help with short-term financial needs and should not be relied upon for long-term financial planning.
Does Cleo AI charge any fees for its services?
Cleo AI offers a free version with basic features, but it also has a premium subscription known as Cleo Plus, which includes additional features like cash advances and enhanced budgeting tools. While the basic app is free, subscribing to Cleo Plus incurs a monthly fee. It’s advisable to review the features of both versions to determine which best suits your financial management needs before making a decision.
Advertisements

Download Cleo AI: Cash Advance & Money
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 3.73.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.