


Cashli: Cash Advance & Rewards
Cashli Funds
Advertisements
App Specs
- Version
- 1.0.19
- Updated
- Nov 6, 2026
- Android Version
- 8.0
- Installs
- 100,000+
- Developer
- Cashli Funds
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
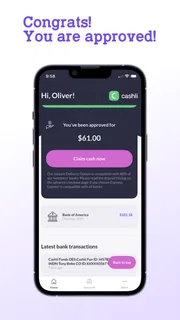
Our Review
 Analysis byUnlimiteds
I approached Cashli: Cash Advance & Rewards as a finance app for people who need to understand its practical value before relying on it. Its central promise is straightforward: it is designed to help users access a small cash advance, while also presenting rewards as part of the experience. That makes it different from a normal budgeting app, where the main job is usually tracking spending, setting goals, or organizing bills.
The first thing I would tell a friend is to treat Cashli as a short-term financial tool, not as a replacement for regular income. The idea of getting help with an immediate expense can be useful, but the important question is whether the app fits the specific situation. A quick advance may solve a timing problem; it does not automatically solve an ongoing money problem. That distinction shaped my view of the app more than its simple store summary.
What Cashli actually offers at no purchase price
Cashli is a free finance app from Cashli Funds, with an Everyone content rating. It was released on July 18, 2023, and the current version is 1.0.19. It runs on Android devices using version 8.0 or later, so it remains accessible to people using older supported phones rather than requiring a recent device.
The word “free” matters here, but it needs to be interpreted carefully. It tells me that downloading the app does not require an upfront purchase. It does not, by itself, tell me that every financial transaction connected with an advance is cost-free. For any borrowing product, I would read the in-app terms closely before accepting an offer, paying particular attention to repayment timing, eligibility conditions, possible fees, and what happens if repayment is late.
That is not a criticism unique to Cashli. It is simply the right way to evaluate any app that may connect users with early access to money. A free download and free borrowing are not the same thing. If someone installs it expecting the app itself to function like a no-cost emergency fund, that expectation could lead to a poor decision.
Cashli has attracted more than 100 thousand installs, and its average rating is 4.1 from roughly 4.9 thousand ratings. Those figures suggest that the app has reached a meaningful audience and that user reactions are generally positive, but they should not replace personal checking. A rating cannot tell me whether the service will suit my income pattern, eligibility, repayment date, or financial habits.
How I would check the cost before accepting anything
I would begin by installing the app only from the official mobile store and reviewing the screens that explain the offer. I would not rush through registration simply because the amount appears small. The useful question is not only “How much can I receive?” but also “How much must I repay, and when?” If the answer is unclear, I would stop before confirming.
I would also separate three different kinds of value. First, there is the value of free access to the app itself. Second, there is the potential value of receiving money earlier than a normal payday. Third, there is the value of any rewards activity. These are related, but they should not be mentally combined into one guaranteed benefit.
For example, a reward may sound attractive while still requiring time, participation, or conditions that do not suit me. Likewise, an advance may be useful while still carrying obligations that make it expensive compared with waiting for regular income. The safest habit is to judge the repayment commitment before counting the advance as help.
Where the app can deliver practical value
The strongest use case is a short gap between an immediate bill and an expected payment. Imagine that I have a necessary household expense due today, while my normal income arrives shortly afterward. If Cashli presents an offer I qualify for and the repayment terms fit my next pay cycle, the app could be more convenient than asking a friend, visiting a branch, or applying for a larger traditional loan.
That convenience is especially relevant when the amount needed is modest. A conventional personal loan may involve more paperwork, a longer process, or a borrowing amount larger than the problem requires. Cashli’s appeal is the possibility of handling a smaller, time-sensitive need through a phone rather than beginning a full lending application.
Another useful angle is visibility. An app-based process can put the offer, repayment information, and account activity in one place. That may be easier to revisit than relying on memory or scattered messages. I would still save the important repayment details separately, because a finance app should support my records rather than become the only place where I know what I owe.
The rewards side may add interest for users who like earning benefits through app activity. However, I would consider it secondary. Rewards should be treated as an extra possibility, not as a reason to borrow money or spend more time than the benefit is worth. If completing an activity encourages unnecessary purchases, subscriptions, or distractions, the apparent reward may have little real value.
Three practical habits that make the experience safer
My first habit would be to calculate the repayment from money that is already expected, not money I hope to earn. If the plan depends on overtime, a future sale, or an uncertain payment, I would regard the advance as risky. A short-term product works best when the repayment source and date are already clear.
Second, I would use Cashli for a defined need rather than keeping it available as a permanent spending buffer. Before requesting anything, I would write down the exact bill and the exact amount required. This prevents a small emergency solution from turning into extra discretionary spending.
Third, I would compare the complete obligation with ordinary alternatives. If waiting a few days solves the problem without a charge, waiting may be the better financial choice. If a trusted person can help without creating a complicated repayment arrangement, that may also be preferable. Cashli becomes more compelling when speed and convenience genuinely matter and the terms remain manageable.
The trade-offs behind quick access to money
The main trade-off is convenience versus commitment. A fast mobile process can feel simple because it removes friction at the moment I need help. But the repayment obligation remains real after the immediate problem has disappeared. This is why I would never judge the app only by how quickly it presents an option.
There is also a trade-off between flexibility and predictability. A traditional bank product may feel slower, but it can provide clearer documentation and a more familiar repayment structure. Cashli may be more attractive for a small, urgent gap, while a bank or credit union could be better for a planned expense that requires a larger amount or a longer repayment period.
The rewards concept introduces another decision. Rewards can make an app feel more engaging, but engagement is not the same as financial improvement. I would ask whether the activity helps my situation or merely gives me another reason to open the app. For someone trying to reduce spending, a reward system could be less useful than a plain budgeting tool that keeps attention on expenses.
I would also avoid assuming that an offer is available simply because the app is installed. Access to a financial product can depend on individual circumstances and the app’s own evaluation process. Since eligibility is personal, I would install Cashli to inspect the actual offer and terms rather than building a plan around a promised amount.
Who is most likely to get value from Cashli?
Cashli makes the most sense for an adult who has a temporary cash-flow mismatch, understands the repayment obligation, and wants to manage the process from a phone. It may suit someone who needs a modest amount for a necessary expense and prefers a digital option over a traditional application.
It can also appeal to users who want to explore a finance app that combines cash-advance access with rewards in one place. The free download lowers the barrier to evaluating the service, provided the user reads every relevant screen before accepting money or participating in an offer.
I would be more cautious if the user already relies on advances to cover ordinary bills every pay period. In that case, the app may ease today’s pressure while leaving the underlying shortfall unchanged. A spending plan, income review, debt counselor, or a more structured financial product could offer better long-term value.
I would also suggest skipping it if the repayment date is uncertain, if the user dislikes checking financial terms carefully, or if a free alternative can solve the problem without creating a new obligation. Someone looking mainly for expense categorization, investment research, or detailed budgeting may be better served by a dedicated app built around those tasks rather than a cash-advance service.
How it compares with familiar alternatives
Compared with a standard budgeting app, Cashli is focused less on understanding where money goes and more on addressing a short-term access problem. A budgeting app is usually the better choice when the goal is to find recurring leaks, plan bills, or build savings. Cashli is more relevant when the immediate issue is timing rather than tracking.
Compared with a bank loan, its appeal is likely the smaller, more mobile-first experience. A bank may be preferable for larger planned borrowing, established customer support, or a formal repayment structure. The right choice depends on the size and urgency of the need, not on which option feels easiest during a stressful moment.
Compared with asking family or friends, Cashli can provide a more private digital route, but it also means accepting the app’s terms and repayment process. Personal help may be more flexible in some situations, while a formal app can make the obligation clearer. I would choose based on transparency and affordability rather than embarrassment or speed alone.
My final decision for different financial situations
My overall opinion is cautiously positive. Cashli is worth considering as a free-to-install finance app for a specific, short-lived cash gap, especially when I know exactly how repayment will fit into my next income cycle. The combination of cash-advance access and rewards gives it a distinct purpose, and its support for Android 8.0 or later makes it practical for a broad range of devices.
Still, I would not recommend accepting an advance automatically. The app’s real value depends on the offer shown to the individual, the full repayment terms, and whether the need is genuinely temporary. The free price of the download is useful for trying the service, but it should never be confused with a guarantee that borrowing carries no cost.
If I had a one-off emergency, a clear repayment source, and no cheaper solution available, I would inspect Cashli carefully and consider using it. If I faced repeated shortages, wanted a detailed spending planner, or could simply wait for my normal income, I would choose another route. Cashli is best viewed as a carefully checked short-term option, not a substitute for a stable financial plan.
That is the distinction I would share with a friend: install it if you want to evaluate a possible solution and are prepared to read the terms, but do not let the promise of quick access or rewards make the decision for you. Used selectively, it may be convenient. Used routinely, it could mask the problem that needs the most attention.
Pros and Cons
Pros
- Fast application process with clear eligibility information.
- Rewards can provide extra value beyond the cash advance feature.
- Useful repayment reminders help users avoid missing due dates.
- Simple interface makes account details easy to review.
- May help cover small
- unexpected expenses between paychecks.
Cons
- Advance availability and limits may vary by user and location.
- Fees or optional costs can make borrowing more expensive.
- Repayment dates may arrive quickly after receiving an advance.
- Requires access to personal and financial information.
- Not suitable as a long-term solution for recurring money problems.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Cashli: Cash Advance & RewardsCashli Funds | 4.1 | 100,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Cashli: Cash Advance & Rewards, and how does it work?
Cashli: Cash Advance & Rewards is a financial app that may help eligible users access a cash advance while also offering rewards or other money-saving features. After installing it, you generally create an account, provide requested personal and financial information, and review the available offer. Approval, advance amounts, repayment terms, and reward eligibility can vary, so read the in-app details carefully before accepting anything.
Is Cashli a loan, and are there any fees or repayment requirements?
A cash advance is not free money and should not be treated as a long-term borrowing solution. Depending on the offer presented, Cashli may charge a membership fee, service fee, expedited-transfer fee, or another form of cost. Repayment may also be scheduled automatically from a linked bank account. Before proceeding, check the total amount you will repay, the due date, cancellation rules, and any consequences of a failed payment.
Who can use Cashli and what information is required to apply?
Availability normally depends on factors such as your age, location, identity, banking relationship, income, and other eligibility requirements set by the service or its financial partners. During registration, the app may request identifying details, contact information, employment or income information, and permission to connect a bank account. Only submit accurate information, and review the privacy policy to understand how your data is collected and shared.
How do Cashli rewards work, and can they be converted into cash?
Rewards may be earned through qualifying activities, partner offers, referrals, subscriptions, or other actions shown inside the application. The exact value and redemption options can differ, and some rewards may have minimum thresholds, expiration dates, exclusions, or verification requirements. Do not assume that points or promotional credits are equivalent to cash; open the rewards terms in the app to confirm how and when they can be redeemed.
Is Cashli safe to download and use?
Cashli should be downloaded only from the official Google Play Store or Apple App Store, where you can verify the developer, ratings, permissions, and recent user feedback. Financial apps require extra caution because they handle sensitive information. Use a strong, unique password, avoid sharing verification codes, and review account permissions. If the app requests access that seems unrelated to its services, pause and investigate before continuing.
Advertisements

Download Cashli: Cash Advance & Rewards
About This Listing
- Last Checked
- Nov 6, 2026
- Version Reviewed
- 1.0.19
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.