


Cash Advance - No credit Check
Advertisements
App Specs
- Version
- 1.1.3
- Updated
- Nov 7, 2026
- Android Version
- 7.0
- Installs
- 500,000+
- Developer
- D.J. Advance App
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
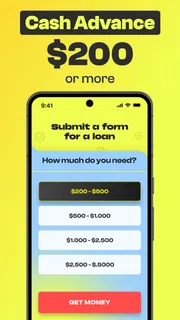
Our Review
 Analysis byUnlimiteds
When an unexpected bill arrives before payday, the hardest part is often not finding a financial app but understanding what it can realistically do for you. Cash Advance - No credit Check is designed around that urgent moment, presenting itself as a finance app for people looking for a cash advance without the usual emphasis on a credit check. I tried to approach it as I would any money app: quickly, cautiously, and with attention to what happens when the phone has a weak connection or the user needs an answer immediately.
My overall impression is that it is best viewed as a starting point for exploring short-term borrowing options, not as a guaranteed source of money. That distinction matters. The app is free to install, its content rating is Everyone, and it is made by D.J. Advance App. It has attracted a 4.7 average from around 35 thousand ratings and more than 500 thousand installs, which suggests that many people have found the format useful enough to keep using or recommending. Still, popularity should not replace careful reading when the subject is borrowing.
How the app fits into a real cash emergency
The most convincing use case is a simple one: I have an essential expense due today, my regular income is expected soon, and I need to review possible ways to bridge the gap. In that situation, the app’s direct focus is more helpful than opening a general budgeting tool filled with charts and long-term planning features. It keeps attention on the immediate question: what kind of cash advance route might be available, and what should I examine before proceeding?
That focus can save time, but it can also encourage rushed decisions. A cash advance is not automatically affordable just because the application process feels easy. I would use the app to gather information, compare the repayment obligation with my next income, and check every condition before accepting anything. If the amount needed is not essential, waiting or using savings is usually the safer choice. If the expense is recurring, the app cannot solve the underlying budget problem by itself.
One useful habit is to write down the exact amount needed before opening the app. I would include only the bill or purchase that cannot wait, rather than choosing a larger amount simply because it appears available. I would also note the date of my next dependable income and leave room for ordinary expenses. This turns the app from an impulse tool into a short decision-making step.
The experience is particularly relevant for someone who does not want a traditional credit-focused route to dominate the first stage of the search. However, the phrase “no credit check” should not be treated as a promise that everyone qualifies or that borrowing has no conditions. Approval, repayment terms, eligibility, and any costs can depend on the specific offer and the provider involved. I would never enter personal information or agree to repayment until those details are visible and understandable.
What I would check before accepting anything
My first check would be the total amount to repay, not merely the amount deposited. Those two figures can differ, and the difference is what affects the real cost. Next, I would look for the repayment date or schedule, any service charges, and what happens if repayment is late. If the wording is unclear, that is a reason to pause rather than a reason to assume the best.
I would also check whether the app is showing an actual offer or directing me toward a separate provider’s application. That distinction changes how I interpret the screen. An informational path can help me compare possibilities, while a completed application may involve additional terms, identity checks, or financial commitments. Reading the transition between the app and any external service is therefore just as important as reading the opening screen.
A less obvious but important tip is to take a moment to record the terms I saw before leaving the flow. I would save the relevant confirmation or write down the repayment amount and date in a secure note. This is useful because urgent borrowing decisions are easy to remember incorrectly, especially when several providers or screens look similar. It also gives me something concrete to compare with later account activity.
Why connectivity changes the experience
This kind of app is closely tied to connectivity. A cash advance search depends on current information, account communication, and possibly a handoff to another service. When the network is stable, the process can feel straightforward: open the app, review the available path, and continue while the relevant pages load. When the signal is weak, the same process becomes more stressful because a delayed page can look like a rejected request or an incomplete submission.
I would avoid starting an application in a moving vehicle, inside a building with unreliable reception, or while switching between mobile data and public Wi-Fi. A stable connection reduces the chance of a page failing during a sensitive step. It also makes it easier to notice whether a button has actually worked, rather than tapping repeatedly and accidentally submitting the same action more than once.
The mobile setting is both the app’s strength and its main practical risk. Most people look for emergency financial help on the phone they already carry, often while standing in a store, waiting for transport, or dealing with a bill notification. That convenience is valuable, but those are also environments where distractions are common. I would not review repayment terms while rushing through a checkout line. I would open the app, read the details in a quiet place, and only then decide whether to continue.
Another useful mobile workflow is to separate research from commitment. On the first pass, I would inspect the available information and note the important figures. On the second pass, after checking my budget, I would return to complete a decision if it still made sense. This small pause helps prevent a fast tap from turning a temporary problem into a repayment obligation I cannot comfortably manage.
What to do when a page fails or the connection drops
If a screen stops loading, I would first check whether the phone still has a reliable connection before refreshing repeatedly. I would avoid assuming that a blank or delayed page means the request failed. Instead, I would wait briefly, confirm whether any confirmation message or notification arrived, and then reopen the relevant section carefully. Repeated submissions are a particular risk in financial workflows because the user may not know which attempt was recorded.
If the app returns to an earlier screen, I would not immediately re-enter sensitive details. I would look for a saved status, confirmation message, or other indication of where the process stopped. If there is no clear status, I would contact the relevant support channel shown in the app or provider flow rather than guessing. The safest recovery method is slower, but it is better than creating duplicate requests or agreeing to terms twice.
I would also keep the app updated when a newer version is offered. The current version is 1.1.3, and using the current release can help avoid problems caused by an older installation. That does not guarantee uninterrupted access, especially when the problem is network-related, but it is a sensible maintenance step for a finance app.
There is a practical distinction between losing connectivity before entering information and losing it after submitting a request. Before submission, I would simply reconnect and restart the review. After submission, I would treat the situation as uncertain until I can verify the outcome. Checking messages, account activity, or the provider’s own status area may be necessary. I would never submit again solely because the first response was slow.
Using it carefully on mobile data
For ordinary browsing, the app is unlikely to be the biggest source of mobile data use, but a financial application can still move between several online pages. If I were using a limited data plan, I would prefer a trusted Wi-Fi connection for the initial review, provided the network is private and secure. I would avoid using an open public network for sensitive financial details, even if it is faster than mobile data.
Data-conscious use is not only about megabytes. It is also about limiting how much personal information I provide and where I provide it. I would read the screen before entering anything, verify that I am still in the expected app or service flow, and avoid sharing details through messages or unofficial channels. If a page unexpectedly asks for information that does not seem relevant to the application, I would stop and investigate.
I would keep notifications under control as well. Emergency borrowing can make every alert feel urgent, but a notification is not a substitute for reading the full terms. I would open messages from a trusted source, compare them with what I saw in the app, and avoid responding to a request that seems inconsistent. This is a small but meaningful safeguard for anyone using a finance app during a stressful situation.
One advanced habit I recommend is maintaining a simple repayment note outside the app. I would record the amount received, the total expected repayment, the due date, and the account from which repayment will come. That note remains useful even if the app is temporarily unavailable or the phone has no connection. It also makes it easier to spot whether the arrangement fits alongside rent, food, transport, and other fixed obligations.
Who will find this useful, and who should skip it?
I think Cash Advance - No credit Check is most useful for an adult who needs to investigate a short-term cash option quickly and is willing to read the conditions carefully. It may suit someone who prefers a focused mobile starting point instead of searching across unrelated finance websites. The free price removes an upfront installation cost, and the Everyone rating makes the app broadly accessible as a piece of software, although borrowing decisions themselves still require adult financial judgment.
I would skip it if I needed a long-term debt solution, a complete budgeting system, investment tools, or detailed credit-building guidance. Someone already struggling to repay existing advances should also be cautious about using another advance to cover the first one. In that situation, a nonprofit debt adviser, a bank conversation, or a revised payment arrangement may be more appropriate than another short-term application.
It is also not the right choice for anyone who expects guaranteed approval, instant money in every situation, or a completely consequence-free alternative to a credit check. The app can make the search more convenient, but it cannot remove the need for eligibility checks, repayment planning, or careful comparison. A conventional bank product may be better when the borrower qualifies for a lower-cost, clearly scheduled option. An employer advance or a negotiated bill extension may be better when those alternatives are available without adding a new debt obligation.
How it compares with familiar alternatives
Compared with a general personal finance app, this one is narrower and more immediate. A budgeting app helps me understand spending patterns and prepare for future shortfalls; Cash Advance - No credit Check is aimed at the moment when I am already looking for a bridge. That makes it faster to approach for an urgent need, but less useful for preventing the same problem next month.
Compared with searching the web manually, a dedicated app can feel less scattered because the purpose is clear from the start. The trade-off is that I still need to understand where the information comes from and whether I am moving into a separate provider’s process. I would not assume that a polished mobile screen means the offer is better than one found through a bank or credit union.
Compared with a traditional bank application, this route may appeal to people who want to explore a cash advance without beginning with the usual credit-oriented experience. A bank may nevertheless be preferable when it offers transparent terms, an existing relationship, and a repayment structure that fits the borrower’s income. The best option depends less on how quickly the first screen appears and more on the complete cost and the ability to repay on time.
My final view on the connected experience
After looking at the app through the lens of real mobile use, I see it as a convenient doorway into short-term cash advance information, with connectivity playing a central role in whether that doorway feels smooth or frustrating. Its focused purpose, free access, and strong user response make it worth considering for someone facing a genuine, temporary cash gap. The developer, D.J. Advance App, has kept the concept easy to understand, and the app’s current release is 1.1.3.
My recommendation comes with a firm condition: use it to investigate, not to switch off your judgment. Work on a stable connection, separate research from acceptance, record the repayment details, and verify what happened if a page fails. Most importantly, compare the total repayment with your next income and essential expenses. The best result is not simply receiving cash quickly; it is choosing an option you can repay without creating a larger problem.
For a short-term search on a phone, I would recommend giving it a careful look. I would not recommend accepting any offer automatically, and I would choose a bank, credit union, employer option, bill extension, or debt-support service instead whenever that alternative is safer or cheaper. Used with that level of caution, Cash Advance - No credit Check can be a practical first step for an urgent decision, but it should remain one part of a broader financial plan rather than the plan itself.
Pros and Cons
Pros
- Quick application process with minimal information required.
- No traditional credit check is promoted for eligible applicants.
- Useful for handling unexpected
- short-term expenses.
- Application is accessible from a mobile device.
- May show loan terms before users accept an offer.
Cons
- Approval is not guaranteed and depends on eligibility requirements.
- Advance fees and interest can make borrowing expensive.
- Repayment deadlines may be short and difficult to manage.
- Availability and terms may vary by state or location.
- Late repayment could lead to additional charges or financial stress.
Advertisements
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Cash Advance - No credit CheckD.J. Advance App | 4.7 | 500,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |
Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Cash Advance - No Credit Check, and how does it work?
Cash Advance - No Credit Check is generally presented as a financial app that may help users explore short-term cash advance options through a mobile device. After entering personal and financial information, the app may display available offers or connect users with third-party lenders. Approval, loan amounts, fees, interest rates, and repayment terms are determined by the lender, not necessarily by the app itself.
Can I really get a cash advance without a credit check?
The phrase “no credit check” should be treated carefully. Some providers may use alternative information, such as income, employment, banking activity, or identity data, instead of relying only on a traditional credit score. However, this does not guarantee approval, and a lender may still perform a credit inquiry. Before accepting an offer, review whether it involves a hard or soft credit check and read the full eligibility requirements.
How much does using the app or accepting a cash advance cost?
Costs vary depending on the lender and the specific offer shown through the app. Possible charges can include origination fees, service fees, membership fees, expedited-transfer fees, interest, or late-payment penalties. Some short-term products can have a high annualized cost even when the amount borrowed is small. Always check the total repayment amount, payment schedule, and all disclosures before agreeing to anything.
What personal information does Cash Advance - No Credit Check require?
A cash advance application may request information such as your name, address, date of birth, phone number, employment details, income, bank account information, and government-issued identification. Because financial data is sensitive, verify the app’s privacy policy, developer identity, permissions, and security practices before submitting details. Avoid providing banking credentials through suspicious links, and download the application only from an official app store or verified source.
What should I know about repayment, approval, and lender communications?
Approval is not guaranteed, and receiving an offer through the app does not mean the funds will arrive immediately. Repayment may be scheduled automatically from your bank account or deducted on a specified date, depending on the lender’s terms. Missing a payment can result in fees, collection activity, or possible credit consequences. Confirm the lender’s contact information, cancellation rights, repayment dates, and customer-support process before accepting an advance.
Advertisements

Download Cash Advance - No credit Check
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 1.1.3
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.