

Acorns Early: Kids Money App
Acorns
Advertisements
App Specs
- Version
- 9.7.0
- Updated
- Nov 6, 2026
- Android Version
- 7.0
- Installs
- 100,000+
- Developer
- Acorns
- Category
- Finance
- Content Rating
- Everyone
- Price
- Free
Screenshots
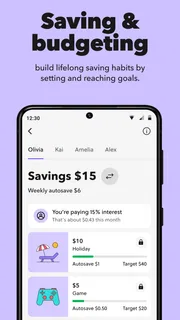
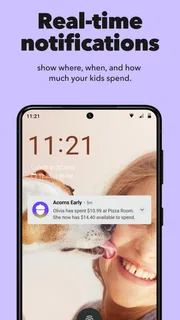
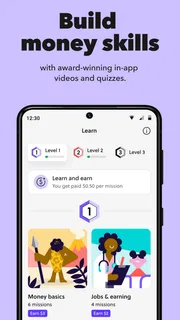
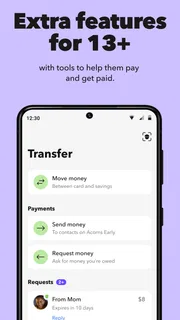
Our Review
 Analysis byUnlimiteds
Teaching children about money is difficult because the lesson has to feel real without turning every allowance into a complicated financial project. After spending time with Acorns Early: Kids Money App, I see it as a gentle bridge between everyday family money habits and long-term investing. Its central idea is simple: help a parent build a financial routine for a child or teenager through an investing plan, rather than expecting a young person to understand a full brokerage platform on day one.
That simplicity is the app’s biggest strength and also the point where I would set expectations carefully. This is a finance app from Acorns, not a complete replacement for conversations about saving, spending, earning, and risk. I found it most appealing for parents who want to make investing part of a child’s financial education without handing over a dense adult-oriented interface. It is less convincing for families looking for detailed budgeting tools, independent teen banking, or hands-on control over individual investments.
How the app turns a vague money lesson into a family routine
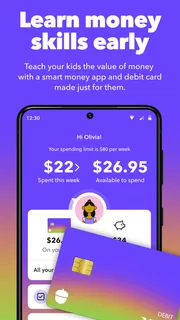
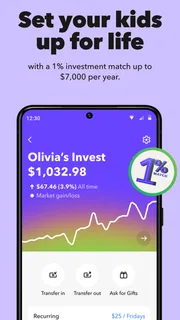
The first useful distinction is that the app is aimed at the parent-child relationship, not simply at children browsing a money game. The store summary focuses on building a child’s or teenager’s financial wellness through a smart investing plan, and that framing matters. The adult remains the person making the important decisions, while the young person can become part of a longer conversation about what money is doing over time.
In practice, I would approach it as a routine rather than a one-time lesson. A parent might open the app during a monthly family check-in, talk about a goal, review how contributions fit into the household budget, and then leave the account alone to develop gradually. That workflow is more realistic than promising a child instant financial independence. The app works best when it supports a repeated habit: explain a decision, connect it to a goal, and revisit the idea later.
One of the less obvious benefits is that an investing plan can make time visible. Children often understand that saving means keeping money, but investing introduces a different question: what might happen when money is left working for a longer period? I would use the app as a prompt for that discussion, while making clear that investing is not the same as a guaranteed savings balance. The parent still needs to explain that values can change and that a long-term plan requires patience.
The app is free to download, which makes trying its basic experience less intimidating for a family that is curious but not ready to commit immediately. I would still distinguish between downloading a finance app and deciding how to use any financial product connected with it. Before setting up a plan, I would read each screen carefully, check the available account details, and make sure the arrangement matches the child’s age, the family’s goals, and the adult’s comfort with investing.
Its Everyone content rating also makes the app feel approachable as a family-facing product. That rating should not be mistaken for a promise that every financial decision is suitable for every child. A young child may need the parent to explain nearly everything, while a teenager may be ready to discuss trade-offs and long-term goals. The same interface can therefore serve different families only if the adult adjusts the conversation around it.
Where the experience feels strongest
My strongest impression is that Acorns Early keeps the focus on starting a child’s financial journey rather than overwhelming the family with market terminology. That is valuable because the main obstacle is often not a lack of interest; it is the friction of choosing an account, understanding the language, and maintaining a habit. A guided, family-oriented investing experience can lower that initial barrier.
I also like the idea of separating the child’s future from the parent’s everyday spending account in the family’s thinking. Even when money is managed by an adult, giving it a named purpose can make it easier to discuss. A parent can say, “This is for a longer-term goal,” instead of treating every saved dollar as part of one indistinct pool. That mental separation is useful whether the eventual goal is education, a first car, or simply giving a teenager a head start.
The app’s appeal is reinforced by its early adoption. It has an average rating of 4.5 from around 3.2 thousand ratings, with more than 500 written reviews and over 100 thousand installs. Those figures do not prove that it will suit every family, but they do suggest that the concept has found an audience beyond a handful of curious testers. I would treat the response as encouraging rather than as a reason to skip the practical questions about investing and account suitability.
Acorns is also a recognizable name in personal finance, and the developer shown for this app is Acorns. That continuity may reassure an existing user who already understands the company’s general approach. For someone new to the brand, however, familiarity should not replace reading the actual terms and reviewing how the child-focused plan works. A trusted interface can make decisions feel easier, but it does not remove the need for an informed adult.
The current version is 9.7.0, and the app supports Android 7.0 and later. That broad device compatibility is helpful for families who do not all use the newest phones. It also means I would check that an older family device runs smoothly before making it the main way a child interacts with the experience. Finance apps need to feel dependable, and a slow or outdated phone can create unnecessary frustration during sign-in or account review.
A realistic family use case
Imagine a parent whose fourteen-year-old has started earning occasional money from chores or small jobs. The teenager wants to spend everything immediately, while the parent wants to introduce a longer view without giving a lecture about retirement. The parent could use Acorns Early to establish a child-focused investing plan, then agree on a simple rhythm: some money can remain available for near-term wants, while another portion is directed toward the longer-term plan.
The important part is not merely pressing a button in the app. The parent can ask the teenager what the money is for, how long it might stay invested, and how it would feel if the value moved down temporarily. That last question is especially important. A child who sees investing only as a faster way to make money may panic when the balance changes. Used properly, the app becomes a visual aid for a conversation about patience and uncertainty.
For a younger child, I would make the routine even simpler. The adult could explain that money is being set aside for a future purpose and avoid turning the child into a daily account watcher. Frequent checking can encourage short-term thinking, which works against the long-term lesson. In my view, the app is better used as a periodic teaching tool than as a screen a child constantly refreshes.
A second useful scenario involves grandparents or relatives who want to contribute to a child’s future. The app may give a family a central place to discuss that intention, but I would not assume that every relative should receive access or that every contribution arrangement is automatically suitable. The parent should decide who needs to know what, keep the child’s privacy in mind, and make sure the family understands the plan before money changes hands.
The trade-off behind the simple approach
The same simplicity that makes the app approachable may leave experienced users wanting more control. Someone who already compares funds, studies tax treatment, or manages several investment accounts may find a child-centered plan too streamlined. That is not necessarily a design failure; it is a sign that the product is aimed at reducing complexity, not maximizing customization.
I would also avoid treating the app as a complete financial education platform. A child still needs to learn how to distinguish a need from a want, build an emergency cushion, recognize misleading offers, and understand that investing carries risk. An investing plan can support those lessons, but it cannot replace them. If a family uses the app as proof that the child is now “good with money,” it is missing the more important work.
Another limitation is emotional rather than technical. Parents may be tempted to use the account as a reward system or as a way to pressure a child into behaving. That can make investing feel like punishment or surveillance. I would keep the account connected to shared goals and explanations, not as a scoreboard for chores or grades. The app is more constructive when the child understands the purpose, even if the adult controls the financial decisions.
Families with urgent short-term needs should think carefully before prioritizing a child’s investing plan. If the household is struggling to cover bills or lacks accessible savings for emergencies, locking attention onto a long-term child goal may not be the best first move. The emotional appeal of investing for a child is strong, but household stability comes before an attractive future plan. In that situation, a straightforward savings method may be more useful and easier to access.
How it compares with familiar alternatives
The closest alternative is often not another investing app but a regular savings account. Savings is easier to explain, the balance is more intuitive, and the money is generally associated with a nearer-term purpose. I would favor that route when the family is saving for something soon or when the child is still learning the basic difference between spending and keeping money. Acorns Early makes more sense when the goal is deliberately long-term and the parent is ready to explain investment risk.
A standard brokerage account can offer more flexibility and a wider range of choices, but that flexibility can become a burden for a parent who simply wants a clear starting point. Adult-oriented platforms may also make it harder to involve a child without exposing them to information they are not ready to interpret. The child-focused direction here is the better fit for families who value a guided experience over detailed control.
Teen banking apps are another different category. They may be stronger for learning how to manage spending, receive money, use a card, or track day-to-day transactions. Acorns Early is not the choice I would make if the immediate lesson is budgeting weekly spending. Its value lies in introducing a longer horizon, so I see it as complementary to practical money management rather than a substitute for it.
Even a simple spreadsheet can be a serious competitor. A parent who enjoys teaching through visible household budgeting might prefer to track goals manually, because that makes deposits, spending, and trade-offs completely transparent. The advantage of the app is convenience and structure; the advantage of a spreadsheet is control and flexibility. I would choose based on which tool the family will actually revisit instead of which one sounds more sophisticated.
Who should use it, and who should wait
I would recommend Acorns Early to a parent who wants to introduce investing gradually, prefers a family-oriented experience, and is comfortable staying involved. It is particularly suitable for a child or teenager who has started asking where money goes but is not ready to manage a complex financial account independently. The app can give the parent a shared reference point for conversations that might otherwise remain abstract.
I would also consider it for an existing Acorns customer who wants to extend a familiar financial habit to a child. The learning curve may feel gentler in that situation, although I would still review the child-specific details separately rather than assuming the adult experience works in exactly the same way.
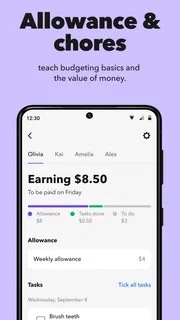
I would skip it, at least for now, if the main need is a spending card, detailed allowance tracking, or a full budgeting dashboard. I would also hesitate if the adult expects the app to teach financial responsibility automatically. A child will learn more from a calm explanation of why a decision was made than from simply seeing an account appear on a phone.
Before starting, I would prepare a short family agreement. Decide what the plan is for, how often it will be reviewed, who makes decisions, and what the child should do when they have questions. I would avoid promising a particular future result, and I would not encourage daily balance checks. Those small choices prevent the app from becoming either a source of unrealistic expectations or another neglected account.
It is also worth deciding how the app fits beside other money tools. If the child already has a savings method, explain what each one is for. For example, savings can serve a near-term purchase while the investing plan is reserved for a goal that can wait. That division gives the child a practical mental model and reduces the chance that they will treat all balances as interchangeable spending money.
My verdict after using it
Acorns Early succeeds because it makes a potentially intimidating subject feel like something a parent and child can approach together. Its best feature is not a flashy trick; it is the focus on a child’s or teenager’s financial future through a structured investing plan. I found that approach more useful than an app that tries to turn money education into a game without connecting it to real family decisions.
Still, I would recommend it with a clear condition: the adult has to provide the context. Investing involves uncertainty, and a young person needs to understand that a long-term plan is not a guaranteed upward line. Families also need everyday lessons about spending, saving, earning, and protecting personal information. The app can support those lessons, but it cannot carry them alone.
Released on November 8, 2024, and available free with an Everyone rating, the app is an accessible starting point for families exploring this subject. Its 9.7.0 release and support for Android 7.0 or later make it practical for a range of devices, while its reception suggests that many users find the overall idea worthwhile. I would not choose it for advanced investors or for a household seeking a complete teen banking system.
My final view is straightforward: Acorns Early is best when it becomes part of a thoughtful family conversation, not a substitute for one. If you want a gentle way to introduce long-term investing to a child or teenager, it is worth exploring. If your priority is immediate spending control, detailed budgeting, or maximum investment choice, a savings tool, teen banking product, or traditional brokerage may serve you better.
Pros and Cons
Pros
- Teaches saving
- spending
- and investing through age-appropriate activities.
- Parents can set goals and monitor progress from one connected account.
- Simple interface makes money concepts accessible to younger children.
- Encourages regular saving habits with visual milestones and rewards.
- Useful tool for starting family conversations about financial responsibility.
Cons
- Some features may require an eligible Acorns subscription or family plan.
- Children may need parental guidance to understand investment-related concepts.
- Limited value for families seeking advanced budgeting or banking tools.
- Availability and features can vary depending on the child’s age and region.
- Requires consistent parent involvement to turn activities into lasting habits.
Advertisements
Other Releases by Acorns
How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 Acorns Early: Kids Money AppAcorns | 4.5 | 100,000+ | Free |
 Google WalletGoogle LLC | 4.4 | 1,000,000,000+ | Free |
| 4.0 | 500,000,000+ | Free | |
 DANA Indonesia Digital WalletPT Espay Debit Indonesia Koe | 4.5 | 100,000,000+ | Free |

Alternatives Worth Trying


More Finance Reviews
View All More Finance Reviews


Frequently Asked Questions
What is Acorns Early: Kids Money App, and who is it designed for?
Acorns Early is a family-focused money app designed to help parents introduce children to saving, spending, and basic financial responsibility. Parents can typically create and manage a supervised account, while children receive an age-appropriate experience for learning about money. It is best suited to families who want practical conversations about allowances, goals, and everyday spending rather than a complex investment platform for children.
How does Acorns Early help children learn about money?
The app encourages children to build healthy money habits through features such as allowance management, savings goals, spending awareness, and parental guidance. In our review, its main strength is making financial lessons more practical: children can connect chores or regular payments with earning, decide how to use money, and see progress toward goals. Parents remain involved, making it easier to explain choices and set boundaries.
Can parents control spending and monitor their child’s activity?
Yes, parental supervision is a central part of Acorns Early. Parents can generally review activity, manage allowances, set expectations, and receive visibility into how the account is being used. Depending on the current plan, region, and account setup, available controls may differ. Before downloading, parents should check the latest terms, supported features, transaction limits, and whether the app meets their preferred level of oversight.
Is Acorns Early safe for children to use?
Acorns Early is built around a parent-managed experience, which is important because children need protection when using financial tools. Parents should create the account, review privacy and security settings, and explain that login details and personal information must never be shared. No financial app should be treated as completely risk-free, so families should also enable device security and regularly check account activity.
Is Acorns Early free, and are there any additional costs?
The cost of Acorns Early can depend on the subscription, membership, account type, and features available in your country. Some services may be included with an eligible Acorns plan, while others can involve recurring fees or specific transaction conditions. Because pricing and benefits may change, check the current App Store or Google Play listing and Acorns’ official pricing information before signing up.
Advertisements

Download Acorns Early: Kids Money App
About This Listing
- Last Checked
- Nov 6, 2026
- Version Reviewed
- 9.7.0
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.