

UKG Wallet
Advertisements
App Specs
- Version
- 1.0.25
- Updated
- Nov 7, 2026
- Android Version
- 10
- Installs
- 100,000+
- Developer
- UKG, Inc.
- Category
- Business
- Content Rating
- Everyone
- Price
- Free
Screenshots
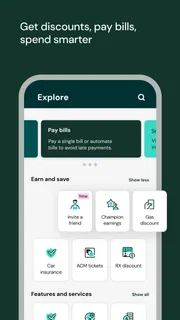
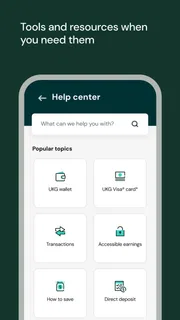
Our Review
 Analysis byUnlimiteds
Getting access to money you have already earned can be more useful than waiting for the normal payday, and that is the central idea behind UKG Wallet. I reviewed it as a business app from UKG, Inc., and my overall impression is that it works best as a practical bridge between work and personal finances rather than as a complete banking replacement. If your employer supports the service, it can make earned wages easier to reach when an unexpected expense appears. If your workplace does not use the relevant UKG setup, however, the app is unlikely to become useful simply because you install it.
That distinction matters. This is not a general budgeting app, a traditional bank account, or a payday-loan alternative. Its value comes from connecting your employment information with access to wages you have already earned. In everyday terms, I see it as a tool for smoothing out timing problems: a bill arrives before payday, a necessary purchase cannot wait, or a small emergency would otherwise force you to rely on an overdraft or borrowed money.
How UKG Wallet fits into real working life
I find it helpful to judge UKG Wallet by the problem I need it to solve: a temporary gap between work already completed and the next payday. Before relying on it, I would confirm that my employer supports the service and decide what expense would justify using early access. That simple check makes it easier to see where this focused approach has an advantage—and where a different kind of financial tool may serve me better.
The app’s strongest idea is timing, not complicated money management
The most convincing part of UKG Wallet is its focus. Many financial apps try to do everything at once, combining spending analysis, savings goals, credit products, investing, and account aggregation. UKG Wallet takes a narrower route by centering the relationship between your work and your earned pay. That narrow purpose can make it easier to understand when you need exactly that kind of help.
I would think of the app as a short-term cash-flow tool. Suppose I have worked several shifts during the week, but my regular payday is still a few days away. A car repair, prescription, or utility payment could create a problem even though the money is technically on its way. In that situation, access to earned wages may be more sensible than putting the expense on a high-cost credit product. The app’s usefulness is therefore tied to the gap between when work happens and when payroll normally arrives.
That does not mean every earned dollar should be moved immediately. One of the more important judgments is deciding whether early access actually solves a problem or merely makes the next payday feel smaller. I would use it deliberately, for a defined expense, rather than treating available wages as extra income. That habit keeps the tool focused on cash-flow relief instead of turning it into a reason to spend more often.
A realistic scenario where it earns its place
Imagine a retail employee who has completed most of a pay period when a tire develops a serious leak. The employee has income coming, but the repair cannot reasonably wait until the scheduled payroll date. With UKG Wallet available through the employer, the employee may be able to use earned wages to cover the immediate need instead of missing work, delaying the repair, or using a more expensive form of credit.
That is a much stronger use case than withdrawing money for routine impulse purchases. The app makes the most sense when timing is the problem and the underlying income is dependable. It can also be useful for workers whose hours vary, because the distance between completed work and the next paycheck can feel more significant when weekly expenses remain fixed.
I would still pause before every transfer and ask three questions: Is this expense necessary, have I already earned the amount I need, and will accessing it now make the next payday difficult? Those questions are not built-in magic, but they are the practical discipline that makes an earned-wage app helpful rather than stressful.
What the adoption figures suggest, without mistaking popularity for fit
The app has an average rating of 4.5 from around twelve thousand ratings, alongside roughly 1.9 thousand written reviews. It has also passed one hundred thousand installs. Those figures indicate that UKG Wallet has found a meaningful audience, but they do not guarantee that it will work the same way for every employee. Employer integration is the deciding factor, so a strong public reception should be treated as encouragement, not proof of universal compatibility.
I also appreciate that the app is free to install and carries an Everyone content rating. That makes it approachable for a broad working audience, although “free” should not be confused with “every possible transaction or service is cost-free.” Before relying on early access, I would read the in-app terms carefully and pay attention to any information shown during a transfer. The important question is the total practical cost and timing, not just the download price.
The employer connection changes the whole experience
Unlike a standalone finance app, UKG Wallet depends heavily on the workplace relationship behind it. UKG, Inc. is the developer, but the employee’s experience is also shaped by whether the employer has enabled the service and how payroll information reaches the wallet. This is why I would begin by checking with the workplace or payroll contact rather than assuming the app alone can create access.
That dependency is both a strength and a limitation. When the employment connection is working, the app’s purpose is clearer than a generic cash-advance service because it is tied to wages already earned. When the connection is missing, delayed, or difficult to establish, there may be little the user can do from the phone itself. In that situation, contacting payroll is more productive than repeatedly reinstalling the app or changing personal banking details.
A useful workflow is to set up the account when you are not under pressure. I would verify the employment connection, review how available wages are presented, and understand the steps for receiving money before an emergency occurs. Learning the process during a calm week is much better than trying to solve a financial problem while also navigating account setup.
Where it compares well with common alternatives
The usual alternatives fall into several groups. A traditional bank account is better for storing money, paying bills, and managing a longer-term financial routine. A budgeting app is better for seeing spending patterns and planning future expenses. A credit card may offer convenience and purchase protections, but it can also create a balance that lasts beyond the original emergency. Borrowing from friends or family may avoid formal costs, yet it can bring its own social pressure.
UKG Wallet occupies a different position. Its strongest advantage over a general budgeting app is that it addresses access to earned pay rather than merely showing where money went. Its advantage over a credit product is that the underlying source is wages already earned, not a new line of debt. Its weakness compared with a bank account is that it is not designed to replace the broader set of services people expect from everyday banking.
For someone who needs detailed spending categories, long-term savings tools, or a consolidated view of several financial accounts, a dedicated personal-finance app will probably be more useful. For someone facing a short gap before payday, UKG Wallet is more directly relevant. The right choice depends less on which app has more features and more on whether the user’s actual problem is wage timing.
The meaningful limitation: access is not the same as financial flexibility
The main weakness is easy to overlook because the concept sounds straightforward. Early access can improve the present week while reducing what arrives on the scheduled payday. The app may help with a genuine emergency, but it cannot increase total earnings or fix a recurring mismatch between income and expenses.
That makes repeated use a warning sign. If I needed the wallet every pay cycle for groceries, rent, or transportation, I would treat that pattern as evidence that my budget or income schedule needed a broader solution. The app can soften a timing problem, but it should not be expected to repair an ongoing shortfall. A conversation with an employer about payroll timing, a revised spending plan, or independent financial guidance may be more appropriate in that case.
There is also a psychological trade-off. Seeing wages available before payday can make them feel like spare money, even though they are part of the same pay period. I would avoid opening the app casually when I am tempted to spend. Using it only for a named need creates a simple boundary and reduces the risk of turning convenience into a habit.
Questions I would settle before depending on it
The first question is whether my employer supports the service. This is the essential starting point, because UKG Wallet is not a universal wage-access tool that works independently of payroll. I would confirm eligibility through the workplace and make sure the employment information shown in the app matches my current job.
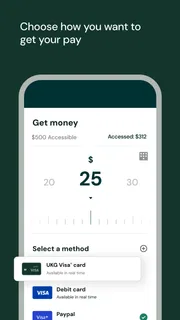
The second question is how quickly money becomes usable after requesting access. Timing matters when the app is being considered for a bill or emergency. I would review the available delivery choices and any timing information presented before submitting a request, rather than assuming that every transfer is immediate.
The third question is what happens to the regular paycheck after using early access. I would want to understand how the amount already received affects the later payroll deposit and whether the app clearly shows that relationship. A transparent view of the remaining pay is important because it helps prevent accidental overspending before payday.
The fourth question is what to do if the wage amount looks wrong or does not appear. In that situation, I would compare the app’s information with my recorded hours and then contact the employer’s payroll or HR team if necessary. Because the service depends on employment records, some problems may need to be corrected outside the app.
Finally, I would ask whether the app suits my financial habits. If I am already struggling to keep enough money for the end of each pay period, early access might offer temporary relief but also make the cycle harder to break. If I mainly need occasional help with a specific, unavoidable expense, the same tool could be much more sensible.
Small workflow choices that make a real difference
My first practical tip is to establish a personal rule before using the wallet. For example, I would reserve it for transportation, urgent household repairs, medical necessities, or another clearly defined need. This is more useful than relying on willpower at the moment money becomes available.
My second tip is to check the next payday budget immediately after accessing wages. I would list the bills that still need to be covered and subtract the amount already received mentally or on paper. That extra step turns the wallet from a source of temptation into a cash-flow planning tool.
My third tip is to keep records of transfers for a few pay cycles. I would note why I used the service, how much I accessed, and whether the following payday felt manageable. This creates personal evidence about whether the app is solving occasional timing issues or masking a deeper budget problem.
A fourth useful approach is to set up and test understanding before an urgent situation. I would read the screens carefully, learn where wage availability is displayed, and identify the right workplace contact for payroll questions. That preparation is especially valuable for employees with variable shifts, where an apparent difference in available wages may require checking hours or payroll timing.
Who should use it, and who should choose something else?
UKG Wallet is a strong candidate for employees whose workplace supports it and who occasionally need access to wages before the normal payroll date. It is particularly suitable for people dealing with irregular expenses, variable hours, or a narrow gap between necessary spending and payday. The free app and Everyone rating also make it easy to consider without a large commitment.
I would recommend it more cautiously to anyone who already relies on early access repeatedly. The service may still be useful, but repeated dependence suggests that another solution should accompany it. A bank account is better for everyday money management, a budgeting tool is better for planning, and a financial counselor or employer conversation may be better when expenses consistently exceed available income.
I would skip it if I am looking for investing, detailed financial reporting, a full digital banking relationship, or a broad collection of money-management features. That is not a failure of the app; it is simply outside its central job. Installing it will not turn it into a replacement for those tools.
My verdict after looking at the whole experience
UKG Wallet has a clear and worthwhile purpose: it helps eligible employees think about earned wages as accessible support when payday timing creates pressure. I like that its best use is easy to explain, and I find the employer connection more meaningful than the vague promises common in financial apps. When used for a specific need, it can be a practical alternative to taking on expensive short-term debt.
At the same time, I would not present it as free money or a complete financial solution. Its usefulness depends on workplace participation, the accuracy of payroll information, and the user’s ability to plan for the reduced amount arriving later. Those conditions are not minor details; they determine whether the app provides relief or simply moves the same pressure to another date.
The current version is 1.0.25, and the app was released on December 21, 2021, giving it an established place among workplace-focused financial tools. My recommendation is straightforward: if your employer supports UKG Wallet and you occasionally need to bridge a short gap before payday, it is worth trying. Use it with a clear purpose, check the effect on your next paycheck, and keep a separate budget for longer-term stability. Its real strength is controlled access to earned pay, not replacing the rest of your financial life.
Pros and Cons
Pros
- Supports convenient mobile access to payroll and HR information.
- Useful for checking pay details
- tax documents
- and personal records on the go.
- Can reduce the need to contact HR for routine information.
- Provides a centralized place for workplace-related updates and tools.
- Helpful for employees who frequently work remotely or across locations.
Cons
- Features may vary depending on your employer’s UKG configuration.
- Requires valid workplace credentials and may not work for former employees.
- Some actions redirect to web pages rather than staying fully in-app.
- Performance can depend on your company’s server and account setup.
- Access to sensitive payroll data makes device security especially important.
Advertisements
Other Releases by UKG, Inc.
View All Other Releases by UKG, Inc.


How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 UKG WalletUKG, Inc. | 4.5 | 100,000+ | Free |
 Zoom Workplacezoom.com | 4.1 | 1,000,000,000+ | Free |
 LinkedIn: Community & NetworkLinkedIn | 3.9 | 1,000,000,000+ | Free |
 Microsoft TeamsMicrosoft Corporation | 4.6 | 500,000,000+ | Free |
Alternatives Worth Trying


More Business Reviews
View All More Business Reviews


Frequently Asked Questions
What is UKG Wallet and what can it be used for?
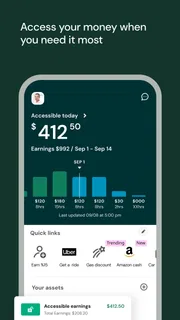
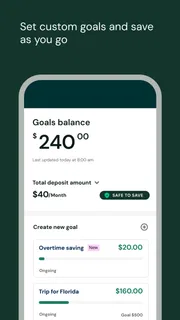
UKG Wallet is a financial wellness and earned-wage-access app designed for eligible employees. Depending on how an employer has configured the service, users may be able to view earned wages, request access to part of their available pay before payday, review account activity, and manage related financial tools. Available features can vary by employer, payroll setup, location, and employment status.
Who can use UKG Wallet, and is it available to everyone?
UKG Wallet is generally intended for employees whose organizations support the service through an eligible UKG payroll or workforce-management setup. Downloading the app alone does not guarantee access. Your employer must participate, your payroll information must be connected correctly, and you may need to meet specific eligibility requirements. If registration fails, contact your employer’s HR or payroll department.
How does early wage access work in UKG Wallet?
When enabled by your employer, UKG Wallet may show a portion of wages you have already earned but have not yet received through the normal payroll cycle. You can request an available amount and choose an approved delivery method, subject to limits, verification, and applicable fees. Early access reduces the amount paid on your regular payday, so review the details carefully before confirming a transfer.
Are there fees or other costs for using UKG Wallet?
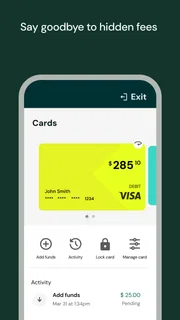
Some UKG Wallet services may be free, while others—particularly expedited transfers or optional financial products—can involve fees. The exact pricing depends on your employer’s program, location, transfer method, and the features you select. Before submitting a request, check the transaction summary for any displayed charges, processing times, and the amount that will remain for your scheduled paycheck.
Is UKG Wallet safe, and what should I do if I cannot log in?
UKG Wallet uses account authentication and security measures intended to protect employee and payroll information, but users should still choose a strong, unique password and avoid sharing verification codes. If you cannot log in, update the app, check your connection, and use the official recovery options. For employer eligibility, payroll mismatches, or account verification issues, contact your HR or payroll administrator.
Advertisements

Download UKG Wallet
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 1.0.25
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.