

BILL AP & AR Business Payments
Advertisements
App Specs
- Version
- 3.7.171
- Updated
- Nov 7, 2026
- Android Version
- 9
- Installs
- 500,000+
- Developer
- Bill.com Inc.
- Category
- Business
- Content Rating
- Everyone
- Price
- Free
Screenshots
Our Review
 Analysis byUnlimiteds
When a small business has bills arriving in different formats and customers paying on different schedules, the difficult part is rarely the act of sending money. The real problem is keeping the whole chain visible: what needs approval, what has already been paid, which customer is late, and who needs to act next. I tested BILL AP & AR with that everyday problem in mind, and I found it most useful as a mobile companion for organizing payable and receivable work rather than as a complete replacement for every accounting tool.
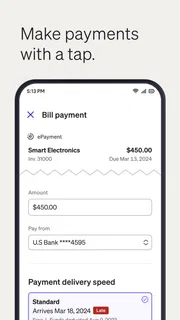
The app sits in the Business category and comes from Bill.com Inc. It is free to download, suitable for Everyone, and available for devices running iOS 9 or later. Its focus is straightforward: helping a business pay bills and get paid online. That sounds simple, but the value becomes clearer when I follow a payment from the moment an invoice arrives to the point where someone checks the result.
My overall view is that BILL AP & AR works best when a business already has a payment routine and wants a more convenient way to keep that routine moving. It can reduce the need to handle every task from a desktop, especially when an owner or manager is away from the office. However, people looking for a full bookkeeping system, detailed financial reporting, or a simple personal bill-payment app may find its business-first approach more involved than necessary.
From an incoming bill to a completed payment
I’d use this section to trace one bill through the decisions that matter: who checks it, what should prompt a pause, and how the team keeps the next step clear. A useful habit is to treat an approval as a review, not a reflex; when an amount or supplier detail looks unfamiliar, resolving that question first is better than letting mobile convenience rush the payment.
The starting condition: payment work is scattered
I would begin using this app when bills are already coming into the business through several channels and accounts receivable is becoming difficult to monitor. A supplier may be waiting for payment while a customer has an unpaid invoice, and the person responsible for approving one item may not be the person who actually sends the money. That separation creates small delays that are easy to miss during a busy day.
BILL AP & AR is designed around both sides of that situation. The “AP” side addresses accounts payable, where the business owes money. The “AR” side addresses accounts receivable, where customers owe the business. Keeping both directions in the same business-payment environment is useful because cash flow is not only about outgoing payments. It is also about knowing when incoming money should arrive.
Before relying on it, I would make one practical decision: define who owns each stage. If one person enters bills, another approves them, and a third person watches incoming customer payments, the app will only help if those responsibilities are clear outside the screen as well. No payment app can fix an approval process that nobody has agreed on.
Step one: prepare the payable side
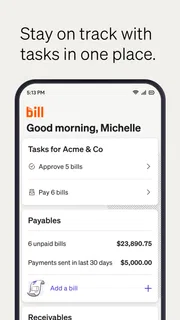
On the accounts-payable side, I would use the app as the place to review obligations before they become urgent. The useful habit is not simply opening it when a payment is late. It is checking pending work regularly, identifying which items need attention, and separating routine payments from those that require a manager’s decision.
This is where the mobile format makes sense. A business owner who is travelling, visiting a job site, or moving between meetings may not want to wait until returning to a computer before reviewing a payment task. The app gives that person a way to stay involved in the workflow without treating every decision as an office-only activity.
My advice is to avoid approving items too quickly just because they appear familiar. A recurring supplier name does not automatically mean the amount or timing is correct. I would use the mobile review as a checkpoint, then compare the bill with the company’s own records whenever something looks unusual. The app can make the process more accessible, but careful review still belongs to the person approving the payment.
Step two: move through approval instead of losing the handoff
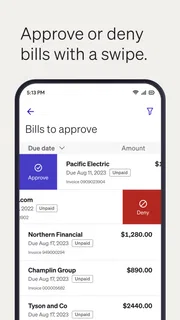
The most important part of this kind of workflow is the handoff between the person who receives or prepares a bill and the person who authorizes payment. In many small companies, that handoff happens through email, chat messages, or a paper folder. Those methods can work, but they make it harder to tell whether an item is waiting, rejected, or already dealt with.
I found the app’s strongest practical role here is keeping the payment task connected to the business process. The person responsible for the next action can work from the same payment environment rather than relying on a message such as “please take a look at this invoice.” That reduces the chance that an approval request is buried under unrelated conversation.
There is still friction if the company has complicated approval rules. A larger organization may need more specialized controls, accounting integrations, audit procedures, or role management than a mobile payment application can comfortably provide. For a small team, the simpler flow may be an advantage. For a department with several layers of authorization, I would test the workflow carefully before moving all payment activity into it.
Step three: handle incoming customer payments
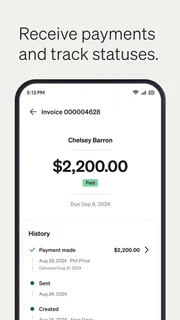
The accounts-receivable side changes the direction of the workflow. Instead of asking whether the business has paid a supplier, I would use it to keep track of money that should be coming in from customers. This matters for a contractor waiting on a completed project, a consultant billing several clients, or a small company trying to avoid surprises between payroll and supplier deadlines.
What I like about combining payable and receivable work is the possibility of looking at both pressures together. If several customer payments are still outstanding, that context may influence how an owner plans outgoing payments. The app does not turn cash-flow management into an automatic decision, but it can make the relationship between money owed and money expected easier to follow.
A useful everyday routine would be to review receivables before committing to non-urgent expenses. I would check which customers have outstanding obligations, decide whether a reminder or follow-up is appropriate, and then review the bills waiting on the payable side. That sequence is more useful than checking only the bank balance, because a bank balance shows the present while receivables and payables show what may happen next.
A realistic day with the app
Imagine a small design studio on a Monday morning. A printer has submitted a bill, a freelance specialist is waiting for payment, and a client has not yet paid for the previous project. The studio owner is away from the desk but needs to make decisions before the afternoon.
I would start by reviewing the incoming bills and checking whether the printer’s charge is ready for approval. If the bill is routine, I could move it through the established process. If the amount needs clarification, I would leave it for follow-up rather than approving it simply to clear the list. Next, I would review the unpaid client item and decide whether the account manager should contact the client. Finally, I would look at the remaining outgoing obligations and consider which ones can be scheduled responsibly.
The outcome is not merely that a payment was sent. The better outcome is that each item has a visible next step: approve, investigate, follow up, or wait. That distinction is important. A payment app becomes genuinely useful when it prevents uncertainty, not just when it processes a transaction.
Where the handoffs can still fail
Mobile access does not eliminate human delay. If the person who approves payments rarely opens the app, the workflow may still stop. If a bill is entered with incomplete information, the next person may have to search through email or ask the supplier for clarification. If the receivables owner does not update the team after contacting a customer, other decisions can still be made using outdated expectations.
I would therefore establish a short internal rule before adopting the app: every pending item must have an owner and a next action. That simple rule adds more value than installing the app alone. It also makes it easier to see whether the problem is the payment process or the company’s communication habits.
What the result looks like
When the workflow is set up sensibly, the result is a cleaner view of business payments. Bills are less likely to sit unnoticed, approvals can happen away from a desktop, and incoming customer obligations are considered alongside outgoing commitments. For a small operation, that can make the owner feel less dependent on one employee’s inbox or one computer in the office.
The app’s public reception supports the idea that it has found a practical audience: it holds a 4.3 average from around 7,500 ratings, with roughly 1,500 written reviews and more than 500,000 installs. I do not treat those figures as proof that every business will have a smooth experience, but they do suggest that the product is established enough to be considered by teams that need mobile access to business payments.
Its current version is 3.7.171, and the product has been available since December 16, 2015. That history matters to me less as a badge than as a sign that this is not a brand-new experiment. Still, an established app can retain workflows that feel designed for business administrators rather than casual users, so I would judge it by the needs of the team using it.
Three less-obvious ways I would use it
First, I would use the payable and receivable views as a weekly conversation starter rather than waiting for a month-end review. A short check of what is waiting on both sides can reveal a timing problem before it becomes a cash-flow emergency. This is especially helpful when the owner handles finance between operational tasks.
Second, I would treat mobile approval as a controlled exception to the normal office routine, not as permission to approve everything from anywhere without context. When travelling, I would clear straightforward items and hold anything that needs supporting information. That keeps convenience from weakening oversight.
Third, I would use the app to identify process bottlenecks. If bills repeatedly wait for the same handoff, the issue may be an unclear responsibility rather than a missing feature. Looking at which stage keeps slowing down can help a small business redesign its routine, even if the app itself does not solve the organizational problem.
How it compares with familiar alternatives
The usual alternative is a combination of online banking, email approvals, spreadsheets, and accounting software. That combination may be enough for a very small business with only a few monthly payments. It can also be cheaper in terms of changing established habits, because everyone already knows how to use it. The trade-off is that the process is spread across several places, making status and responsibility harder to follow.
Compared with a general accounting package, BILL AP & AR feels more focused on the movement and coordination of bills and customer payments. A full accounting system is usually the better choice when the main need is bookkeeping, tax preparation, financial statements, inventory, or broad reporting. I would not choose this app alone as the financial foundation for a business that needs all of those areas managed together.
Compared with a bank’s bill-pay feature, its business workflow is the more relevant distinction. Bank tools are convenient for sending money, but they may not provide the same sense of a payable item moving through preparation, review, and approval. On the other hand, a bank remains the final place where account balances and transaction activity matter, so I would still verify important payments there rather than treating any single app as the only source of truth.
Who should use it, and who should skip it
I would recommend trying BILL AP & AR if you run a small or growing business, share payment responsibilities with one or two colleagues, or need to review bills while away from a desktop. It is also a sensible option for someone who wants accounts payable and accounts receivable considered in the same daily routine instead of maintaining separate reminders for each.
I would be more cautious if you are searching for a personal finance app, a simple way to pay household utilities, or a full enterprise finance platform. The business terminology and workflow may feel excessive for personal use, while larger teams may require deeper controls and reporting. A company with very unusual approval requirements should also test a representative process before committing.
Because the app is free and rated for Everyone, trying it does not require treating it as an immediate long-term commitment. Even so, I would not rush the setup. Decide who can prepare, approve, and follow up on payments, then run a few ordinary bills and one receivable cycle through the process. That trial will reveal more than a quick glance at the feature summary.
My final assessment after following the full flow
BILL AP & AR is most convincing when the problem is scattered business-payment work, not when the problem is accounting in general. I like the way it frames outgoing bills and incoming customer payments as connected parts of a working business. The mobile angle is genuinely useful for owners and managers who need to keep approvals moving during the day.
Its limitations are tied to that same focus. It depends on disciplined handoffs, clear ownership, and sensible review habits. It cannot make an unclear internal process clear by itself, and it may not satisfy a business that needs comprehensive accounting or complex financial administration in one place.
For the right user, I would recommend giving it a structured trial: start with a small set of routine bills, include the people who approve and follow up, and judge whether each item reaches a clear outcome without extra chasing. If that test reduces the number of forgotten approvals and makes unpaid customer work easier to discuss, the app earns its place in the workflow. If your needs are mainly personal payments or full-scale bookkeeping, I would choose a tool built specifically for those jobs instead.
Pros and Cons
Pros
- Streamlines invoice creation
- tracking
- and payment collection in one place.
- Supports better visibility into accounts receivable and outstanding balances.
- Can reduce manual data entry and help minimize payment-processing errors.
- Useful payment records make reconciliation and cash-flow monitoring easier.
- Designed to support recurring business payment workflows and routine billing tasks.
Cons
- May require setup and training before teams can use every feature efficiently.
- Advanced tools may be more useful to larger businesses than small occasional billers.
- Payment availability can depend on supported currencies
- banks
- or regional services.
- Users may need to verify integrations carefully before connecting financial accounts.
- Businesses should review transaction fees and subscription costs before committing.
Advertisements
Other Releases by Bill.com Inc.
View All Other Releases by Bill.com Inc.How It Compares
| App | Rating | Installs | Price |
|---|---|---|---|
 BILL AP & AR Business PaymentsBill.com Inc. | 4.3 | 500,000+ | Free |
 Zoom Workplacezoom.com | 4.1 | 1,000,000,000+ | Free |
 LinkedIn: Community & NetworkLinkedIn | 3.9 | 1,000,000,000+ | Free |
 Microsoft TeamsMicrosoft Corporation | 4.6 | 500,000,000+ | Free |
Alternatives Worth Trying


More Business Reviews
View All More Business Reviews


Frequently Asked Questions
What is BILL AP & AR Business Payments used for?
BILL AP & AR Business Payments is designed to help businesses manage accounts payable and accounts receivable in one place. After reviewing the app, its main purpose is to simplify paying vendors, sending invoices, tracking incoming payments, and organizing transaction records. It is aimed primarily at companies and finance teams rather than personal users managing everyday household bills.
Can I use BILL AP & AR Business Payments to pay vendors and receive customer payments?
Yes. The platform supports both sides of business payment management. You can use it to schedule or send payments to vendors and to create, deliver, and monitor invoices for customers. The exact payment methods, processing times, and available features may depend on your account type, business location, and the payment options accepted by the recipient, so reviewing the terms before sending money is recommended.
Is BILL AP & AR Business Payments suitable for small businesses?
The app can be useful for small businesses that want to replace scattered spreadsheets, email threads, and manual payment tracking with a centralized workflow. It may help owners and bookkeepers save time by organizing bills, invoices, approvals, and payment status. However, pricing, transaction fees, user limits, and accounting features should be checked carefully, since the most suitable plan depends on payment volume and business needs.
Does BILL AP & AR Business Payments integrate with accounting software?
Integration with accounting tools is one of the platform’s key advantages because it can reduce duplicate data entry and make financial records easier to maintain. Depending on the subscription and supported software, users may be able to synchronize bills, invoices, vendors, customers, and payment information. Before downloading or subscribing, confirm that your accounting system and required synchronization features are supported in your region.
Is BILL AP & AR Business Payments secure, and what should I know before using it?
Because the app handles sensitive business and banking information, security is an important consideration. BILL uses account protections and controlled payment workflows, but users should still enable available security measures, create a strong unique password, and carefully verify vendor banking details before approving transactions. Also review transaction fees, cancellation rules, approval permissions, and customer support options before relying on the service for critical payments.
Advertisements

Download BILL AP & AR Business Payments
About This Listing
- Last Checked
- Nov 7, 2026
- Version Reviewed
- 3.7.171
- Source
- Official Stores
This listing provides independent information about Unlimiteds. We do not own, develop, or distribute this app. All names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer through the links listed on this page.